Close Menu

    Subscribe to Updates

    Get the latest creative news from FooBar about art, design and business.

    What's Hot

    Social Security COLA 2027: What the 3.6% Raise Means for Your Monthly Plan

    November 6, 2026

    Best Free Budget Apps in 2026: iPhone, Android, and Web

    November 6, 2026

    Federal Pay Period Calendar for 2027: Every Pay Period and Payday

    November 6, 2026
    Facebook X (Twitter) Instagram
    Amppfy
    • Safe to Spend™ App
      • Amppfy on iPhone — one clear number with the status scale and the math under itYour number, in your pocketFree on iPhone and Android, with the same account on the web.
        • Download on the App Store
        • Get it on Google Play
        • Prefer the web? Sign up free ›
      • The app
        • OverviewOne clear number for what’s safe to spend before payday
        • Safe-to-Spend™The four-line math, always shown
        • Weekly check-inTen minutes a week keeps it honest
      • Features
        • Bills & paydaysEvery bill and payday on one calendar
        • GoalsSavings that fund themselves first
        • For couplesTwo logins, one number you both trust
        • SubscriptionsWhat you pay monthly, and what cancelling gives back
        • Calendar & heads-upsYour month at a glance, a heads-up before bills land
        • Net worth & payday nudgeThe whole picture, month by month
        • BudgetWhere the month’s money goes, month by month
      • Trust & help
        • Security & privacyJust your balances, optional two-step verification
        • Help centerSetup, the number, check-ins, FAQ
        • Open the web appSame account, any browser
    • Budget & Save
      • Budget & SaveOne number for what’s safe to spend before paydayBudgeting that starts from your balances, not a spreadsheet.Explore Budget & Save ›95 guides · 482 articles
      • Budgeting
        • Budgeting basics
        • Start a budget
        • Monthly budget
        • Budget methods
        • 50/30/20 budgeting
        • Zero-based budgeting
        • Budgeting mistakes
        • Budgeting tips
        • Budgeting tools
        • Couples budgeting
        • Family budgeting
        • Vacation budgeting
        • How to budget and save money
        • Common Budgeting Mistakes and How to Fix Them
        • 5 Steps to Stop Living Paycheck to Paycheck
        • Are You Living Paycheck to Paycheck?
        • How to Build a Simple Monthly Budget You’ll
        • Best Budgeting Apps Compared
        • Cut Recurring Costs
        • How to Track Every Dollar
        • 5 Easy Budgeting Apps You Need to Try
        • How to Cut Household Expenses Without Feeling
        • Budget Repair for Ages 18–28 with $30–50k Income
        • Beginner’s Guide to Creating a Monthly Budget
      • Saving
        • Savings
        • Savings goals
        • Savings plan
        • Savings buckets
        • Sinking funds
        • Cut expenses
        • Groceries savings
        • Smart saving strategies
        • Saving in a recession
        • Savings tips
        • Savvy saver
        • Maximize your savings
        • Debt-to-Income Ratio Calculator
        • Savings Calculator
        • Savings Goal Calculator to Help You Master Your
        • Monthly 50/30/20 Budget Calculator to Maximize
        • When to Use a High-Yield Savings Account vs
        • 14 Simple Ways to Cut Monthly Expenses
        • How to Set Up Savings Buckets in 20 Minutes
        • How to Create a Savings Plan
        • How to Build a 6-Month Savings Plan for Financial
        • How to Set Realistic Savings Goals and Hit Them
        • The 52-Week Savings Challenge
        • How to Maximize Savings
      • Emergency fund
        • Emergency fund
        • How much to save
        • Where to keep it
        • Rainy day fund
        • Emergency savings
        • Emergency buffer
        • Best emergency fund tips
        • Emergency Fund Calculator
        • Building a Rainy Day Fund
        • How to Calculate Your Emergency Fund
        • Sinking Funds vs. Emergency Fund
        • 5 Best High-Yield Savings Accounts for Emergency
        • Emergency Funds
        • Why an Emergency Fund Is Non-Negotiable
        • Why an Emergency Fund Is Crucial for Financial
        • Millions Can’t Cover an Emergency Expense. Here’s
        • 5 High-Liquidity Places to Park Your First $1,000
        • Saving Strategies for Emergency Funds and Retirement
        • Short-Term Savings Goals vs Emergency Fund
        • Emergency Fund Explained
        • Emergency Fund vs. Investing
        • Emergency Fund Guide
        • How Much Emergency Fund Do You Need?
        • Build Your Emergency Fund Fast
      • Money habits
        • Money management
        • Money management basics
        • Money habits
        • Money mindset
        • Money matters
        • Monthly financial reviews
        • Spend tracking
        • Smart spending
        • Cash flow
        • Net worth
        • Know your money
        • Financial literacy
        • Net Worth Calculator
        • How to Calculate Your True Debt-to-Income Ratio
        • What a Simple 7-Question Money Quiz Reveals About
        • Do Personal Money Management Tools Work?
        • The 3 Key Personal Finance Metrics Every Household
        • How to Build a Simple Monthly Financial Review Habit
        • Beginner’s Guide to Tracking Spending
        • Building a Savings Habit
        • What Is Financial Literacy?
        • Are Financial Advisor Fees Negotiable?
        • Psychology of Money Management
        • Should You Skip That Charitable Donation at the
      • Financial planning
        • Financial planning
        • Financial goals
        • Financial wellness
        • Financial freedom
        • Financial independence
        • Financial resilience
        • Financial self-assessment
        • Finance
        • Finance tips
        • Compound interest
        • Long-term wealth
        • Wealth building
        • Life-stage financial planning
        • Compound Interest Calculator
        • The Cashflow Calendar
        • What to Expect When Meeting with a Financial Advisor
        • How to Map Short, Medium, and Long Financial Goals
        • Financial Independence Roadmap
        • 50/30/20 Budget Rule
        • Personal Finance Mastery
        • How to Start a Budget
        • 5 Proven Saving Strategies to Reach Your Financial
        • Steps to Build Financial Resilience for Life Events
        • The Ultimate Guide to Financial Literacy
      • Income
        • Side hustles
        • Side hustle ideas
        • Side income
        • Extra income
        • Using extra income
        • Passive income
        • Gig economy
        • Gig work
        • Gig earnings
        • Freelance finance
        • Irregular income
        • Online income
        • Renting out assets
        • Selling unused items
        • Small business ideas
        • How to make money online
        • Salary
        • Selling Handmade Crafts Online
        • 10 Side Hustles You Can Start this Weekend
        • How to Start Freelance Writing
        • Budgeting for Irregular Income
        • Short-Term Income Boosters
        • Explore the Lucrative World of Delivery Driving
        • Building Your Credit as a Gig Worker
      • Family & life events
        • Family finance
        • Family costs
        • Family financial education
        • Teen money skills
        • New immigrant finance
        • Recovery after job loss
        • Healthcare costs
        • Healthcare savings
        • Cost of living
        • How to Rebuild Savings After a Job Loss
        • 529 Plans 101
        • How to Teach Financial Literacy to Teenagers
        • Real Cost of Raising Two Kids
        • Family Budgeting
        • Family of Four Budget
        • Winter Break Childcare
        • Thanksgiving Hosting on a Budget
        • Gifts for Kids on a Tight Pay Cycle
        • The Small Holiday Costs That Add Up
        • Holiday Gift Budget for Couples
        • Gift Cards After the Holidays
        • Holiday Returns and Refunds
        • Holiday Spending on a Pay Schedule
        • When Your Payday Moves Early
      • Big purchases & cars
        • Major money decisions
        • Major purchase planning
        • Major purchases
        • Buying a car
        • Buying a used car
        • Car buying
        • Moving expenses
        • How to Plan for a Major Purchase Without Going into
        • What to Check When Buying a Used Car
        • A Beginner’s Guide to Car Buying
        • Insurance in a Household Budget
        • Transportation Budget
        • First Paycheck, First Lease
        • Moving Without Draining Your Account
        • How Much Should You Keep for Car Repairs?
        • Saving for a Car Down Payment on a Paycheck Schedule
        • Moving In Together
        • Car Insurance Due in One Lump?
        • Should Your Car Count Toward Net Worth?
      • Money & the economy
        • The economy
        • Economic trends
        • Jobs report
        • U.S. financial system basics
        • Personal finance news
        • Free Interest Rate Calculator
        • Managing Your Savings During a Recession
        • Emergency Fund for a Recession
        • How to Navigate US Financial Systems as a New
        • How to Manage Your Savings During a Recession
        • Social Security COLA
        • Gig Economy Playbook
    • Debt & Credit
      • Debt & CreditPay it down, then make your score work for youPayoff plans that fit a pay cycle, and the credit moves that stick.Explore Debt & Credit ›36 guides · 109 articles
      • Pay off debt
        • Debt payoff
        • Debt-free journey
        • Credit card debt
        • Debt consolidation
        • HELOC payoff strategy
        • Debt as a single parent
        • Debt-Snowball vs. Debt-Avalanche
        • The Pros and Cons of Debt Consolidation
        • Debt Snowball vs Avalanche
        • Consolidating Debt
        • Saving for a Wedding Without Going Into Debt
        • Emergency Buffer While Paying Down Debt
        • How to Build a Realistic 6-Month Debt Payoff
        • Rolling Over a 401 to Pay Down Debt Without
        • Payoff Strategies for Single Parents with Multiple
        • How to Use Extra Cash to Crush Debt Fast
      • Loans
        • Student loans
        • Auto loans
        • Auto loan debt
        • Personal loans
        • Personal loan debt
        • Personal loan refinance
        • Refinancing a personal loan
        • Medical debt
        • How to Refinance a Personal Loan
        • Can You Refinance a Personal Loan?
        • What to Know Before Taking Out a Personal Loan
        • How to Deal With Personal Loan Debt
        • 5 Tips for Paying Off Your Auto Loan Early
        • Best Personal Loans
        • When to Refinance a Personal Loan
        • Student Loan Repayment Options
        • Medical Debt in America
        • Medical Debt Explained
        • Student Loans 101
        • Dealing With Student Loans
        • Auto Loans Explained
        • Budgeting with a High-Interest Personal Loan
        • Fast and Simple Auto Financing
        • Creating a Debt-Repayment Fund for Unexpected Loans
      • Credit score
        • Credit score
        • What credit scores mean
        • How credit scores are calculated
        • Checking your credit score
        • Improve your credit score
        • Build credit
        • Credit health
        • Credit reports
        • Credit basics
        • Credit for gig workers
        • How to Remove Negative Items from Your Credit Report
        • How to Build Credit
        • Understanding Credit Utilization
        • What Is Credit?
        • How to Build Credit From Scratch at Any Age and
        • How to Start or Rebuild Credit
        • Credit Utilization
        • How Long Do Negative Marks Stay on Your Credit
        • How to Read Your Credit Report and Dispute Errors
        • How to Check and Improve Your Credit Score
        • How Long Negative Items Stay on Your Credit Report
        • Credit Score 101
        • Dispute a Credit Report Item
        • Medical Bills on Your Credit Report
      • Credit cards
        • Credit cards
        • Credit cards for beginners
        • Credit card rewards
        • Balance transfer cards
        • Best Credit Cards to Build or Rebuild Credit and
        • Balance Transfers Explained
        • Best Starter Credit Cards for Building Credit
        • What to Do If Your Credit Card is Lost or Stolen
        • How to Pay Off Credit Card Debt Fast
        • How to Pick the Best Rewards Credit Card for
        • Best Practices for Responsible Credit Card Use
        • Using a Balance Transfer Credit Card to Pay Off
        • 10 Ways to Pay Off Credit Card Debt
        • Using a HELOC to Pay Off High-Interest Credit Card
        • Credit Card Hacks
        • Beginner’s Plan to Pay Off Credit Card Debt Fast
        • Financial Advice for Single Parents
        • How to Use Credit Cards Safely to Earn Rewards
        • Secured Credit Cards and Credit-Builder Loans
        • Credit Card Basics
        • Secured vs. Unsecured Credit Cards
        • AmEx and Fanatics to Partner on New Credit Card
        • American Express Gold Card Unveils New and Updated
        • 5 Things to Know About the Robinhood Platinum Card
      • Relief & protection
        • Debt relief
        • Bankruptcy
        • Negotiating with creditors
        • Predatory lenders
        • Wage garnishment
        • Credit freeze
        • Credit protection
        • Fraud awareness
        • Truth About Credit Freezes and When to Use One
        • How to Freeze and Unfreeze Your Credit with All 3
        • How to Negotiate with Creditors
        • Credit Freeze Guide
        • How to Avoid Predatory Lenders and Spot Scams
        • Personal Loan Debt Relief Options
        • How to Freeze and Thaw Your Credit Report
        • How to Freeze and Unfreeze Your Credit
        • When Bankruptcy Might be an Option
        • Budgeting Around Wage Garnishment
        • Identity Theft Checklist
        • Monitoring vs Freezes
    • Invest & Retire
      • Invest & RetireStart small, stay boring, retire on timeIndex funds, brokerages and retirement accounts without the jargon.Explore Invest & Retire ›54 guides · 168 articles
      • Start investing
        • Investing
        • How to start investing
        • Start investing with little money
        • Start investing with $100
        • Fear of investing
        • Brokerage setup
        • Investing risk
        • Investments
        • Investment Calculator
        • Why the Price-to-Earnings Ratio Matters
        • How to Start Investing with Little Money
        • Best Apps for Beginner Investors
        • Dollar-Cost Averaging Investing Strategy
        • Investing for Beginners
        • How to Build a Diversified Investment Portfolio
        • Investing Basics for Beginners
        • I’m 25. Here’s How I Got Started Investing
        • How to Start Investing While Paying Down Debt
        • How to Start Investing and Build Your Financial
        • How to Start Investing and Build Wealth
        • How to Start Investing if You’re Scared of the
      • Strategy
        • Investing strategy
        • Investment strategies
        • Your investing portfolio
        • Diversification
        • Diversifying your investments
        • Investing mistakes
        • Investing tips
        • Investment tips
        • Best investing tips
        • Risk management
        • Understanding Custodial Accounts
        • Recession-Proof Your Portfolio
        • How to Rebalance Your Portfolio
        • When to Use Dollar-Cost Averaging vs Lump Sum
        • 5 Simple Portfolios for New Investors
        • Diversification Strategies
        • Top 11 Investments to Consider
        • Asset Allocation for the Mid-Career Investor
        • How to Understand Investment Risk and Protect Your
        • 5 Smart Diversification Strategies to Spread Your
        • Behavioral Mistakes New Investors Make
        • Set-It-And-Forget It
        • Investing Mistakes New Investors Make and How to
        • Diversification Tips for High-Income Earners with
      • Stocks
        • Stock market
        • Stock market basics
        • How to start investing in stocks
        • Stock analysis
        • Stock trading
        • Stock trading strategies
        • S&P 500
        • Options trading
        • Margin trading
        • Short selling
        • How to Make Money in Stocks
        • How to Short a Stock in 5 Easy Steps
        • Bullish vs. Bearish
        • Top 8 Investment Account Options for Children
        • How to Read Stock Charts
        • How the Stock Market Works
        • Investing 101
        • How Stock Trading Works
        • Finding the Best Stocks to Weather Inflation
        • How to Start Investing in Stocks with Little Money
        • Beginner’s Guide to Analyzing Stocks in 5 Steps
        • How to Protect Your Investments in a Stock Market
        • Identify Recession-Resistant Stocks to Outperform
        • Margin Trading Explained
      • Funds & assets
        • Index funds
        • Index funds for beginners
        • Best S&P 500 index funds
        • ETFs
        • Dividend investing
        • Bonds
        • Bond investing
        • Crypto
        • Investment types
        • The 7 Best S&P 500 Index Funds
        • Index Funds vs. Actively Managed Funds
        • Beginner’s Guide to Index Funds
        • Choosing the Best S&P 500 Index Fund for Your
        • Mutual Funds vs. ETFs
        • The Best Low-Cost ETFs for Beginners to Buy Right
        • How to Start Investing in ETFs
        • Index Funds vs. ETFs
        • 7 Best Index Funds Beyond the S&P 500
        • How to Invest in Index Funds
        • Dividend Investing for Beginners
        • How Index Funds Track the S&P 500 Index
        • How to Start Investing in S&P 500 Index Funds
        • How Bond Index Funds Provide Stability and Income
        • Common Beginner Mistakes When Investing in ETFs
      • Platforms
        • Brokerages
        • Investment platforms
        • Stock brokerage platforms
        • Robo-advisors
        • Fidelity
        • Fidelity Go Review
        • Choosing between Vanguard and Fidelity for
        • Robinhood vs. E*TRADE
        • How to Manage Multiple Brokerage Accounts
        • Opening a Brokerage Account and Its Benefits
        • Fidelity vs. Schwab
        • Manage Multiple Brokerage Accounts
        • Robo-Advisors vs. Human Advisors
        • How Brokerage Fees and Commissions Affect Your
        • Robo-Advisors vs. Traditional Brokers
        • Maximizing Returns
        • Robo-Advisors vs DIY Investing
        • How to Choose the Best Brokerage Account for
      • Retirement
        • Retirement
        • Retirement planning
        • Retirement planning basics
        • Retirement saving
        • Retirement accounts
        • Retirement income
        • 401(k)
        • IRA
        • Social Security
        • Estate planning
        • Estate basics
        • Wealth transfer
        • Roth IRA vs. Traditional IRA
        • Target-Date Funds Explained and When to Use Them
        • Tax-Advantaged Accounts
        • How to Build a Simple, Low-Stress Retirement
        • Social Security Basics
        • How to Maximize Employer 401 Match
        • How to Choose the Right ETF for Your Goals
        • Stock Investing for Major Life Goals
        • Long-Term Care for Retirement
        • 401 Basics
        • Are You Making These Retirement Mistakes?
        • Retirement Planning Essentials
    • Home & Insurance
      • Home & InsuranceBuy, borrow and insure the biggest thing you ownFrom the first down payment to the policy that protects it.Explore Home & Insurance ›39 guides · 114 articles
      • Buying
        • Home buying
        • First-time home buyer
        • Home affordability
        • Home down payment
        • Down payment strategies
        • How Much House Can I Afford?
        • Buying a Fixer-Upper House?
        • What First-Time Home Buyers Need to Know About
        • Renting vs. Buying
        • How Much Home Can You Afford?
        • How to Save for a Home Down Payment Without
        • How Much Down Payment Do You Really Need to Buy a
        • Why Every First Time Home Buyer Should Attend a
        • Is Renting Better Than Buying?
        • Unlocking Down-Payment Assistance
        • Best Down Payment Strategies for First-Time Home
        • Understanding First-Time Home Buyer Loans and
        • 9 Steps to Successfully Buy a House
        • First-Time Home Buyers Top 21 Checklist
        • Saving for a Down Payment to Buy a House
        • From Pre‑Approval to Closing a New Home
      • Mortgage
        • Mortgage
        • Mortgage basics
        • Mortgage types
        • Adjustable-rate mortgages
        • Mortgage rates
        • Mortgage application
        • Mortgage payment
        • Mortgage payoff strategies
        • Mortgage refinance
        • Mortgage tips
        • How to Calculate the Debt-to-Income Ratio for a
        • Mortgage Amortization Calculator
        • How to Refinance a Mortgage with Low Credit
        • Refinance Your Mortgage
        • Free Mortgage Calculator To Estimate Your Monthly
        • First-Time Homebuyer Checklist
        • Fixed vs. Adjustable Mortgage
        • Leveraging Credit Score Improvements Before
        • Navigating Rising Mortgage Rates
        • Refinance, Rate Locks and More
        • Credit Scores to Closing Costs
        • The Mortgage Playbook
        • Understanding ARM Mortgage Outlook Homebuyers
        • Understanding Mortgages
      • Owning
        • Home ownership
        • Owning a home
        • Home equity
        • Home improvement
        • Home renovation
        • How to Cover the Cost of Emergency Home Fixes in 8
        • Hidden Costs of Home Ownership
      • Real estate
        • Real estate
        • Real estate investing
        • Getting started in real estate
        • Rental property
        • REITs
        • Evaluating Short-Term Rental Return on Investment
        • Investing in Real Estate Owned Properties
        • Analyzing Real Estate Investment Trusts for Passive
        • Calculating Rental Property Cash Flow Accurately
        • Building a Real Estate Investment Analysis
        • Evaluating a Multi-Family Real Estate Property
        • Evaluating Real Estate Crowdfunding Platforms
        • Estimating Real Estate Property Appreciation for
        • Starting a House Hacking Strategy
        • How to Use Real Estate Wholesaling Strategy for
        • Evaluating Fix-and-Flip Real Estate Opportunities
        • Using Leverage Wisely in Real Estate
        • Structuring a Real Estate Portfolio for Tax
        • Using a 1031 Exchange to Defer Capital Gains Taxes
        • Using Real Estate Syndications to Access Larger
      • Insurance
        • Home insurance
        • Best home insurance
        • Coverage basics
        • Home insurance deductibles
        • Home insurance rates
        • Home insurance claims
        • Policy add-ons
        • Home insurance tips
        • Best home insurance companies
        • How to choose a policy
        • Compare home insurance quotes
        • Instant home insurance quotes
        • Car insurance
        • Life insurance
        • Top 6 Home Insurance Companies
        • Understanding Your Home Insurance Deductible
        • Compare Home and Insurance Quotes
        • Get Your Free Home Insurance Policy Quotes Today
        • The Ultimate Guide to Homeowners Insurance
        • How to Get the Best Home Insurance Policy Quotes
        • Home Insurance Premiums Explained
        • How to Compare Term vs. Whole Life Insurance for
        • Instant Insurance Quotes for Your Home
        • How to Estimate True Homeownership Costs
    • Taxes
      • TaxesKnow what lowers your bill before April doesDeductions, credits and the forms behind them, in the order you meet them.Explore Taxes ›25 guides · 53 articles
      • Filing
        • How to file taxes
        • Tax filing basics
        • Your tax bill
        • Tax refunds
        • Adjusted gross income
        • Adjusted Gross Income Explained
        • Tax Prep Checklist
        • Free File Tax Program Remains Woefully Underused
        • How to File a Tax Extension Online
        • Tax Refund Loan
        • Georgia State Income Tax
        • 6 Smart Ways to Cut Taxes in Retirement and Keep
        • Handling Back Taxes
      • Deductions & credits
        • Deductions
        • Tax deductions, itemized
        • Tax credits
        • Deductions vs credits
        • Saver’s credit
        • Claiming Moving Expense Deductions
        • Understanding Tax Credits vs. Deductions
        • Tax Filing for Beginners
        • How to Lower Your Tax Bill
        • Tax Deductions 101
        • Tax Credit vs. Tax Deduction
        • Earned Income Tax Credit
        • Sales Tax Deduction
        • Mortgage Interest Tax Deduction
        • Itemized Deductions
        • Popular Tax Credits Explained
        • Popular Tax Deductions and Tax Breaks
        • Qualifying for and Claiming the Saver’s Credit
      • Family
        • Child tax planning
        • Child tax credit
        • Child care credit
        • Dependent care credit
        • Maximizing the Child and Dependent Care Credit
        • The Child Tax Credit
        • Child Tax Credit Explained
        • Child and Dependent Care Credit Explained
      • Situations
        • Freelance taxes
        • Gig work taxes
        • Investment taxes
        • Capital gains taxes
        • Retirement taxes
        • HSA
        • Health savings accounts
        • How to File Taxes if You’re Freelancing
        • Capital Gains Tax Rates
        • Understanding Capital Gains Taxes
        • Contributing to HSA
        • How Side-Gig Income Affects Your Taxes
        • Saver’s Credit Explained
        • Tax Strategies for Side Hustles and Gig Working
        • What to Consider Before Moving to a State With No
        • Massachusetts State Income Tax
        • How to Use Health Savings Accounts to Lower Your
      • Planning
        • Tax planning & strategies
        • Tax strategy
        • Tax savings
        • Tax tips
        • Tax Mistakes that Trigger Audits
        • Tax-Advantaged Accounts for Education
        • Wealth Transfer
        • What to Know About Changing Your Tax Withholding
        • How to Choose the Right Tax Software for Your Tax
        • Tax Basics for New Investors
        • How Federal Tax Brackets and Rates Work
        • California State Income Tax Guide
        • Colorado State Income Tax
        • What Is a Marginal Tax Rate?
        • Illinois State Income Tax
        • Year-End Tax Checklist
    • Banking
      • Start hereBanking, without the fees you forgot you payChecking, savings and CDs, explained the way you’d tell a friend.Explore Banking ›14 guides · 215 articles
      • Basics
        • Banking basics
        • Open your first account
        • How to choose a bank
        • Compare banks
        • Bank fees
        • Best Online Bank Accounts
        • How to Open Your First Bank Account
        • Wire Transfer Fees
        • Returned Deposit Fees Explained
        • Open a Bank Account Online
        • Chase Banking
        • How to Avoid Bank Fees
        • Online Bank vs. Brick-and-Mortar
        • Online vs. Traditional Banking
        • Truist Banking Review
        • Switching Banks?
        • Chase vs. Wells Fargo vs. Capital One
        • Credit One Banking
        • Can a Bank Reopen a Closed Account?
        • How to Read Your Bank Statement Like a Pro
        • Can Someone Steal Money With Your Routing Number?
        • How to Setup a Personal Bank Account Online in 5
        • PNC Banking
        • Regions Banking
      • Checking & debit
        • Checking accounts
        • Best checking accounts
        • Debit cards
        • Best Checking Accounts with No Monthly Fees
        • Best Checking Accounts for High-Interest Earnings
        • Understanding the Time It Takes for a Check to Clear
        • Beginner’s Guide to Overdraft Protection
        • How to Mobile Deposit Checks for Beginners
        • Best Checking Accounts with Overdraft Protection
        • Maximizing Rewards
        • When to Stop a Check Payment and the Fees Involved
        • Second Chance Checking vs. Regular Accounts
        • Where to Buy Cheap and Affordable Personal Checks
        • Best Checking Accounts for Joint Accounts
        • How to Choose the Right Checking Account for Your
        • Cashing Checks at Any Bank
        • Best Checking Accounts with Excellent Mobile
        • Two Checking Accounts at One Bank
        • How Much Cash Should You Keep in Each Checking and
        • Begin Anew With Second Chance Checking in the U.S
        • Switching Checking Accounts
        • Overdraft Fees
        • Online vs. Traditional Banks
        • Missing Debit Card?
      • Savings & CDs
        • Savings accounts
        • CD Calculator
        • Understanding the Basics of Savings Account Minimum
        • Money Market Account vs. Savings Account
        • Savings Accounts vs. CDs
        • 5 Common Savings Account Fees You Should Avoid
        • High-Yield vs. Traditional Savings
        • How to Choose the Best High-Yield Savings Account
        • Learn How to Open a Savings Account in Simple Steps
        • Emergency Fund Essentials
        • Maximizing Interest
        • How to Calculate Interest Earnings in Your Savings
        • High-Yield Savings Accounts Explained
        • Determining the Right Number of Savings Accounts
        • How to Use a Money Market Account vs. a Savings
        • Savings Account Hacks for Travel Goals
        • When to Save and When to Invest
        • What is a CD and When It Makes Sense for Your
        • From CDs to Treasurys, What Happens to Yields When
        • CD and HELOC Fees
        • PNC High-Yield Savings Account Interest Rate
        • How I Chased Savings Rates at the Same Bank
        • Bread Savings CD Rates
      • Deposits & joint accounts
        • Joint bank accounts
        • Chase Joint Bank Accounts Review
        • Discover Joint Bank Accounts Review
        • How to Set Up Direct Deposit in Minutes
        • Bank of America Joint Accounts
        • Capital One Joint Bank Accounts
        • Beginner’s Guide to Early Direct Deposit with Banks
        • Wells Fargo Joint Bank Accounts
        • When to Open a Joint Bank Account
        • How to Open a Joint Bank Account Online
        • Regions Joint Account
        • TD Bank Joint Account
        • What Time Does Citizens Direct Deposit Hit?
        • What Time Does Netspend Direct Deposit Hit?
        • How to Set Up Direct Deposit With Chase
        • How to Set Up Direct Deposit on Cash App
        • How to Set Up Direct Deposit for Social Security
        • How to Set Up Direct Deposit Without an Employer
        • How Long Does Direct Deposit Take to Set Up?
        • How to Set Up Direct Deposit
        • How to Set Up Chime Direct Deposit, With or Without
        • Truist Joint Account
        • What Time Does Truist Direct Deposit Hit?
        • Wells Fargo Joint Account
      • Smarter & safer
        • Digital banking
        • Financial safety
        • Banking how-to guides
        • Banking tips
        • Best Ways for Managing Multiple Bank Accounts
        • Stay Safe from Check Scams
        • How to Set Up Bank Account Alerts and Why They
        • How Many Savings Accounts Should You Have?
        • 5 Steps to Cancel a Lost Check Quickly and Easily
        • Cashier’s Check vs. Personal Check
        • Writing a Check From a Closed Account
        • Fake Check Scams Explained
        • How Many Checking Accounts Should You Have?
        • How to Build a Relationship with Your Bank for
        • Check Washing Scams
        • Bank Bonuses Funded My Christmas Shopping This Year
        • If the CFPB Can’t Help You, Here’s How You Can Help
        • How to Secure Your Digital Banking and Finances
    • Sign In
    • Sign Up
    Amppfy
    Home » Insurance » What Does Home Insurance Cover? A Deep Dive into Protection
    Insurance

    What Does Home Insurance Cover? A Deep Dive into Protection

    Understand what does home insurance cover and protect your investment. Learn about hidden protections in your policy today.
    Thomas T.By Thomas T.March 30, 2026Updated:April 1, 202618 Mins Read
    Facebook Twitter LinkedIn Email Copy Link
    What Does Home Insurance Cover? A Deep Dive into Protection
    Share
    Facebook Twitter LinkedIn Email Copy Link
    This article contains sponsored links from Farmers Insurance. Amppfy may earn a commission if you buy through them. It never changes what we recommend.

    How to Review Your Home Insurance Policy to Avoid Costly Coverage Gaps

    Your home is probably the most expensive thing you’ll ever own. And yet, most homeowners have only a vague idea of what their insurance policy actually protects. I’ve seen people confidently assume their policy covers flood damage (it doesn’t), while having no clue they’re covered if someone slips on their icy front steps and sues them for $200,000.

    With home insurance premiums increasing by an average of 24% over the past three years, you’re paying more than ever for this protection. The average American homeowner is now spending close to $2,522 annually. In high-risk states like Florida, that number balloons dramatically. You deserve to know exactly what you’re getting for that money.

    Think of your homeowners policy as a bundle of six distinct protections, each with its own limits, rules, and blind spots. Some of those protections are obvious: your house burns down, insurance pays to rebuild it. Others are less intuitive: your kid breaks a neighbor’s window with a baseball, and your policy covers that too. Understanding each component helps you identify gaps before a disaster forces you to discover them the hard way.

    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store Get it on Google Play

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

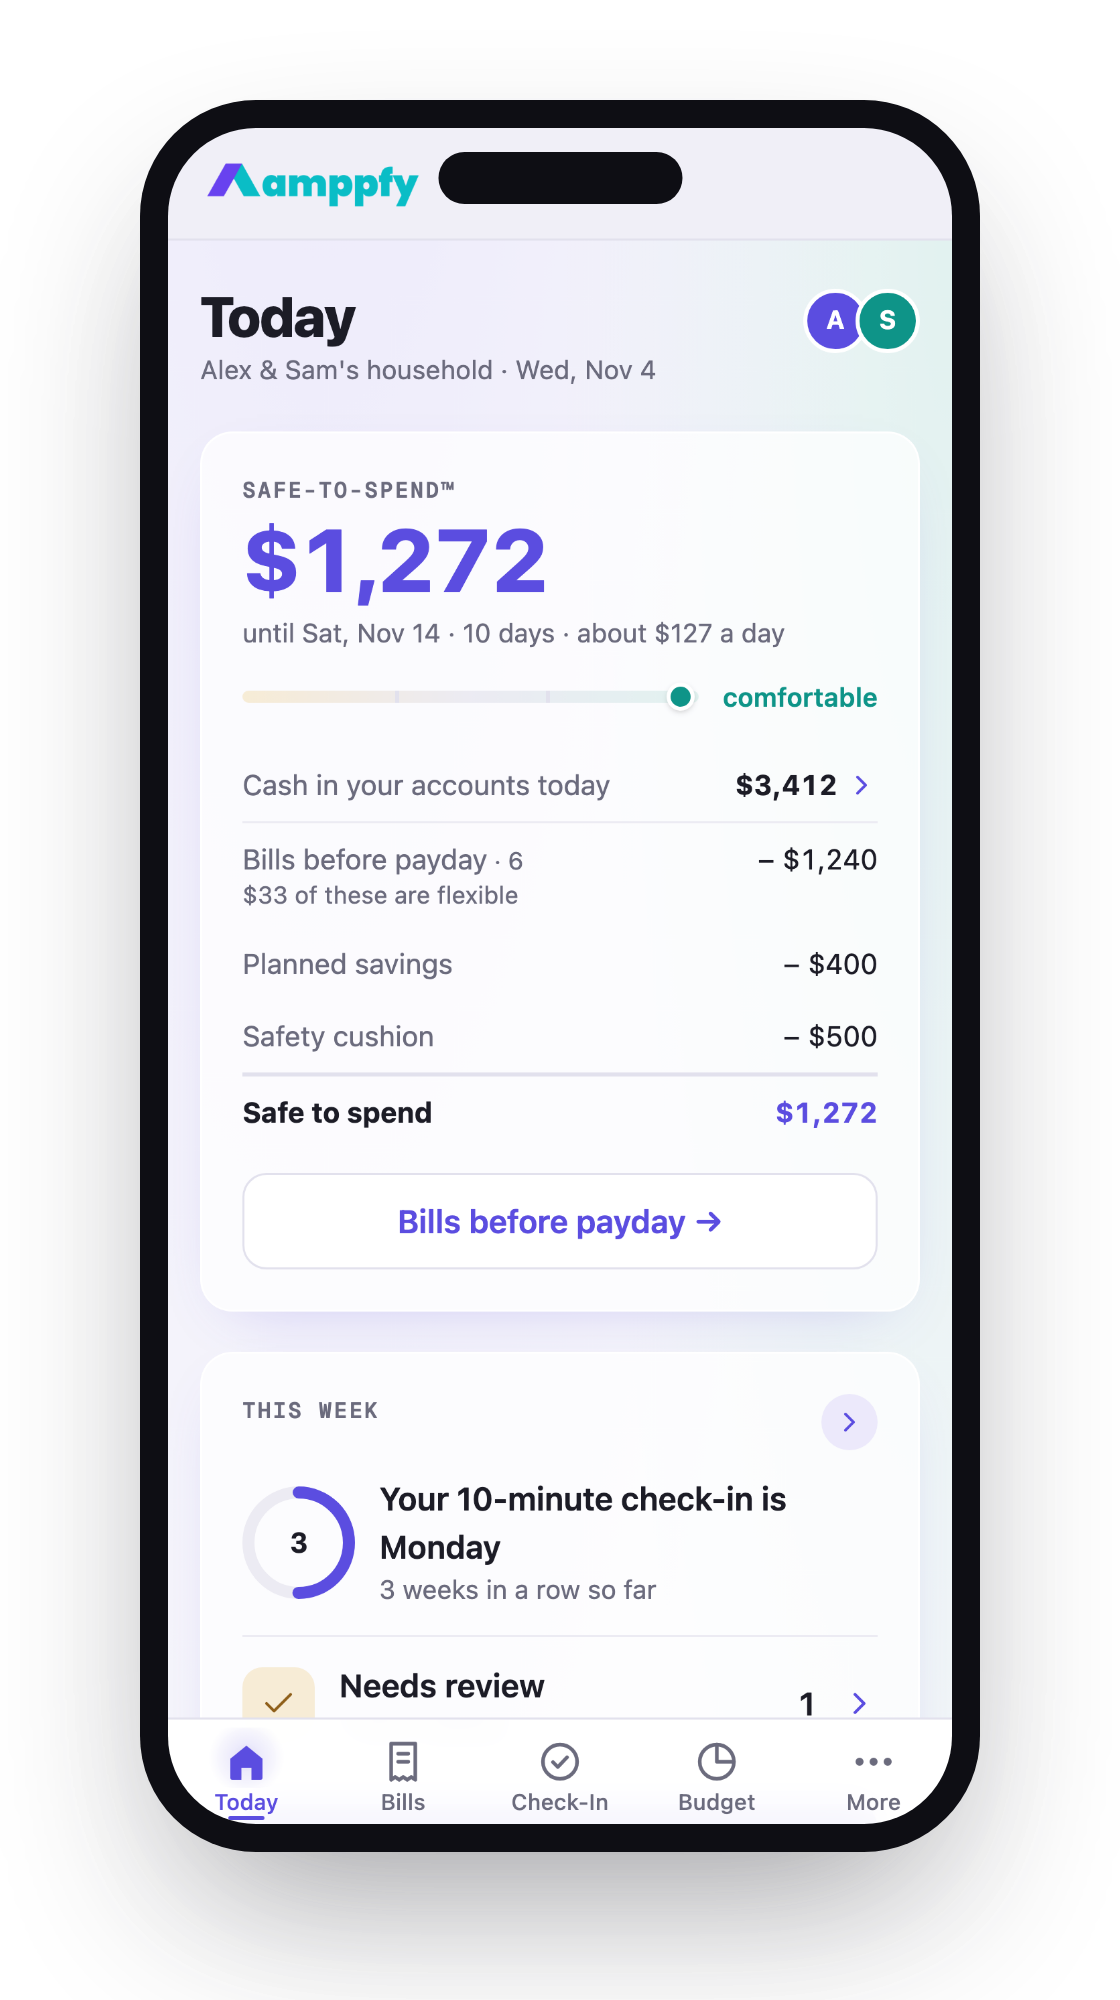
    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it

    This isn’t a topic where vague generalities help anyone. So I’m going to walk through the specific coverages, the common exclusions that catch people off guard, and the optional add-ons that might be worth your money, depending on where you live and what you own.

    The Core Components of a Standard Homeowners Policy

    A standard homeowners policy, typically called an HO-3, is structured around several distinct coverage categories. Each one protects a different part of your financial life, and each has its own dollar limit. Understanding these categories is the foundation for knowing whether you’re adequately protected or dangerously underinsured.

    The three most fundamental components cover the physical stuff: your house, your other structures, and your personal belongings. They work together, but they’re calculated separately, and the limits interact in ways that matter.

    » Understand your home insurance coverage with confidence: Understanding Your Home Insurance Policy Coverage Exclusions Guide

    Dwelling Coverage for the Physical Structure

    Dwelling coverage, listed as Coverage A on your policy, pays to repair or rebuild your home’s physical structure if it’s damaged by a covered peril. This includes the walls, roof, floors, built-in appliances, attached garage, and permanently installed fixtures, such as plumbing and electrical systems.

    Here’s where people get tripped up: dwelling coverage should reflect the cost to rebuild your home, not its market value. Your house might sell for $350,000, but rebuilding it from scratch could cost $280,000 or $420,000, depending on local construction costs and materials. If you insure for market value and rebuilding costs more, you’re stuck paying the difference out of pocket.

    Most policies include an inflation guard clause that automatically adjusts your dwelling coverage by a small percentage each year. But with construction costs surging in many areas, that automatic adjustment may not keep pace. I’d recommend reviewing your dwelling limit every two to three years and getting an updated rebuild estimate, especially if you’ve done major renovations.

    » Protect your home and finances with confidence: Ultimate Guide To Homeowners Insurance Everything You Need To Know Guide

    Other Structures Protection for Detached Buildings

    Coverage B protects structures on your property that aren’t attached to your main house. Think detached garages, garden sheds, fences, gazebos, and in-ground swimming pools. Even your driveway and walkways fall under this category.

    This coverage is typically set at 10% of your dwelling coverage. So if your home is insured for $300,000, you’d have $30,000 for other structures. For most homeowners, that’s plenty. But if you have a detached workshop, a guest house, or an expensive pool setup, you might need to increase this limit.

    One important restriction: structures used for business purposes often aren’t covered under a standard policy. If you rent out a detached garage as studio space or run a business from a backyard building, you’ll likely need a separate commercial policy or endorsement.

    » Understand the key differences in insurance coverage: Renters Vs Homeowners Insurance Whats The Difference Guide

    Personal Property and Belongings Coverage

    Coverage C covers your stuff: furniture, clothing, electronics, kitchen appliances, sporting equipment, and everything else you own inside (and sometimes outside) your home. Standard policies set this at 50% to 70% of your dwelling coverage amount.

    Here’s a critical distinction most people miss: standard policies cover personal property on an actual cash value basis, meaning they factor in depreciation. That five-year-old laptop you paid $1,200 for might only get you $300. If you want full replacement cost coverage, where the insurer pays what it costs to buy a new equivalent item, you usually need to upgrade your policy or add an endorsement.

    Certain categories of belongings have sub-limits that cap payouts regardless of your total personal property coverage:

    • Jewelry and watches: typically limited to $1,500 to $2,500
    • Cash and securities: often capped at $200 to $500
    • Firearms: usually limited to $2,500
    • Silverware and goldware: commonly capped at $2,500
    • Business equipment at home: often limited to $2,500

    If you own items exceeding these sub-limits, you’ll need scheduled personal property coverage, which I’ll discuss later.

    » Protect your home and finances with confidence: Ultimate Guide To Homeowners Insurance Everything You Need To Know Guide

    Liability and Loss of Use Protections

    The financial protections in your homeowners policy extend well beyond physical damage to your property. Two often-overlooked components, liability coverage and loss of use coverage, can be the most valuable parts of your entire policy. A single lawsuit or an extended period away from home can cost tens of thousands of dollars, and these coverages are specifically designed for those scenarios.

    Personal Liability for Legal and Medical Expenses

    Coverage E, your personal liability protection, kicks in when you’re legally responsible for someone else’s bodily injury or property damage. The standard amount is $100,000, though many financial advisors recommend carrying at least $300,000 to $500,000.

    The scenarios this covers are broader than most people realize. A delivery driver trips on your broken front step and fractures a wrist. Your dog bites a neighbor’s child at a barbecue. Your tree falls onto a neighbor’s car during a storm. In each case, your liability coverage pays for their medical bills, legal defense costs, and any settlement or judgment against you, up to your policy limit.

    Your policy also includes Coverage F, medical payments to others, which is a smaller amount (usually $1,000 to $5,000) that pays for minor injuries on your property regardless of fault. This is designed to handle small claims quickly and prevent them from becoming lawsuits. If a guest stumbles on your stairs and needs an X-ray, medical payments coverage covers the cost without anyone having to file a liability claim.

    For homeowners with significant assets, a standard liability limit may not be enough. An umbrella policy, which sits on top of your homeowners and auto liability coverage, can extend your protection to $1 million or more for a relatively modest annual premium, often $200 to $400 per year.

    » Get the best home insurance quotes with ease: Get Your Free Home Insurance Policy Quotes Today Guide

    Additional Living Expenses During Home Repairs

    Coverage D, also called loss-of-use coverage, pays for the increased cost of living when your home is uninhabitable due to a covered loss. If a fire destroys your kitchen and you need to live in a hotel and eat at restaurants for three months while repairs are completed, this coverage reimburses those extra expenses.

    The keyword here is “increased.” Your policy doesn’t pay your entire hotel bill and every restaurant meal. It pays the difference between your normal living expenses and what you’re spending while displaced. If you normally spend $400 a month on groceries but you’re now spending $1,200 eating out because you have no kitchen, Coverage D reimburses the $800 difference.

    Most policies set this coverage at 20% of your dwelling amount. On a $300,000 policy, that gives you $60,000 for additional living expenses. For short-term displacements, that’s usually more than enough. But if your home suffers catastrophic damage requiring a year or more of reconstruction, you could burn through that limit. Homeowners in disaster-prone areas should pay close attention to this number.

    Common Perils Covered by Standard Policies

    An HO-3 policy covers your dwelling on an “open perils” basis, meaning everything is covered unless it’s specifically excluded. Your personal property, however, is typically covered on a “named perils” basis, meaning only listed dangers are covered. Understanding the most common perils gives you a practical sense of what your policy handles day to day.

    Weather-Related Damage: Fire, Wind, and Hail

    Weather events drive the majority of homeowners’ insurance claims. Wind and hail alone account for 40.7% of all home insurance claims submitted nationwide, making them the largest category of covered losses.

    Fire and lightning, while less frequent, tend to be far more devastating per incident. The average claim for fire and lightning exceeds $88,000, reflecting the reality that fires often cause total or near-total losses. A kitchen fire that spreads can destroy not just the structure but virtually everything inside it.

    Your standard policy covers damage from fire, lightning, windstorms, hail, explosions, and the weight of ice and snow. If a hailstorm shreds your roof or a lightning strike sparks a house fire, you’re covered. However, some policies in hurricane-prone and tornado-prone states apply separate, higher deductibles for wind damage, sometimes 2% to 5% of the dwelling coverage rather than a flat dollar amount.

    Crime and Vandalism Protection

    Standard policies cover theft of personal property, both inside and outside your home, as well as vandalism and malicious mischief. If someone breaks into your house and steals your electronics, your personal property coverage pays for the loss (minus your deductible and subject to any sub-limits).

    Theft coverage even extends to belongings stolen away from home. If your luggage is stolen from a hotel room during a vacation, your homeowners’ policy can cover it, typically up to 10% of your personal property limit. Vandalism is covered too: if someone spray-paints your siding or smashes your windows, your policy pays for repairs.

    One caveat: if your home has been vacant for more than 30 to 60 days (the exact timeframe varies by insurer), vandalism and theft coverage may be suspended. This matters for snowbirds, landlords between tenants, or anyone with a second home that sits empty for extended periods.

    Critical Exclusions Every Homeowner Should Know

    What your policy doesn’t cover can hurt you more than what it does. The exclusions in a standard homeowners policy are specific, and some of them are genuinely surprising to people who’ve never read their policy documents.

    Natural Disasters: Floods and Earthquakes

    This is the big one. Standard homeowners’ policies do not cover flood damage or earthquake damage. Period. These are separate policies that require separate premiums.

    Flood insurance is available through the National Flood Insurance Program (NFIP) or private insurers. NFIP policies max out at $250,000 for dwelling coverage and $100,000 for personal property. If you live in a FEMA-designated flood zone and have a federally backed mortgage, flood insurance is mandatory. But even homeowners outside designated flood zones should consider it: roughly 25% of all flood claims come from properties in low- to moderate-risk areas.

    Home insuranceSponsored
    Farmers Insurance
    Switch & save on home
    $778 average savings could be yours.*
    Get a quote
    Quotes by Farmers Insurance. Amppfy may earn a commission. *Based on average nationwide annual savings of new customers surveyed, excluding HI, SC & Farmers GroupSelect®, from 9/1/24 to 8/31/25 who switched their Home insurance policy to a Farmers® branded policy, responded to the survey, and realized savings. Potential savings vary by customer and may vary by state and product. Coverage and prices vary by state.

    Earthquake insurance is available as a standalone policy or as an endorsement, primarily through state-run programs such as the California Earthquake Authority. Earthquake policies typically carry high deductibles, often 10% to 20% of the dwelling coverage, making them useful mainly for catastrophic damage rather than minor cracks.

    PerilCovered by Standard Policy?Alternative Coverage
    Fire/LightningYesN/A
    Wind/HailYes (may have separate deductible)N/A
    FloodNoNFIP or private flood policy
    EarthquakeNoStandalone earthquake policy
    Sewer BackupNoOptional endorsement
    MoldLimitedMold endorsement

    Maintenance Issues and Normal Wear and Tear

    Insurance is designed to cover sudden, accidental events, not gradual deterioration. If your roof leaks because it’s 25 years old and the shingles are worn out, that’s a maintenance issue, not an insurable event. Your claim will be denied.

    This distinction matters in practice more than people expect. A pipe that bursts suddenly during a freeze is covered. A pipe that’s been slowly leaking behind your wall for months, causing mold and rot, is typically not covered because the damage resulted from neglect rather than a sudden event. Some policies cover the resulting water damage but not the cost of repairing the pipe itself.

    Other common exclusions include damage from termites and other pests, settling or cracking foundations, and damage from government action. Understanding these boundaries helps you prioritize home maintenance as a financial strategy rather than just a chore.

    Optional Endorsements for Enhanced Security

    Your base policy is a starting point. Depending on your specific situation, optional endorsements (also called riders or floaters) can fill gaps that would otherwise leave you exposed. These add-ons typically cost a fraction of your base premium but can save you thousands when you need them.

    Scheduled Personal Property for High-Value Items

    Remember those sub-limits I mentioned earlier? If you own a $10,000 engagement ring, a $5,000 guitar collection, or fine art worth $15,000, your standard policy’s sub-limits won’t come close to covering a loss. Scheduled personal property coverage solves this problem.

    With a scheduled endorsement, you list specific high-value items along with their appraised values. The insurer then covers each item for its full appraised amount, often with no deductible and broader coverage than your base policy provides. A scheduled jewelry floater, for example, typically covers accidental loss (you drop your ring down a drain) in addition to theft, which your base policy might not.

    The cost is reasonable: expect to pay roughly $1 to $2 per $100 of coverage annually for jewelry, and similar rates for other categories. For a $10,000 ring, that’s about $100 to $200 per year for complete protection. You’ll need a professional appraisal for each item, which should be updated every few years to reflect current values.

    Sewer Backup and Sump Pump Overflow Riders

    Sewer backup is one of the most common and most disgusting homeowner disasters, and your standard policy doesn’t cover it. When a municipal sewer line backs up into your basement or your sump pump fails during heavy rain, the resulting damage can easily reach $10,000 to $20,000 between cleanup, decontamination, and replacing destroyed belongings.

    A sewer backup endorsement typically costs $40 to $100 per year and provides $5,000 to $25,000 in coverage. If you have a finished basement, this endorsement is practically essential. The cost-benefit math is overwhelmingly in your favor.

    Other endorsements worth considering include water backup coverage, identity theft protection, home business coverage, and equipment breakdown coverage for major systems like HVAC units. Your agent can help you evaluate which add-ons make sense based on your home’s age, location, and your personal risk profile.

    Determining the Right Amount of Coverage

    Getting the right coverage amount is a balancing act. Underinsure, and you’re exposed to financial catastrophe. Overinsure, and you’re wasting money on premiums for protection you’ll never collect on. Here’s how to think about it practically.

    Start with Your Dwelling Coverage

    Get a professional replacement cost estimate, not a Zillow market value. Factor in local construction costs, your home’s square footage, building materials, and any custom features.

    Then make sure your personal property coverage reflects what you actually own: a detailed home inventory, even a simple spreadsheet with photos, makes this process straightforward and speeds up claims if disaster strikes.

    Liability and Net Worth

    For liability, consider your total net worth and future earning potential. If someone wins a judgment against you that exceeds your coverage, they can go after your savings, investments, and even future wages. A $300,000 to $500,000 liability limit with a $1 million umbrella policy costs surprisingly little and protects against worst-case scenarios.

    Review Your Policy Annually

    Especially after major life changes: renovations, expensive purchases, a new trampoline or swimming pool, or a shift in local building costs. Homeowners in states with rapidly rising premiums, like Florida, where the average annual premium hits $5,688 for a $300,000 dwelling, should shop around every year or two to ensure they’re not overpaying.

    The friction of reviewing your policy once a year is minimal. The financial pain of discovering a coverage gap after a disaster is enormous. Set a calendar reminder, pull out your declarations page, and spend 30 minutes making sure your protection matches your reality.

    Frequently Asked Questions

    Does home insurance cover damage from a burst pipe?

    Yes, if the pipe bursts unexpectedly, your standard policy covers both the resulting water damage and cleanup costs. However, the policy typically does not cover repairs or replacement of the pipe itself, and if the damage resulted from long-term neglect or failure to maintain your plumbing, the claim may be denied entirely. Sudden versus gradual is the key distinction insurers use.

    How much personal property coverage do I actually need?

    Most people underestimate the total value of their belongings. Walk through every room and mentally add up the cost of replacing everything: furniture, clothing, electronics, kitchenware, books, decorations. The average household owns $50,000 to $100,000 worth of personal property. Creating a home inventory with photos and estimated values is the best way to determine your actual number.

    Will my premiums go up if I file a claim?

    In most cases, yes. Filing a single claim can increase your premiums by 7% to 25% at renewal, and the surcharge can last three to five years. This is why many financial advisors recommend covering small losses out of pocket and reserving insurance claims for significant damage. A $1,500 claim might save you money now, but cost you more in premium increases over the following years.

    Is home office equipment covered under my homeowners’ policy?

    Standard policies provide limited coverage for business equipment, usually capped at $2,500. If you work from home and have expensive computer equipment, monitors, or specialized tools, this limit probably isn’t enough. A home business endorsement or a separate business owner’s policy can extend your coverage to match the actual value of your work setup.

    Does home insurance cover damage from a burst pipe?

    Yes, if the pipe bursts unexpectedly, your standard policy covers both the resulting water damage and cleanup costs. However, the policy typically does not cover repairs or replacement of the pipe itself, and if the damage resulted from long-term neglect or failure to maintain your plumbing, the claim may be denied entirely. Sudden versus gradual is the key distinction insurers use.

    How much personal property coverage do I actually need?

    Most people underestimate the total value of their belongings. Walk through every room and mentally add up the cost of replacing everything: furniture, clothing, electronics, kitchenware, books, decorations. The average household owns $50,000 to $100,000 worth of personal property. Creating a home inventory with photos and estimated values is the best way to determine your actual number.

    Will my premiums go up if I file a claim?

    In most cases, yes. Filing a single claim can increase your premiums by 7% to 25% at renewal, and the surcharge can last three to five years. This is why many financial advisors recommend covering small losses out of pocket and reserving insurance claims for significant damage. A $1,500 claim might save you money now, but cost you more in premium increases over the following years.

    Is home office equipment covered under my homeowners’ policy?

    Standard policies provide limited coverage for business equipment, usually capped at $2,500. If you work from home and have expensive computer equipment, monitors, or specialized tools, this limit probably isn’t enough. A home business endorsement or a separate business owner’s policy can extend your coverage to match the actual value of your work setup.
    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store Get it on Google Play

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it
    Best Home Insurance Home Buying home insurance Home insurance tips Home Ownership
    Share. Facebook Twitter LinkedIn Email Copy Link
    Previous ArticleHow to Get the Best Home Insurance Rates in 2026
    Next Article Home Insurance Claims Guide: Step-by-Step Strategies to File Faster and Maximize Your Payout
    Thomas T.

    Thomas is a Personal Finance Writer and Financial Content Strategist with over 10 years of experience helping individuals make smarter financial decisions. He specializes in topics such as budgeting, debt management, saving strategies, and financial behavior, translating complex financial concepts into clear, actionable guidance. His work focuses on empowering readers to build sustainable financial habits and confidently navigate their financial lives, combining data-driven insights with practical, real-world advice.

    More Like This

    Insurance in a Household Budget: Health, Auto, Home, and Life

    By Thomas T.October 6, 2026

    A Home Repair Fund: How Much Owners and Renters Should Set Aside

    By Thomas T.October 2, 2026

    Property Tax, HOA, and Home Insurance: Planning the Big Bills Homeowners Forget

    By Thomas T.October 2, 2026
    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number.

    Download on the App Store Get it on Google Play

    Prefer the web? Sign up free ›

    Amppfy dashboard on an iPhone showing the Safe to Spend number with the math under it
    Helpful Resources

    Insurance in a Household Budget: Health, Auto, Home, and Life

    October 6, 2026

    A Home Repair Fund: How Much Owners and Renters Should Set Aside

    October 2, 2026

    Property Tax, HOA, and Home Insurance: Planning the Big Bills Homeowners Forget

    October 2, 2026

    Annual Bills on a Payday Calendar: Insurance, Registration, and the Rest

    October 1, 2026

    Financial Clarity. Everyday Confidence.

    Facebook X (Twitter) YouTube TikTok
    Calculators

    Emergency Fund Calculator

    Compound Interest Calculator

    Interest Rate Calculator

    Net Worth Calculator

    Mortgage Calculator

    How Much Home Can I Afford

    Debt-to-Income Ratio Calculator

    Cost of Living Calculator

    Savings Calculator

    Savings Goal Calculator

    Monthly Budget Calculator

    Latest Resources

    Social Security COLA 2027: What the 3.6% Raise Means for Your Monthly Plan

    November 6, 2026

    Best Free Budget Apps in 2026: iPhone, Android, and Web

    November 6, 2026

    Federal Pay Period Calendar for 2027: Every Pay Period and Payday

    November 6, 2026

    Money Manager Expense & Budget App: Price, Ads, and Simpler Alternatives in 2026

    November 6, 2026
    About & Legal

    About Amppfy

    Documentation

    Advertise with Amppfy

    Editorial Policy

    EULA

    Terms of Use

    Acceptable Use Policy

    Privacy Policy

    Cookie Policy

    Disclaimer

    Do Not Sell or Share My Personal Information

    Acceptable Use Policy

    Disclaimer: Amppfy is committed to keeping its information transparent, accurate, and up-to-date. The information on Amppfy is provided for educational and informational purposes only and should NOT be considered financial, investment, tax, or legal advice. You should consult a qualified financial professional before making any financial decisions. This information may differ from what you find on the specific product or service provider’s website. All information, content, software, tools, products, or services on Amppfy are presented without warranty or guarantee. Please review the specific provider’s terms and conditions when evaluating products or services. By accessing Amppfy or using our AI generator tools, you acknowledge that you have read, understood, and agreed to our EULA, Terms of Use, Acceptable Use Policy, Privacy Policy, Cookie Policy, and Disclaimer. Amppfy.com uses cookies. For more information, visit Amppfy’s Cookie Policy. Amppfy may be compensated through third-party advertisers and affiliates. For more information, visit Amppfy’s Disclaimer.

    Copyright© 2026 Amppfy | All Rights Reserved

    Type above and press Enter to search. Press Esc to cancel.

    Advertiser Disclosure: Products may include affiliate links related to financial products or services. We may earn a commission at no additional cost to you. Our content remains independent and focused on helping you make informed financial decisions.
    Fact Checked
    Financial Disclaimer

    This content is for informational and educational purposes only and should not be considered financial advice. Personal finance decisions—including budgeting, saving, investing, credit, mortgages, taxes, and debt management—depend on your individual circumstances. Always consult a qualified financial professional before making financial decisions.

    Editorial Standards and Content Integrity

    Our editorial process ensures accuracy, clarity, and trust across all personal finance topics, including budgeting, saving, investing, and debt management. Content is created using credible sources such as government agencies, academic research, and established financial institutions, and may incorporate insights from industry experts when relevant. Each article is reviewed for accuracy, timeliness, and relevance before publication and updated as needed to reflect changes in financial guidelines and best practices, with the goal of providing clear, evidence-based information to help readers make informed financial decisions.

    Learn more about our editorial policy and guideline.
    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Get the app on iPhone or Android and enter your balances, bills, and payday. About ten minutes to one clear number: what’s safe to spend before payday.Your balances, bills, and payday. Ten minutes to one clear number. Learn more ›

    Download on the App Store Get it on Google Play
    Scan with your phone to get the app

    Free  ·  No credit card  ·  Just your balances

    Prefer the web? Sign up free ›

    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Enter your balances, bills, and payday once. About ten minutes to one clear number, with the math shown under it.

    Download on the App Store Get it on Google Play
    Scan with your phone to get the app

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances