Close Menu

    Subscribe to Updates

    Get the latest creative news from FooBar about art, design and business.

    What's Hot

    How to Open a Joint Bank Account Online (Without a Branch Visit)

    October 19, 2026

    Regions Joint Account: Opening One Together or Adding a Partner

    October 19, 2026

    TD Bank Joint Account: How to Open One or Add a Partner

    October 19, 2026
    Facebook X (Twitter) Instagram
    Amppfy
    • Safe to Spend™ App
      • Amppfy on iPhone — one clear number with the status scale and the math under itYour number, in your pocketFree on iPhone, with the same account on the web.
        • Download on the App Store
        • Prefer the web? Sign up free ›
      • The app
        • OverviewOne clear number for what’s safe to spend before payday
        • Safe-to-Spend™The four-line math, always shown
        • Weekly check-inTen minutes a week keeps it honest
      • Features
        • Bills & paydaysEvery bill and payday on one calendar
        • GoalsSavings that fund themselves first
        • For couplesTwo logins, one number you both trust
        • SubscriptionsWhat you pay monthly, and what cancelling gives back
        • Calendar & heads-upsYour month at a glance, a heads-up before bills land
        • Net worth & payday nudgeThe whole picture, month by month
        • BudgetWhere the month’s money goes, month by month
      • Trust & help
        • Security & privacyJust your balances, optional two-step verification
        • Help centerSetup, the number, check-ins, FAQ
        • Open the web appSame account, any browser
    • Personal Finance
      • Money Basics
        • How to Master Money Management
        • Psychology of Money Habits
        • How to Set Financial Goals
        • Money Management for Every Life Stage
        • Beyond Budgeting: Advanced Money Skills
        • Financial Literacy
        • Money Management
        • Know Your Money
        • Cash Flow
      • Financial Wellness
        • Understand Your Money Relationship
        • Build a Healthy Money Mindset
        • 7 Money Tips for Financial Freedom
        • Take the Money Health Quiz
        • Monthly Financial Reviews
        • Money Habits
        • Money Mindset
        • Financial Goals
        • Financial Independence
      • Side Hustles & Extra Income
        • 8 Realistic Side Hustles
        • How to Make Money Online
        • Passive Income Ideas That Work
        • Passive Income 101: Ideas That Scale
        • Spot a Bad Passive Income Deal
        • Start Freelance Writing: First $1,000
        • Budgeting with Irregular Income
        • Side Hustle Ideas
        • Passive Income
        • Gig Economy
      • Major Money Decisions
        • Plan a Major Purchase Without Debt
        • Car Buying: Save, Finance, or Lease?
        • Used Car Buying & Negotiation Tips
        • What to Save For vs. Finance
        • Life Insurance 101: Coverage Needs
        • Term vs. Whole Life Insurance
        • Buying a Car
        • Major Purchase Planning
        • Home Improvement
        • Life Insurance
      • Money Tools & Calculators
        • Net Worth Calculator
        • Cost of Living Calculator
        • Compound Interest Calculator
        • Monthly Budget Calculator
        • Savings Goal Calculator
        • Emergency Fund Calculator
        • Savings Calculator
        • Do Money Management Tools Work?
        • Spend Tracking
        • Net Worth
    • Savings
      • Budgeting Tips
        • The 50/30/20 Rule Explained
        • How to Make a Monthly Budget
        • How to Budget Money in 5 Steps
        • The Envelope Method Explained
        • Best Budgeting Apps Compared
        • Common Budgeting Mistakes
        • Budgeting for Couples
        • Start a Budget
        • Budget Methods
        • 50/30/20 Budgeting
      • Ways to Save
        • Save $500 This Month
        • 14 Ways to Cut Monthly Expenses
        • How to Save Money on Groceries
        • Lower Your Utility Bills
        • Budget Swaps for Big Purchases
        • Save Money on Car Insurance
        • Cut Expenses
        • Groceries Savings
        • Smart Saving Strategies
      • Emergency Fund
        • How Much Emergency Fund to Save
        • How to Build an Emergency Fund
        • Start a Rainy Day Fund
        • Sinking Funds vs. Emergency Fund
        • Emergency Fund Essentials
        • Where to Keep Your Emergency Fund
        • Best Emergency Fund Tips
        • Emergency Savings
        • Emergency Buffer
      • Savings Goals & Plans
        • How to Create a Savings Plan
        • How to Set Savings Goals
        • Track Spending Without Spreadsheets
        • 529 College Savings on a Budget
        • Saving During a Recession
        • Budget a Debt-Free Vacation
        • Vacation Budgeting
        • Family Budgeting
        • Savings Goals
        • Recession Saving
      • Savings Tools & Planning
        • Budget Calculator
        • Savings Goal Calculator
        • Emergency Fund Calculator
        • Savings Calculator
        • Compound Interest Calculator
        • Savings Buckets
        • Sinking Funds
        • Maximize Your Savings
        • Savings Tips
        • Savvy Saver
    • Debt
      • Get Out of Debt
        • Debt Snowball vs. Avalanche
        • Pay Off Credit Card Debt Fast
        • Beginner’s Credit Card Payoff Plan
        • Build a Debt Payoff Calendar
        • Use Windfalls to Crush Debt
        • Debt Free Journey
        • Debt Payoff
        • Credit Card Debt
      • Student & Auto Loans
        • Student Loans 101
        • Get Out of Student Loan Debt
        • Income-Driven Repayment Plans
        • Best Student Loan Repayment Option
        • Auto Loans: Shop & Save on Interest
        • Pay Off Your Auto Loan Early
        • Student Loans
        • Auto Loans
        • Auto Loan Debt
      • Debt Consolidation
        • Debt Consolidation Pros & Cons
        • Is Consolidating Debt Right for You?
        • Balance Transfers to Pay Off Debt
        • HELOC to Pay Off Credit Cards
        • 401(k) Rollover to Pay Down Debt
        • How to Refinance a Personal Loan
        • Before You Take a Personal Loan
        • Personal Loans
        • Personal Loan Refinance
      • Managing Debt
        • Navigating Medical Debt
        • Budgeting with a High-Interest Loan
        • Build a Debt-Repayment Fund
        • Debt Payoff for Single Parents
        • Save for a Wedding Without Debt
        • Medical Debt
        • Single Parent Debt
        • Personal Loan Debt
      • Debt Relief & Protection
        • When Bankruptcy Is an Option
        • Avoid Predatory Lenders & Scams
        • Negotiate with Creditors: Scripts
        • Budgeting Around Wage Garnishment
        • Debt Relief
        • Bankruptcy
        • Creditor Negotiation
        • Predatory Lenders
        • Wage Garnishment
    • Credit
      • Credit Scores
        • Credit Score 101
        • Check & Improve Your Credit Score
        • Credit Utilization: A Simple Fix
        • Check Your Credit Score Free
        • Rebuild Credit After a Setback
        • How Credit Scores Are Calculated
        • What Credit Scores Mean
        • Credit Health
      • Credit Reports
        • Read & Dispute Your Credit Report
        • Dispute Template That Works
        • How Long Negative Marks Last
        • Remove Negative Items
        • What to Expect as Items Age Off
        • Understanding Credit Utilization
        • Credit Basics
        • Checking Your Credit Score
      • Building Credit
        • Best Starter Credit Cards
        • Secured vs. Unsecured Cards
        • Secured Cards & Credit-Builder Loans
        • Build Credit as a Gig Worker
        • Boost Your Score Before a Mortgage
        • Borrow Now vs. Wait
        • Build Credit
        • Credit Cards for Beginners
        • Credit for Gig Workers
      • Credit Cards
        • Best Rewards Credit Cards
        • Credit Card Hacks: Intro APRs
        • Balance Transfers Explained
        • Earn Rewards Without Debt
        • Responsible Card Use & Rewards Tips
        • Lost or Stolen Card: What to Do
        • Credit Card Rewards
        • Balance Transfer Cards
      • Credit Protection & Safety
        • Identity Theft Checklist
        • Truth About Credit Freezes
        • How to Freeze & Thaw Your Credit
        • Credit Monitoring vs. Freezes
        • Credit Protection
        • Credit Freeze
        • Fraud Awareness
        • Financial Safety
    • Investing
      • Start Investing
        • Investing 101: Beginner’s Guide
        • Start Investing with $100
        • Start with $50/Month
        • Scared of the Market? Start Here
        • Open a Brokerage Account
        • Invest While Paying Down Debt
        • How to Start Investing
        • Start with Little Money
        • Fear of Investing
      • Investing Strategy
        • Roth IRA vs. Traditional IRA
        • Dollar-Cost Averaging Explained
        • DCA vs. Lump-Sum Investing
        • 5 Simple Starter Portfolios
        • Asset Allocation Beyond 60/40
        • How to Rebalance Your Portfolio
        • Diversify Your Portfolio
        • Investing Mistakes to Avoid
        • Investment Strategies
        • Diversification
      • Stocks
        • How the Stock Market Works
        • How to Make Money in Stocks
        • How to Read Stock Charts
        • Analyze Stocks in 5 Steps
        • P/E Ratio for Beginners
        • Bullish vs. Bearish Explained
        • How Stock Trading Works
        • Stock Market Basics
        • Stock Analysis
        • Stock Trading Strategies
      • Funds & Wealth Building
        • Beginner’s Guide to Index Funds
        • Best S&P 500 Index Funds
        • Mutual Funds vs. ETFs
        • How to Invest in ETFs
        • Dividend Investing for Beginners
        • Build a Dividend Income Stream
        • Maximize Your 401(k) Match
        • Build a Retirement Portfolio
        • Index Funds
        • Dividend Investing
      • Brokerages & Platforms
        • Vanguard vs. Fidelity
        • Fidelity vs. Schwab
        • Robinhood vs. E*Trade
        • Robo-Advisors vs. Human Advisors
        • Robo-Advisor or DIY Investing?
        • How Brokerage Fees Affect Returns
        • Manage Multiple Brokerage Accounts
        • Brokerages
        • Investment Platforms
        • Robo Advisors
    • Home
      • Home Buying
        • First-Time Homebuyer Checklist
        • How Much Down Payment You Need
        • How Much Home Can You Afford?
        • Renting vs. Buying
        • True Costs of Homeownership
        • Qualify as a First-Time Buyer
        • Buying a Fixer-Upper
        • First-Time Home Buyer
        • Home Affordability
      • Mortgage
        • First-Time Buyer’s Mortgage Guide
        • Fixed vs. Adjustable Mortgage
        • How to Refinance a Mortgage
        • Mortgage Payoff Strategies
        • Winning in a High-Rate Market
        • Mortgage Amortization Calculator
        • Down Payment Assistance Programs
        • Mastering Refinance Rate Locks
        • Mortgage Rates
        • Mortgage Refinance
        • Debt-to-Income Calculator
      • Real Estate Investing
        • Real Estate Crowdfunding Platforms
        • Rental Property Cash Flow
        • REITs for Passive Income
        • REITs vs. Direct Ownership
        • Fix-and-Flip Opportunities
        • Airbnb & Short-Term Rental ROI
        • Buying a Multi-Family Property
        • 1031 Exchange to Defer Taxes
        • Real Estate Investing
        • Rental Property
      • Home Insurance
        • Homeowners Insurance Guide
        • Compare Home Insurance Quotes
        • Best Home Insurance Companies
        • Choose Your Deductible
        • Renters vs. Homeowners Insurance
        • File a Property Insurance Claim
        • Home Insurance Coverage Basics
        • Home Insurance Rates
        • Home Insurance Claims
      • Home Equity & Ownership
        • Smart Ways to Use Home Equity
        • Save for a Down Payment
        • Down Payment Strategies
        • Estimate Property Appreciation
        • Home Equity
        • HELOC Payoff Strategy
        • Home Down Payment
        • Home Ownership
        • Home Renovation
    • Bank
      • Banking Basics
        • Open Your First Bank Account
        • Online Banks vs. Traditional Banks
        • How to Avoid Bank Fees
        • How to Switch Banks
        • Read Your Bank Statement
        • Second-Chance Checking Accounts
        • Get Better Rates from Your Bank
        • Banking Basics
        • How to Choose a Bank
        • Compare Banks
      • Checking Accounts
        • Best Checking Accounts
        • Choose the Right Checking Account
        • Overdraft Protection Guide
        • Stop Paying Overdraft Fees
        • The True Cost of Checking Fees
        • Mobile Check Deposits
        • How Long Checks Take to Clear
        • Checking Accounts
        • Best Checking Account
      • Savings Accounts & CDs
        • High-Yield Savings Explained
        • Best High-Yield Savings Account
        • Savings Accounts vs. CDs
        • What Is a CD?
        • Money Market vs. Savings Account
        • HYSA vs. Treasury Bills
        • How Savings Interest Is Calculated
        • Savings Account Minimum Balances
        • Savings Account
      • Bank Smarter
        • Top Banks for High-APY Savings
        • How Much Cash in Each Account
        • How Many Savings Accounts to Have
        • Managing Multiple Bank Accounts
        • Where to Put Your Money
        • When to Save vs. When to Invest
        • Savings Account Fees to Avoid
        • Banking Tips
        • Digital Banking
      • Banking Safety & Security
        • Set Up Bank Account Alerts
        • Avoid Check Scams
        • Missing Debit Card: Next Steps
        • When to Stop a Check Payment
        • Bank Fees
        • Debit Cards
        • Joint Bank Accounts
        • Banking How-To Guides
    • Sign In
    • Sign Up
    Amppfy
    Home » Budgeting and Saving » Insurance in a Household Budget: Health, Auto, Home, and Life
    Budgeting and Saving

    Insurance in a Household Budget: Health, Auto, Home, and Life

    Pull health, auto, home, and life premiums out of the bills pile and budget them as their own group.
    Thomas T.By Thomas T.October 6, 2026Updated:October 6, 20269 Mins Read
    Facebook Twitter LinkedIn Email Copy Link
    Insurance in a Household Budget: Health, Auto, Home, and Life
    Share
    Facebook Twitter LinkedIn Email Copy Link

    Most people think of insurance as a fixed bill, something that hits the account and disappears. But premiums, deductibles, and coverage gaps affect every other dollar you earn. Getting your insurance budget right means you’re not just covered: you’re also freeing up cash for goals that matter. A few deliberate choices here can protect your household and keep your savings on track. Here’s how to treat insurance as a real part of your spending plan, not just a line item you ignore.

    Insurance as its own group

    Insurance tends to get lumped in with “bills,” which buries it alongside electricity, water, and streaming services. That’s a problem. Your premiums for health, auto, home, and life coverage deserve their own group because they behave differently from other expenses. They protect future income. They shift risk away from your family. And they often have hidden costs (deductibles, copays, coverage limits) that don’t show up until something goes wrong.

    Personal insurance and pensions now account for 12.5% of average household spending[1], with healthcare adding another 7.9%. That’s roughly one in five dollars going toward protection and care. Treating all of that as a single “bills” line means you can’t see where the money is actually going.

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

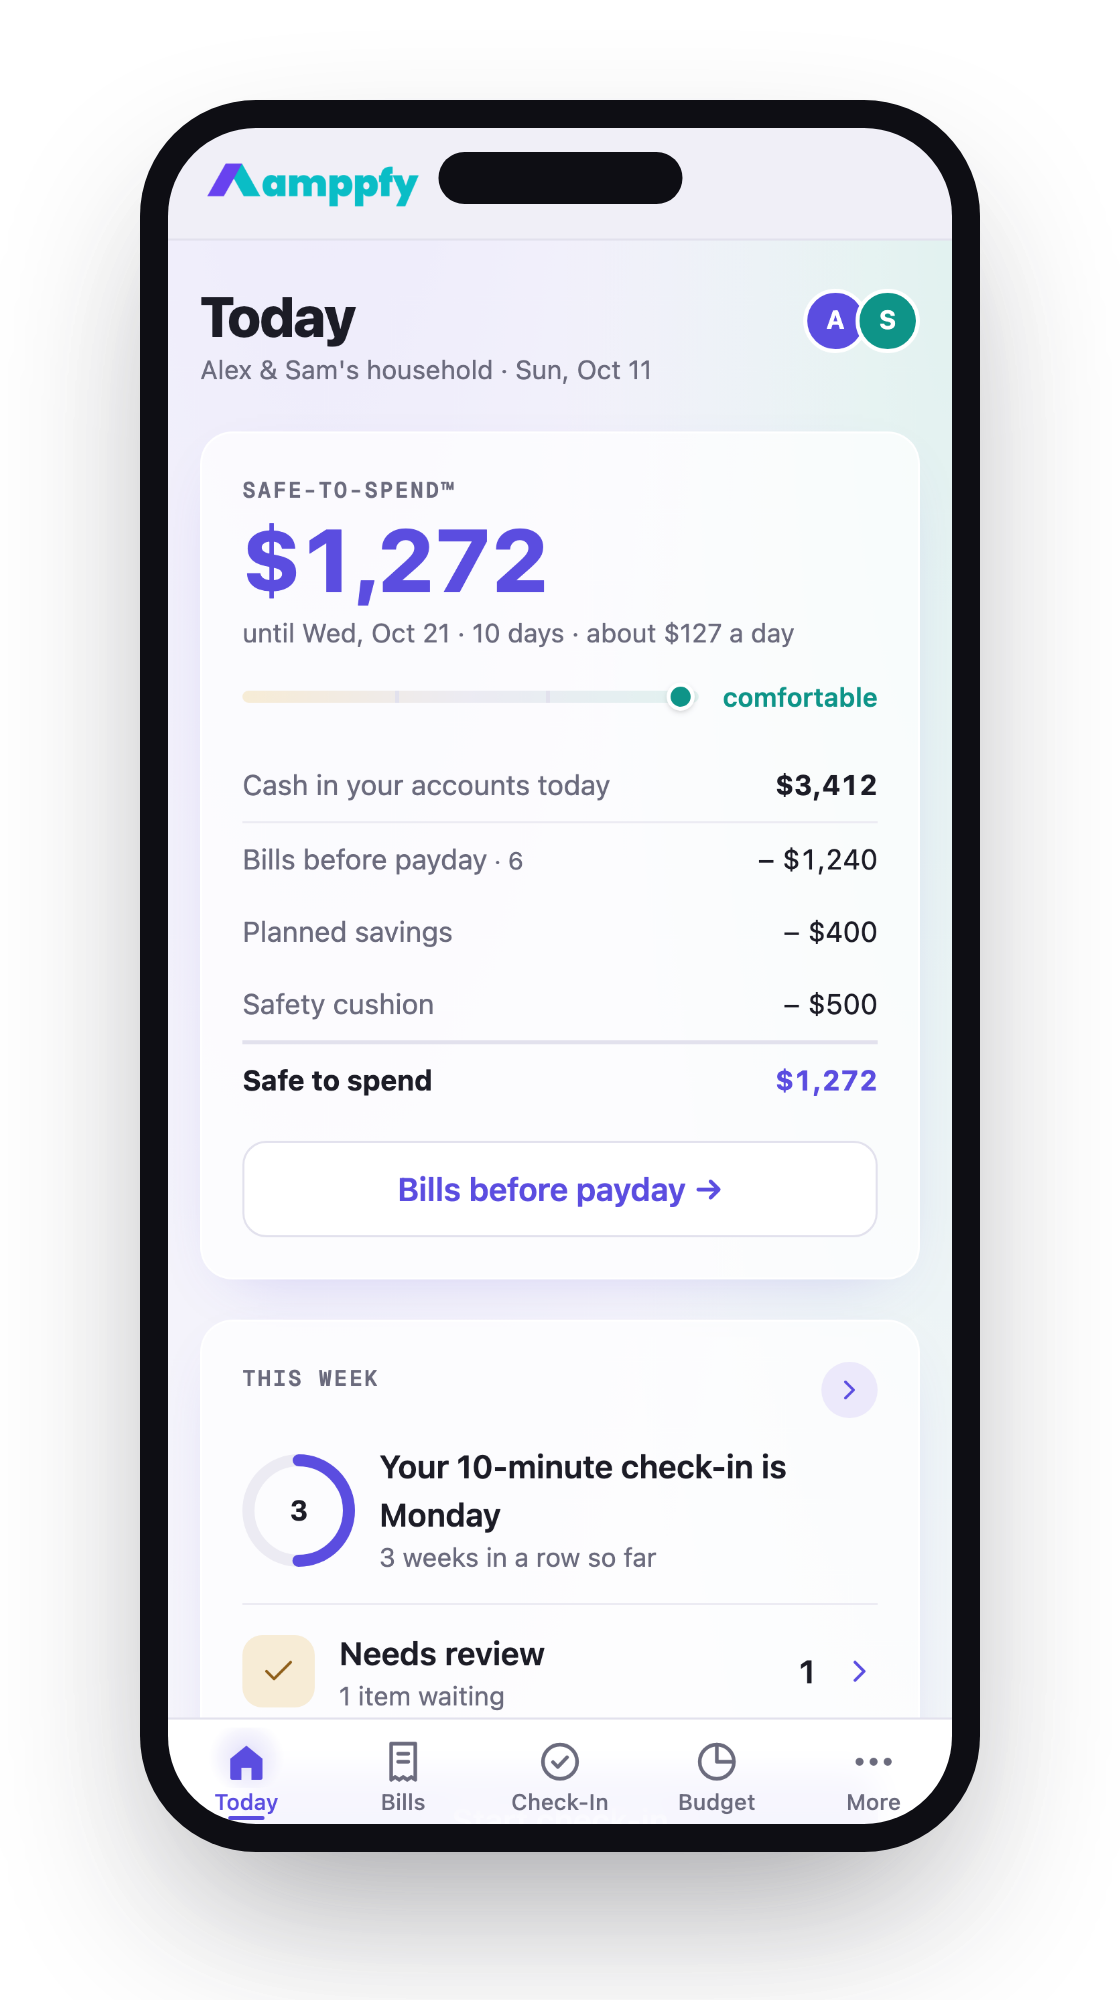
    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it

    Here’s a cleaner way to group your insurance costs:

    Category What It Covers Typical Payment Cycle
    Health Premiums, copays, prescriptions, HSA contributions Monthly or per paycheck
    Auto Liability, collision, comprehensive, roadside Monthly, 6-month, or annual
    Home/Renters Dwelling, personal property, liability Monthly (via escrow) or annual
    Life Term or whole life death benefit Monthly or annual

    When you build a household budget from your actual plan, separating insurance into its own slice makes it easier to spot where you’re over-covered, under-covered, or paying more than you need to.

    Amppfy’s Budget page breaks your month into four slices: Bills, Savings, Subscriptions, and Everyday spending. Insurance premiums land in Bills, while your HSA contributions sit in Savings. Seeing those numbers apart helps you make smarter trade-offs.

    Monthly premiums vs. six-month and annual bills

    Not every insurance bill arrives on the same schedule. Your health premium might come out of each paycheck. Your auto insurer might bill every six months. Your homeowner’s policy might renew once a year. That mismatch trips people up. A $900 auto premium due in July feels like a surprise if you’ve been budgeting month to month.

    The fix is simple: convert every premium to a monthly number, then decide how you want to pay.

    • A $900 six-month auto policy costs $150 per month. Set that aside each month so the bill is already funded.
    • A $1,400 annual homeowner’s premium works out to about $117 per month. If your mortgage escrow handles it, you’re already paying monthly: just know the number.
    • A $26 monthly term life premium is already on a monthly cycle. No conversion needed.

    Paying annually or semi-annually often saves you money. Many auto insurers charge a billing fee for monthly payments, sometimes $5 to $8 per installment[2]. Over a year, that’s up to $144 in fees[3] you don’t need to pay. If you can save the lump sum in advance, the annual option usually wins.

    The key is matching your premium schedule to your pay cycle. If you’re paid biweekly, you get 26 paychecks a year: two months will have three checks. Those “extra” checks are a natural place to fund a semi-annual or annual premium. Write the due date on your calendar. Set the money aside in advance. No surprises.

    Auto insurance rates also vary wildly by state. For 2026, some states like New Jersey face projected rate hikes near 10.5%[4], while Iowa may see rates drop over 6%. Your location shapes your budget more than you might expect.

    Deductibles: the hidden part of the cost

    Your premium is only half the equation. The deductible is the amount you pay out of pocket before insurance kicks in. A lower deductible means higher premiums. A higher deductible means lower premiums but more risk if something happens. This trade-off is the core decision in your insurance budget.

    How Deductibles Affect Your Real Cost

    Consider two auto policies for the same driver:

    Option A Option B
    Monthly premium $185 $140
    Deductible $500 $1,000
    Annual premium cost $2,220 $1,680
    Savings per year – $540

    Option B saves you $540 a year. But if you file a claim, you’ll pay $500 more out of pocket. If you go two or more years without a claim, Option B comes out ahead. The math favors higher deductibles for people who can absorb the upfront cost.

    Health Plan Deductibles and Out-of-Pocket Maximums

    Health insurance adds another layer. Under the CMS Final Rule for 2026, the maximum annual out-of-pocket limit is $10,600 for self-only coverage and $21,200 for family plans. That’s the ceiling on what you’d pay in a worst-case year, not counting premiums.

    If you choose a high-deductible health plan (HDHP), you can pair it with a Health Savings Account. The 2026 HSA contribution limits are $4,400 for individuals and $8,750 for families. HSA dollars are triple-tax-advantaged: tax-deductible going in, tax-free growth, tax-free withdrawals for medical expenses. That’s real money back in your pocket.

    The rule of thumb: only raise your deductible if you can cover it from savings without going into debt. If your emergency fund can’t handle a $1,000 deductible today, the lower-premium option isn’t actually saving you anything.

    Reviewing coverage once a year

    Insurance isn’t a set-it-and-forget-it expense. Your life changes. Your coverage should change with it. A yearly review takes about 30 minutes and can save you hundreds.

    What to Check Each Year

    • Did you get married, divorced, or have a child? Life events change who needs coverage and how much.
    • Did you pay off a car loan? You may no longer need full collision coverage on an older vehicle.
    • Did your home’s value change? Rebuilding costs fluctuate with materials and labor prices.
    • Did your income change? A raise might mean you need more life insurance or qualify for a different health plan tier.

    Where People Overpay

    Loyalty to one insurer year after year is expensive. Rates shift constantly. Get at least two competing quotes for auto and home insurance before each renewal. Bundle discounts (auto plus home with the same carrier) can save 10% to 25%, but only if the bundled price is actually lower than two separate policies from different companies. Check the math.

    Life insurance is another area worth revisiting. A $500,000 20-year term policy for a healthy 30-year-old costs roughly $26 per month. If you bought your policy five years ago at a higher rate and your health has improved, you might qualify for better pricing. A new medical exam could drop your premium.

    One more thing: in 2025, 6% of homeowners went without insurance entirely, with most citing cost as the reason. Dropping coverage feels like a savings move, but one storm or fire can wipe out years of equity. If your premium feels unaffordable, raise the deductible or shop for a new carrier before canceling.

    Keeping insurance from crowding out savings

    Insurance protects what you have. Savings builds what you want. Both matter. The danger is letting premiums consume so much of your paycheck that nothing goes toward your goals.

    Here’s a worked example. Say your monthly take-home is $5,200:

    $5,200 income − $1,800 rent − $680 insurance (health, auto, renters, life) − $400 savings goals − $300 cushion = $2,020 Safe-to-Spend™

    That $680 is 13% of take-home pay. If it creeps toward 20% without a deliberate reason, you’re likely over-insured or under-shopping. The fix isn’t to cut coverage you need. It’s to adjust deductibles, drop riders you don’t use, and shop competing quotes.

    A few concrete moves:

    • Drop roadside assistance from your auto policy if you already have it through your phone plan or a membership.
    • Cancel rental car reimbursement coverage if you have a second vehicle or could use a rideshare for a few days.
    • Switch from a low-deductible health plan to an HDHP and route the premium savings into an HSA. You’ll pay less per month and build a tax-advantaged medical fund.
    • Review your life insurance amount. If your kids are grown and your mortgage is nearly paid off, you may not need the same death benefit you bought at 30.

    Each of those moves frees up $20 to $80 a month. That’s $240 to $960 a year you can redirect toward an emergency fund, a vacation, or paying down debt. Small shifts in your insurance spending create real room for saving.

    Frequently Asked Questions

    How much of my budget should go toward insurance?
    There’s no single right number, but a useful benchmark is 10% to 15% of your take-home pay across all insurance types. If you’re spending more than that, it’s worth shopping for new quotes or adjusting deductibles. If you’re spending less, make sure you’re not skipping essential coverage like health or liability.

    Should I pay insurance premiums monthly or annually?
    Annual or semi-annual payments usually cost less because you avoid installment fees. The catch is that you need the lump sum ready when the bill arrives. If cash flow is tight, set aside the monthly equivalent in a separate savings bucket so the annual bill doesn’t catch you off guard.

    Is it worth raising my deductible to lower my premium?
    Yes, if you have enough in savings to cover the higher deductible without borrowing. A $500 increase in your deductible might save you $40 to $60 per month on premiums. Over a claim-free year, that’s $480 to $720 in your pocket. Just make sure your emergency fund can handle the gap.

    How do I know if I have too much or too little life insurance?
    A common guideline is 10 to 12 times your annual income, but your actual need depends on your debts, dependents, and your partner’s earning power. If your mortgage is small and your kids are independent, you might need far less. If you’re the sole earner with young children, you might need more. Revisit this number every year or after any major life change.

    Make Insurance Work Inside Your Plan, Not Against It

    Insurance is protection, not punishment. Grouping it separately, matching payment cycles to your payday, understanding your deductible trade-offs, and reviewing coverage annually: these steps keep premiums from quietly eating the cash you need for everything else. The goal is a household where insurance does its job and your savings still grow.

    If you want one clear number for what’s safe to spend after your premiums, bills, and savings goals are accounted for, Amppfy can show you that in about ten minutes. Enter your balances, bills, and payday once, and your Safe-to-Spend™ number is always there. Get Amppfy free on iPhone or the web and see exactly where insurance fits in your month.

    1. bls.gov

    2. mass.gov

    3. insuranceopedia.com

    4. valuepenguin.com

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it
    Budgeting Basics car insurance Cut Expenses Family Budgeting Healthcare Costs home insurance life insurance Monthly Budget
    Share. Facebook Twitter LinkedIn Email Copy Link
    Previous ArticleTransportation Budget: Car Payment, Insurance, Gas, and Repairs in One Number
    Next Article Debt Payments in Your Budget: How Much Is Too Much?
    Thomas T.

    Thomas is a Personal Finance Writer and Financial Content Strategist with over 10 years of experience helping individuals make smarter financial decisions. He specializes in topics such as budgeting, debt management, saving strategies, and financial behavior, translating complex financial concepts into clear, actionable guidance. His work focuses on empowering readers to build sustainable financial habits and confidently navigate their financial lives, combining data-driven insights with practical, real-world advice.

    More Like This

    When Will I Get My First Paycheck? Weekly, Biweekly, and Paid in Arrears

    By Thomas T.October 19, 2026

    Pay Period Calculator: How to Count Your Paychecks and Pay Dates by Hand

    By Thomas T.October 19, 2026

    Biweekly Pay Schedule 2026: Every Remaining Payday This Year, and the 2027 Dates

    By Thomas T.October 19, 2026
    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number.

    Download on the App Store

    Prefer the web? Sign up free ›

    Amppfy dashboard on an iPhone showing the Safe to Spend number with the math under it
    Helpful Resources

    When Will I Get My First Paycheck? Weekly, Biweekly, and Paid in Arrears

    October 19, 2026

    Pay Period Calculator: How to Count Your Paychecks and Pay Dates by Hand

    October 19, 2026

    Biweekly Pay Schedule 2026: Every Remaining Payday This Year, and the 2027 Dates

    October 19, 2026

    What Is a Pay Period? Weekly, Biweekly, Semi-Monthly, and Monthly, Explained

    October 19, 2026

    Financial Clarity. Everyday Confidence.

    Facebook X (Twitter) YouTube LinkedIn
    Calculators

    Emergency Fund Calculator

    Compound Interest Calculator

    Interest Rate Calculator

    Net Worth Calculator

    Mortgage Calculator

    How Much Home Can I Afford

    Debt-to-Income Ratio Calculator

    Cost of Living Calculator

    Savings Calculator

    Savings Goal Calculator

    Monthly Budget Calculator

    Latest Resources

    How to Open a Joint Bank Account Online (Without a Branch Visit)

    October 19, 2026

    Regions Joint Account: Opening One Together or Adding a Partner

    October 19, 2026

    TD Bank Joint Account: How to Open One or Add a Partner

    October 19, 2026

    What Time Does Citizens Direct Deposit Hit? Early Pay and Posting Times

    October 19, 2026
    About & Legal

    About Amppfy

    Documentation

    Editorial Policy

    EULA

    Terms of Use

    Acceptable Use Policy

    Privacy Policy

    Cookie Policy

    Disclaimer

    Do Not Sell or Share My Personal Information

    Acceptable Use Policy

    Disclaimer: Amppfy is committed to keeping its information transparent, accurate, and up-to-date. The information on Amppfy is provided for educational and informational purposes only and should NOT be considered financial, investment, tax, or legal advice. You should consult a qualified financial professional before making any financial decisions. This information may differ from what you find on the specific product or service provider’s website. All information, content, software, tools, products, or services on Amppfy are presented without warranty or guarantee. Please review the specific provider’s terms and conditions when evaluating products or services. By accessing Amppfy or using our AI generator tools, you acknowledge that you have read, understood, and agreed to our EULA, Terms of Use, Acceptable Use Policy, Privacy Policy, Cookie Policy, and Disclaimer. Amppfy.com uses cookies. For more information, visit Amppfy’s Cookie Policy. Amppfy may be compensated through third-party advertisers and affiliates. For more information, visit Amppfy’s Disclaimer.

    Copyright© 2026 Amppfy | All Rights Reserved

    Type above and press Enter to search. Press Esc to cancel.

    Advertiser Disclosure: Products may include affiliate links related to financial products or services. We may earn a commission at no additional cost to you. Our content remains independent and focused on helping you make informed financial decisions.
    Fact Checked
    Financial Disclaimer

    This content is for informational and educational purposes only and should not be considered financial advice. Personal finance decisions—including budgeting, saving, investing, credit, mortgages, taxes, and debt management—depend on your individual circumstances. Always consult a qualified financial professional before making financial decisions.

    Editorial Standards and Content Integrity

    Our editorial process ensures accuracy, clarity, and trust across all personal finance topics, including budgeting, saving, investing, and debt management. Content is created using credible sources such as government agencies, academic research, and established financial institutions, and may incorporate insights from industry experts when relevant. Each article is reviewed for accuracy, timeliness, and relevance before publication and updated as needed to reflect changes in financial guidelines and best practices, with the goal of providing clear, evidence-based information to help readers make informed financial decisions.

    Learn more about our editorial policy and guideline.
    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Download the app and enter your balances, bills, and payday. About ten minutes to one clear number: what’s safe to spend before payday.Your balances, bills, and payday. Ten minutes to one clear number. Learn more ›

    Download on the App Store
    Scan with your iPhone to get the app

    Free  ·  No credit card  ·  Just your balances

    Prefer the web? Sign up free ›

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Enter your balances, bills, and payday once. About ten minutes to one clear number, with the math shown under it.

    Download on the App Store
    Scan with your iPhone to get the app

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances