
If you’ve just started a new job, or switched banks, the first paycheck can feel like a loose thread. You want it landing in your Chase checking account, on time, with no paper check in the mail. The good news is that the setup is short. Chase pre-fills most of the paperwork for you, and the rest is a handoff to your employer.
This guide walks through how to set up direct deposit with Chase using the steps Chase itself publishes. It covers what you need, where to tap, how long the first deposit usually takes, and how to confirm it arrived. It also covers the part most guides skip: what to do with the money once it’s sitting in your account.
Think of it as a short checklist. Most people finish the Chase side in under ten minutes. The waiting part belongs to your employer’s payroll calendar, not to you.
What you need before you start
Gather everything first. That way the form takes one pass, not three.
Chase lists the information a direct deposit form needs. Here it is, line by line:
| Line | What it is |
|---|---|
| Employer or depositor’s name and address | The company or agency sending the money |
| Your employee ID or account number with the depositor | How payroll matches the form to you |
| Your Chase account number | The checking account receiving the deposit |
| Your routing (ABA) number | The 9-digit number that identifies Chase |
If you use the pre-filled form, Chase fills in the account and routing numbers for you. If you use the blank PDF, you type them in yourself. Either way, check each digit twice. One wrong number sends the form back, and you lose a pay cycle.
The voided check
Chase says to deliver the form with a voided check when you hand it to your employer. A voided check is a regular check with “VOID” written across it in large letters. The bank details on the bottom stay readable, but nobody can cash it.
Think of it as a photocopy with a padlock on it. Payroll can read the numbers. No one can spend from it.
No checkbook?
That’s common. The pre-filled Chase form already carries your account and routing numbers, which is what payroll needs to see. Ask your employer whether they accept the form on its own. Some payroll teams also have their own portal where you type the numbers in directly. In that case, use the Chase form as your reference sheet.
Step by step, as Chase publishes it
Chase offers two routes: a pre-filled form or a blank PDF. The pre-filled form is faster. Below are the steps exactly as Chase lists them on its direct deposit page, as of October 2026.
On chase.com
- Sign in to chase.com.
- Choose your checking account.
- Go to “More,” then “Account Services.”
- Click “Set up direct deposit form.”
- Download, print or email the form to your employer.
In the Chase Mobile app
- Sign in to the Chase Mobile app.
- Choose your checking account.
- Choose “Manage Account.”
- Tap “Set up direct deposit form.”
- Download, print or email the form to your employer.
Chase also publishes a second app path in its mobile help tips:
- Tap the account.
- Swipe up.
- Tap “Set up direct deposit form.”
- Check the details.
- Tap “Create form.”
Both app routes end in the same place: a form with your details filled in, ready to send.
The blank PDF option
Prefer paper, or need a form for a second employer? Download Chase’s blank PDF. Fill in the 9-digit routing number and your account number. Add the employer details from the table above. Then give it to your employer.
Government benefits work differently
Social Security, military pay and other federal benefit income don’t use the employer form. Chase points you to the Treasury’s Go Direct enrollment at fiscal.treasury.gov/GoDirect. Enroll there, and the agency routes payments into your Chase account.
How long the first deposit takes
This is the part that makes people nervous. It shouldn’t.
Chase says direct deposit “usually takes up to two pay cycles to kick in,” and “it’s different for each employer,” as of October 2026. That’s the whole published rule. Chase doesn’t give a fixed number of days, because the timing sits with your employer’s payroll system, not the bank.
Here’s what that means in plain arithmetic. If you’re paid every two weeks, two pay cycles is up to about four weeks. If you’re paid twice a month, it’s up to about one month. If you’re paid monthly, it could be up to two months.
During that gap, your employer typically pays you another way, often a paper check or a payroll card. You still get paid. The only change is the delivery method.
A few things can push you toward the faster end:
- Submit early. Hand the form in the same day you start, not the day before payroll closes.
- Ask about the cut-off. Payroll teams usually have a date each cycle after which changes roll to the next period. Ask yours what it is.
- Use their portal if they have one. Typing the numbers in yourself removes a step.
Once deposits are running, a different question takes over: what time of day the money shows up. That depends on posting schedules and whether early pay applies. The details are in this breakdown of when Chase direct deposits hit, including early pay and pending deposits.
Checking it worked, and what to do if it did not land
Chase’s advice is simple: confirm the deposit each pay cycle. Not just the first one. Every one.
That sounds like a chore. It takes about 30 seconds.
How to confirm
Open the Chase Mobile app on payday. Tap your checking account. Look for a deposit from your employer in the activity list. Match the amount against your pay stub. If they line up, you’re done for this cycle.
You can also turn on Chase’s direct deposit alerts. Chase offers them so you get a notice when a deposit arrives. That replaces the check-the-app habit with a single glance at your phone.
If it didn’t land
First, check the calendar. If this is your first or second pay cycle since you submitted the form, the deposit may simply not be live yet. Look for a paper check or payroll card payment instead.
If it should have arrived, work through these in order:
- Compare the numbers. Pull up the form you sent. Check the routing and account numbers against your Chase app, digit by digit.
- Check your pay stub. Most stubs show where the money went, often with the last few digits of the account.
- Ask payroll. Confirm they received the form and entered it before the cut-off.
- Contact Chase. If payroll says the money left on time, Chase can look for it on their end.
Most misses trace back to a typo or a missed cut-off. Both are fixable in one conversation. For a fuller walkthrough of the first hour after a missing paycheck, see what to check when a direct deposit didn’t hit.
Once it lands: what is actually safe to spend
The deposit shows up. Your balance jumps. It’s tempting to treat the whole number as yours to use.
It isn’t, quite. Some of that money already belongs to bills due before your next payday. The calm move is to take those out first, on paper, before you spend anything.
How the math actually works
Here’s the logic, line by line:
| Step | Action |
|---|---|
| 1. Start with your balance | What Chase shows after the deposit posts |
| 2. Subtract bills due before next payday | Rent, utilities, phone, subscriptions |
| 3. Subtract planned savings | What you want moved to savings this cycle |
| 4. Subtract a cushion | A small buffer you choose for surprises |
| = What’s left | Your real spending money until payday |
Now with numbers. Say your $2,400 paycheck lands and your checking balance reads $2,650.
- Rent of $1,200 is due on the 1st, before your next payday: $2,650 − $1,200 = $1,450.
- Phone ($65) and electric ($110) also fall before payday: $1,450 − $175 = $1,275.
- You plan to save $200 this cycle: $1,275 − $200 = $1,075.
- You keep a $150 cushion: $1,075 − $150 = $925.
So $925 is the honest number for the next two weeks. Not $2,650. Seeing the steps is what makes the result trustworthy.
Keeping it current without effort
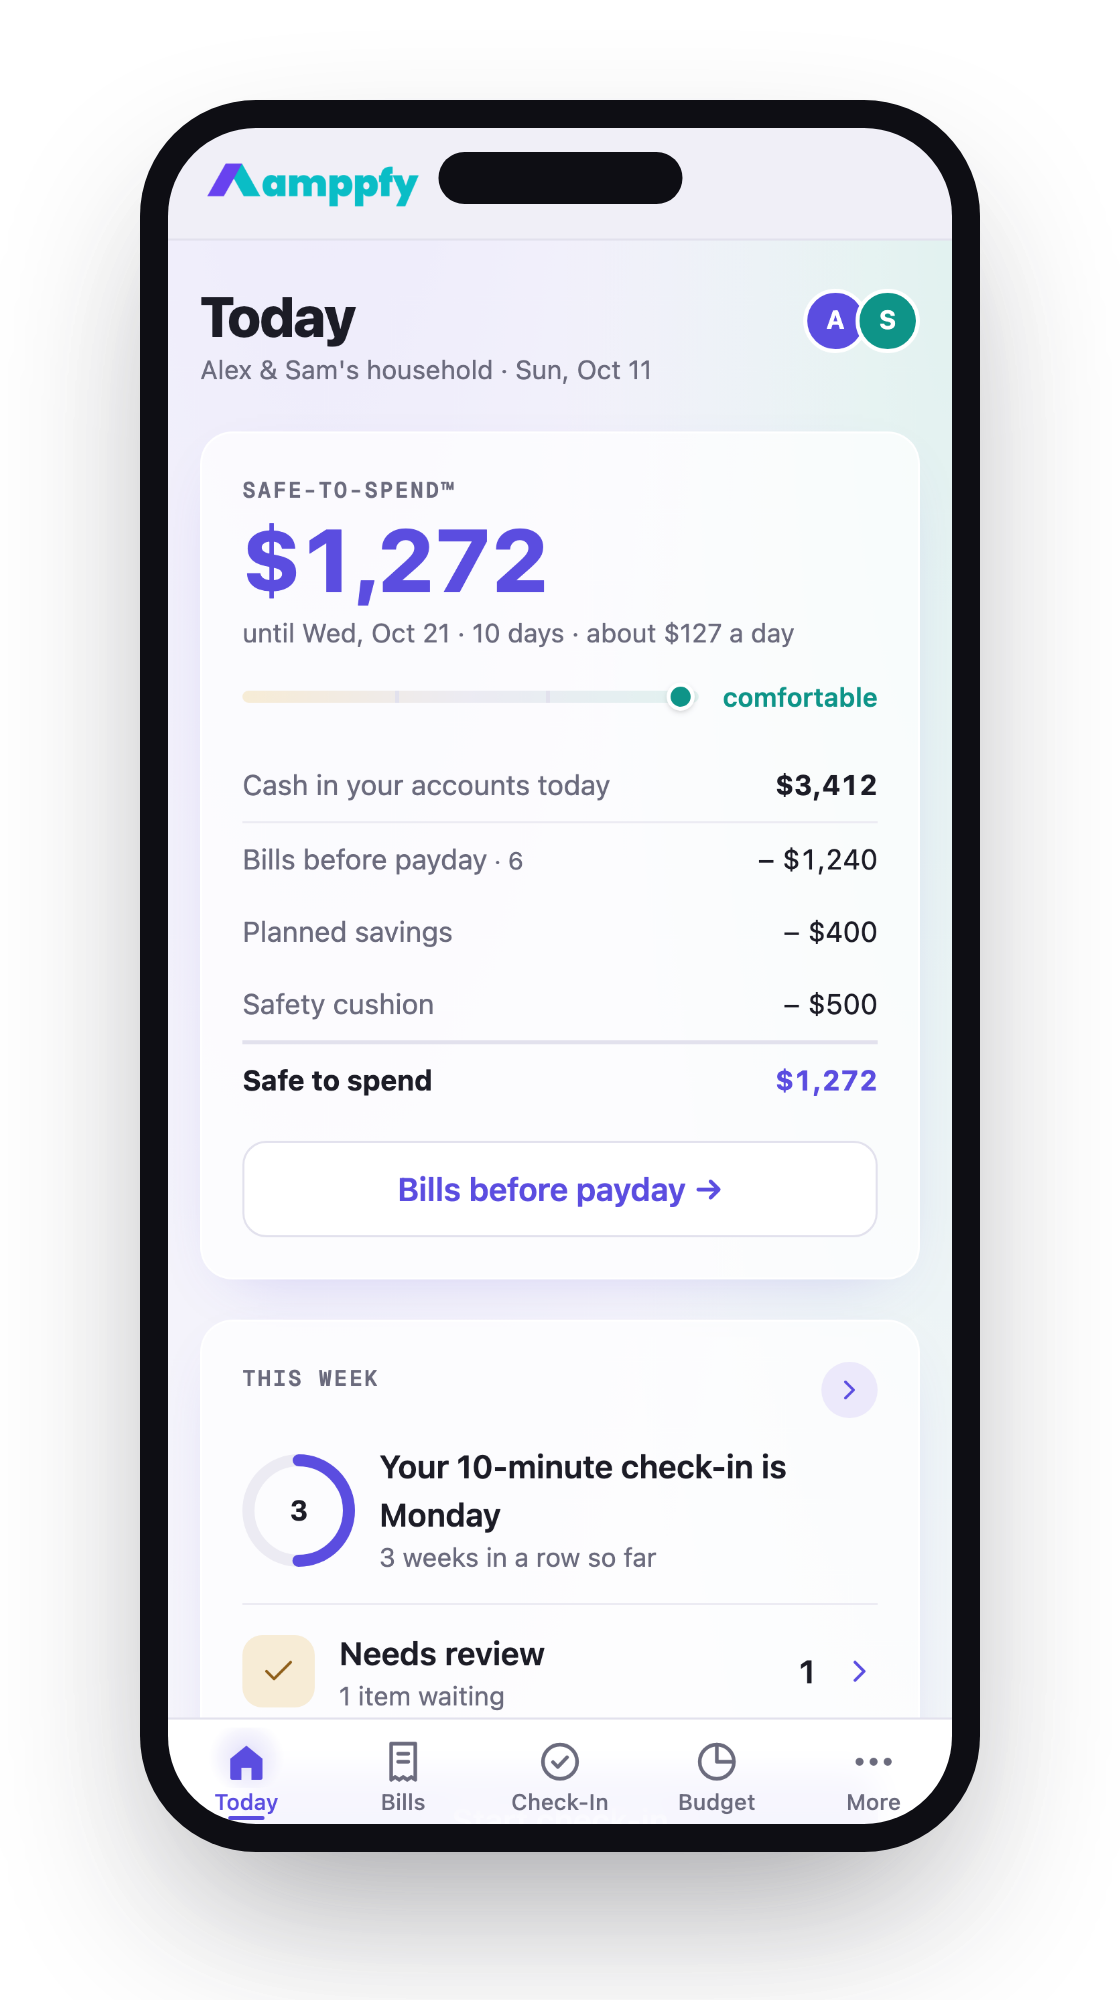
The tricky part isn’t the math. It’s redoing it every time a bill posts or a balance shifts. That’s the job Amppfy does. You type in balances, bills and paydays, and it shows one Safe-to-Spend™ number with those four lines printed underneath. A 10-minute weekly check-in keeps it accurate, and the bills calendar marks your lowest-cash day before payday. If you share bills with a partner, they can get their own login and see the same number, while private accounts stay private.
For the full walkthrough of every route (employer form, your bank’s pre-filled form, or a government payment), see how to set up direct deposit.
FAQ
Can I set up Chase direct deposit without a checkbook?
Yes. The pre-filled form from the Chase app or chase.com already includes your routing and account numbers. Chase says to include a voided check, so ask your employer whether the form alone is enough. Many payroll teams accept it.
Where do I find the direct deposit form in the Chase app?
Sign in, choose your checking account, tap “Manage Account,” then “Set up direct deposit form.” Or tap the account, swipe up, tap “Set up direct deposit form,” check the details and tap “Create form.”
Why hasn’t my first direct deposit arrived?
Chase says it usually takes up to two pay cycles to kick in, and it differs by employer, as of October 2026. Until then, your employer typically pays you another way. If it’s past two cycles, check the numbers and ask payroll.
How do I set up direct deposit for Social Security or military pay?
Government benefit income doesn’t use the employer form. Enroll through the Treasury’s Go Direct site at fiscal.treasury.gov/GoDirect, using your Chase routing and account numbers.
Setting up Chase direct deposit comes down to three moves. Grab the pre-filled form, hand it to payroll with a voided check, and confirm each deposit when it lands. The wait is your employer’s part, and it’s usually no longer than two pay cycles.
Once the money arrives, one rule keeps things calm: bills due before your next payday come out first. Whatever is left after savings and a small cushion is what you can spend. If you’d rather not redo that arithmetic every payday, try Amppfy free on iPhone or the web. Take ten minutes this week to enter your balances and bills, and your next paycheck will arrive with a plan already waiting.