
Two people, two schedules, one shared rent payment. Getting to a bank branch together on a weekday can feel harder than the money talk itself. The good news: you often don’t have to.
Many banks now let you open a joint bank account online from your couch, in one sitting. Others still want you both at a desk with your IDs. The difference usually shows up when you try to add a partner to an account you already have.
This guide sorts that out bank by bank. It shows what you’ll need, how the steps go, and what being joint actually means for your money. Every bank detail comes from that bank’s own page, as of October 2026.
The short answer
Yes, for a new account, usually. Many banks let two or more adults open a joint account entirely online, with no branch visit. Each of you needs a valid government ID and a Social Security number.
Adding a partner to an account you already have is different. Online banks tend to handle it with a menu option or a form. Several big branch banks still ask every owner to show up in person.
So the logic is simple:
- Starting fresh? Open a new joint account online. It’s usually the fastest route.
- Keeping an old account? Check the table below first. You may need a branch, or a form.
If you want the wider list, our hub on online banks that offer joint accounts covers who does and who doesn’t.
Which banks let both owners apply online, and which need a branch
Each row comes from the bank’s own page, as of October 2026.
| Bank | Open a new joint account online | Add a partner to an existing account | Source |
|---|---|---|---|
| SoFi | Yes | Online: gear icon > “Add a joint account owner” | SoFi help page · our SoFi guide |
| Ally | Yes, select Joint when opening | Additional Account Owner Application | Ally form · our Ally guide |
| Capital One 360 | Yes | Online: Account Services & Settings > Add/View Joint Account Holder | Capital One help · our Capital One guide |
| Chase | Branch only | All owners visit a branch with two forms of ID | Our Chase review |
| Bank of America | Not stated on the bank’s page | Financial center appointment, all owners present | BofA ownership changes · our BofA guide |
| Wells Fargo | Yes, primary owner selects Joint, both give info, 18+ online | No published online route | Wells Fargo FAQs · our Wells Fargo guide |
| PNC | Yes, upload photo IDs of all holders | Both visit a branch | PNC guide · our PNC guide |
| TD Bank | No online route published | Both owners visit a TD Bank | TD joint accounts |
| Regions | Yes, if both are age of majority | In a branch | Regions joint accounts |
| USAA | Not stated on the bank’s page | Add another USAA member after opening | USAA checking · our USAA guide |
| Navy Federal | Joint owner at enrollment | Form 97AJO via Message Center, fax, mail, or branch | Form 97AJO · our Navy Federal guide |
| U.S. Bank | Yes: select the joint option and add a co-applicant (name, email, phone) at the end of the online application | No online route published; a branch or 800-USBANKS | U.S. Bank how-to · our U.S. Bank guide |
| Truist | Opens as an individual account online, then a joint owner is added | Online after opening, if the joint owner is 18 or older (full name, last 4 of SSN, email); under 18 at a branch | Truist application page · our Truist guide |
Two of those rows deserve a sentence each. U.S. Bank’s how-to page says you choose the joint option in its online application and add a co-applicant with their name, email and phone at the end; it publishes no online route for adding an owner to an account you already have, so that means a branch visit or a call. Truist’s application page says you open an individual account first and then add a joint owner who is at least 18 by giving their full name, the last four digits of their Social Security number and an email address; anyone under 18 is added at a branch. The fees and waivers for both are in our guides to U.S. Bank joint accounts and Truist joint accounts.
How to open a joint account online: the steps most banks share
The screens differ. The pattern doesn’t. Banks typically ask both applicants for a government-issued ID, Social Security number, current address, and date of birth.
Gather this first. It saves the back-and-forth.
- Pick the account. Choose checking, savings, or both. Look for a “Joint” option at the start.
- Primary applicant starts. One of you fills in your own details and selects Joint.
- Add the second person. Enter their name, date of birth, SSN or ITIN, and address. Some banks send a secure link instead, so your partner verifies identity on their own phone.
- Verify IDs. Expect a photo of a driver’s license or passport. PNC, for example, asks you to upload photo IDs for all holders.
- Fund it. Make an opening deposit from an existing account. Minimums vary by bank, so check the account page.
- Set up logins. Each owner usually gets their own username and card.
With documents ready, the whole thing often takes about 5 to 10 minutes. If your partner is at work, the invite-link route means you don’t need to sit side by side.
Adding a partner to an existing account: usually a branch, sometimes a form
This is where plans stall. You love your current account. Maybe it has years of history and autopays attached. Converting it is reasonable, but the bank decides how.
Online banks make it lightest. SoFi and Capital One 360 put the option right in account settings. Ally and Navy Federal use a form, and Navy Federal accepts form 97AJO through its Message Center, so you can still skip the trip.
Branch banks lean the other way. Chase, Bank of America, PNC, TD Bank, and Regions all route this through a branch or appointment. Wells Fargo publishes no online route for it. USAA lets you add another owner after opening, but that person must be a USAA member.
So weigh it plainly. If a branch visit is hard, opening a fresh joint account online and moving your autopays may be quicker than one shared afternoon off. Moving bills takes a list and an evening, not a crisis.
What changes once it is joint
Three things shift the moment the account turns joint.
Access
Joint checking runs on an “either/or” basis. Any account owner can conduct transactions independently. Your partner doesn’t need your approval to pay a bill or withdraw cash.
Liability
Ownership is shared, not split by who deposited what. Both owners typically have equal legal rights to all the funds. And each person is fully responsible for the account, so one overdraft affects you both.
Survivorship
Many joint accounts pass to the surviving owner if one of you dies. Terms vary, so read your bank’s account agreement and confirm how yours is titled.
None of this is a reason to worry. It’s a reason to agree on rules up front: who pays what, and a heads-up before big withdrawals.
Joint, separate, or both: one number for two people
There’s no single right setup. Some couples pool everything. Some keep everything apart. Many go hybrid: a joint account for rent and groceries, plus private accounts each.
Shared accounts do bring a benefit. They create natural visibility into spending habits, which can lead to calmer money talks. The catch with hybrid setups is the arithmetic. With three or four accounts, neither of you can say at a glance what’s safe to spend before payday.
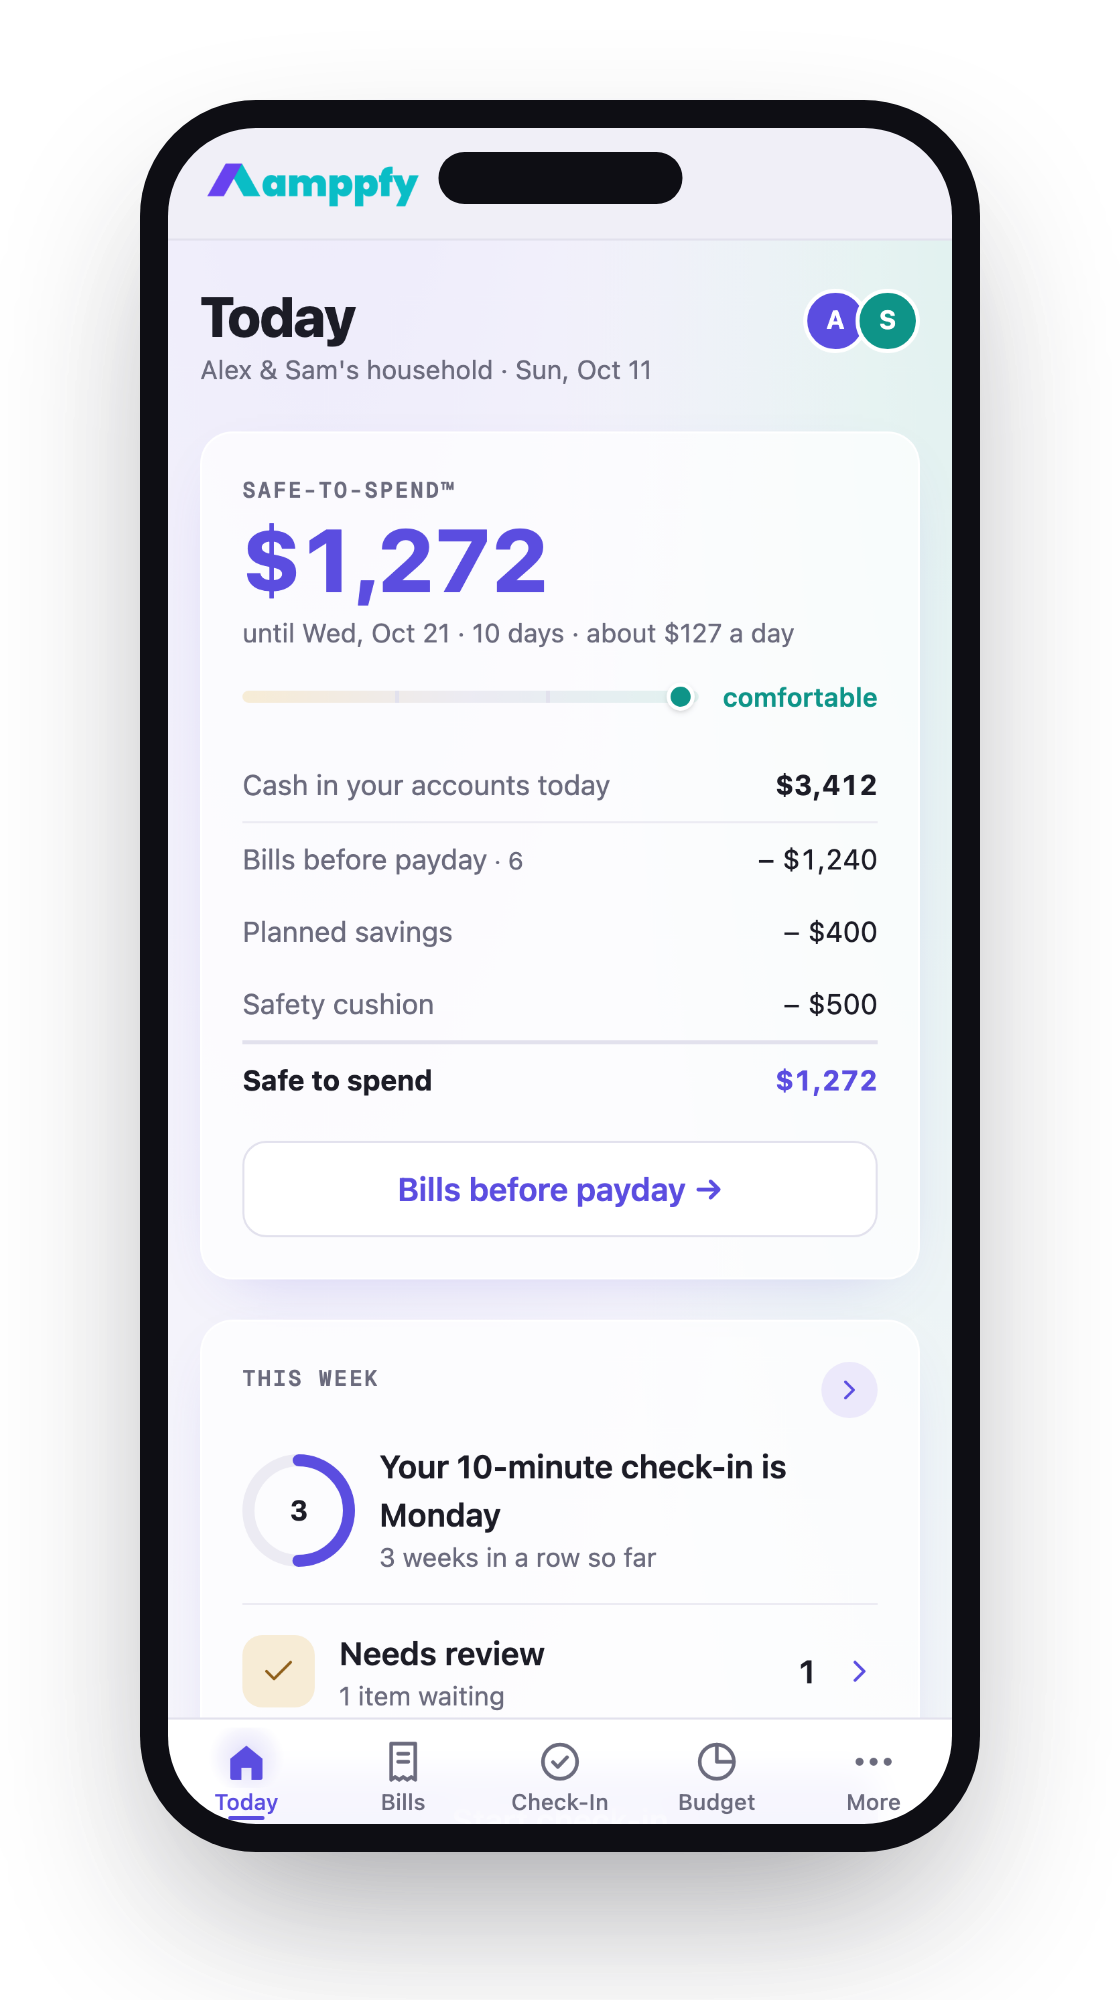
That’s the gap Amppfy fills. Each partner gets their own login and sees the same Safe-to-Spend™ number. It’s cash minus bills due before payday, minus planned savings, minus a cushion. Private accounts stay private. You type in balances yourself, no bank login, and a weekly 10-minute check-in keeps it current.
For setup help on each style, read our guide to bank accounts for couples.
For the joint-versus-separate decision itself, see bank accounts for couples: joint, separate, or both.
FAQ
Do both of us need to be present to open a joint bank account online?
Not physically. Many banks let one person start and invite the other by secure link. Both still need ID and an SSN or ITIN.
Can I add my partner online to my current account?
At SoFi and Capital One 360, yes, through settings as of October 2026. Ally and Navy Federal use a form. Most big branch banks require an in-person visit.
Does my partner have to be a member first?
At USAA, yes: you can add another USAA member as an owner. Navy Federal also handles joint owners through its own membership process and form 97AJO.
Who owns the money in a joint account?
Both of you, typically equally, regardless of who deposited it. Either owner can use it.
The pattern is clear. New joint accounts are usually an online, ten-minute job. Adding someone to an old account depends on the bank, so check the table before you plan a branch trip.
Once the account is open, give it one shared view. Take 15 minutes this week to set up Amppfy for couples: two logins, one number, nothing private exposed.