Close Menu

    Subscribe to Updates

    Get the latest creative news from FooBar about art, design and business.

    What's Hot

    Social Security COLA 2027: What the 3.6% Raise Means for Your Monthly Plan

    November 6, 2026

    Best Free Budget Apps in 2026: iPhone, Android, and Web

    November 6, 2026

    Federal Pay Period Calendar for 2027: Every Pay Period and Payday

    November 6, 2026
    Facebook X (Twitter) Instagram
    Amppfy
    • Safe to Spend™ App
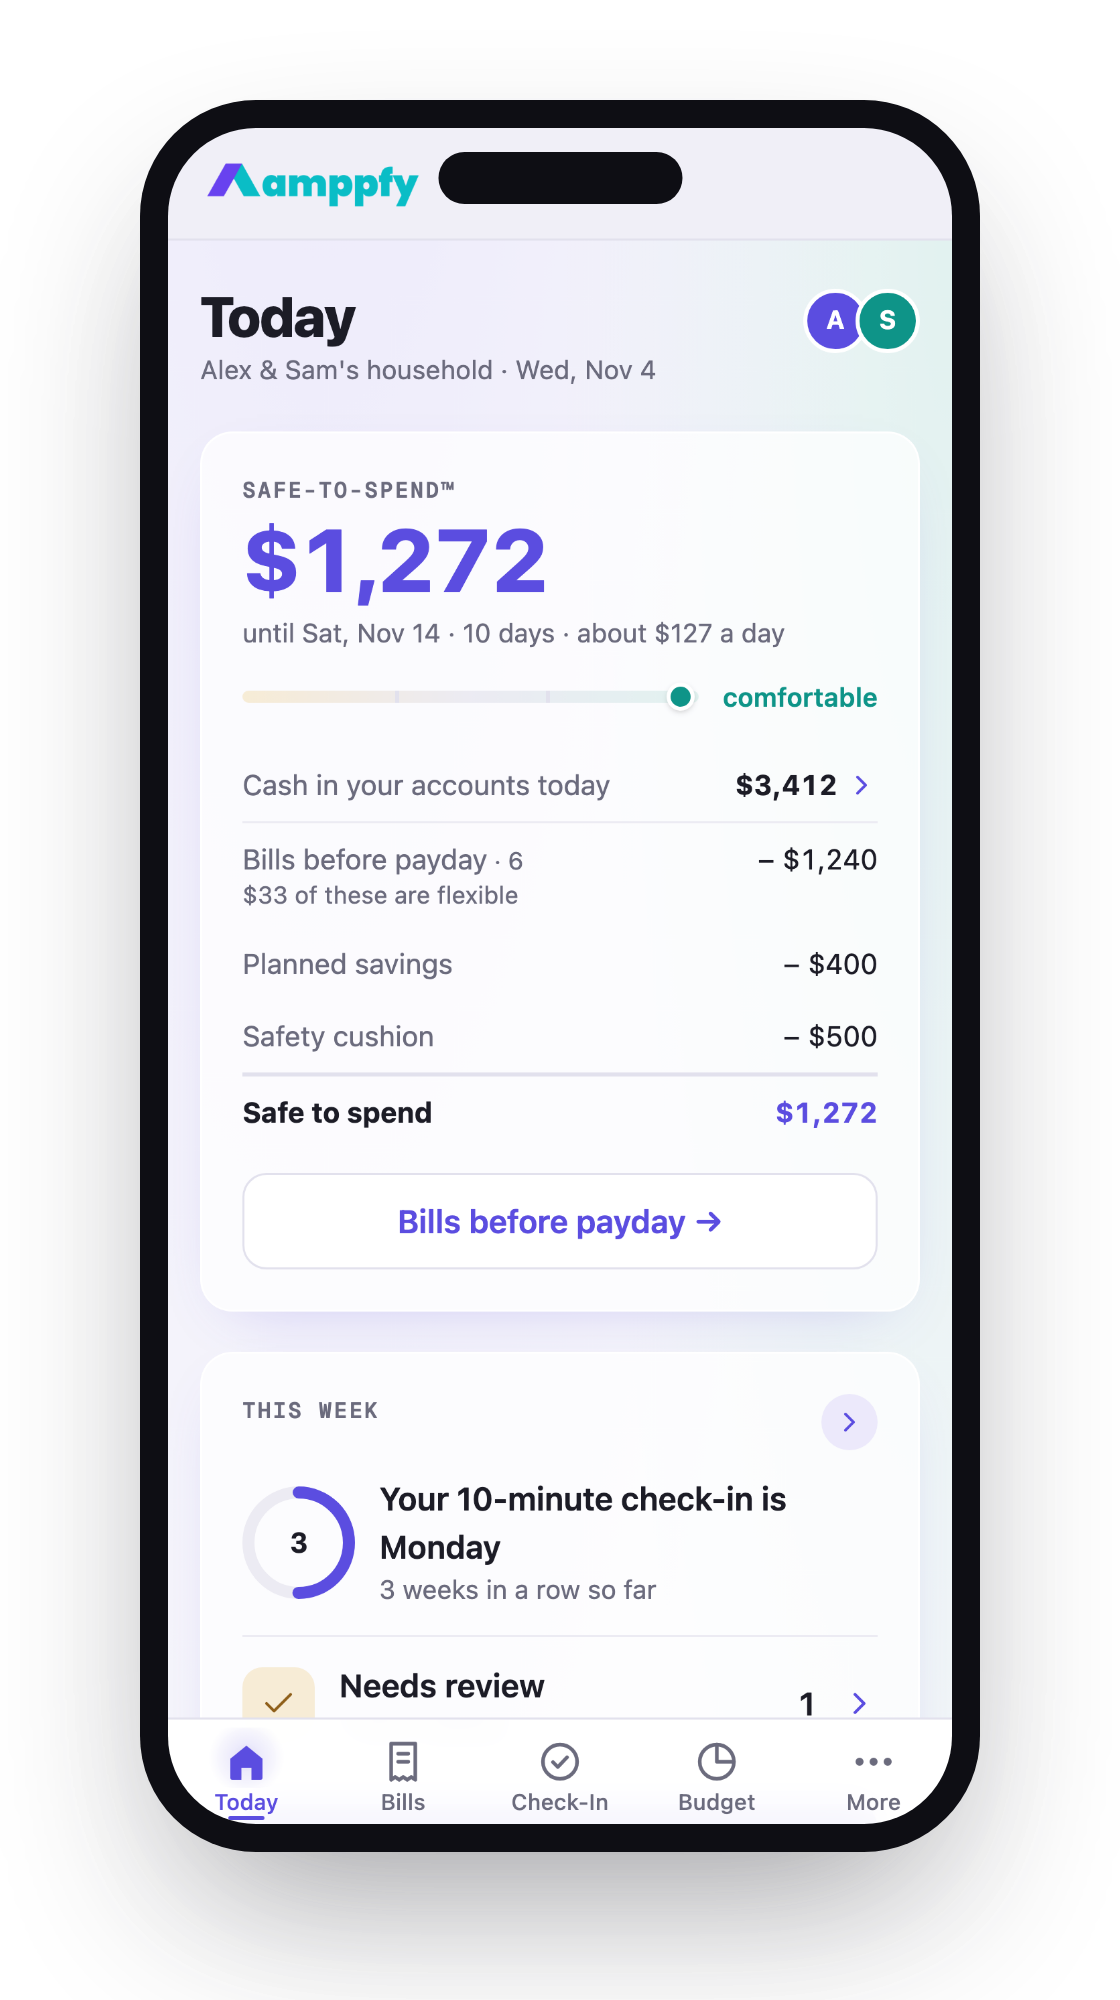
      • Amppfy on iPhone — one clear number with the status scale and the math under itYour number, in your pocketFree on iPhone and Android, with the same account on the web.
        • Download on the App Store
        • Get it on Google Play
        • Prefer the web? Sign up free ›
      • The app
        • OverviewOne clear number for what’s safe to spend before payday
        • Safe-to-Spend™The four-line math, always shown
        • Weekly check-inTen minutes a week keeps it honest
      • Features
        • Bills & paydaysEvery bill and payday on one calendar
        • GoalsSavings that fund themselves first
        • For couplesTwo logins, one number you both trust
        • SubscriptionsWhat you pay monthly, and what cancelling gives back
        • Calendar & heads-upsYour month at a glance, a heads-up before bills land
        • Net worth & payday nudgeThe whole picture, month by month
        • BudgetWhere the month’s money goes, month by month
      • Trust & help
        • Security & privacyJust your balances, optional two-step verification
        • Help centerSetup, the number, check-ins, FAQ
        • Open the web appSame account, any browser
    • Budget & Save
      • Budget & SaveOne number for what’s safe to spend before paydayBudgeting that starts from your balances, not a spreadsheet.Explore Budget & Save ›95 guides · 482 articles
      • Budgeting
        • Budgeting basics
        • Start a budget
        • Monthly budget
        • Budget methods
        • 50/30/20 budgeting
        • Zero-based budgeting
        • Budgeting mistakes
        • Budgeting tips
        • Budgeting tools
        • Couples budgeting
        • Family budgeting
        • Vacation budgeting
        • How to budget and save money
        • Common Budgeting Mistakes and How to Fix Them
        • 5 Steps to Stop Living Paycheck to Paycheck
        • Are You Living Paycheck to Paycheck?
        • How to Build a Simple Monthly Budget You’ll
        • Best Budgeting Apps Compared
        • Cut Recurring Costs
        • How to Track Every Dollar
        • 5 Easy Budgeting Apps You Need to Try
        • How to Cut Household Expenses Without Feeling
        • Budget Repair for Ages 18–28 with $30–50k Income
        • Beginner’s Guide to Creating a Monthly Budget
      • Saving
        • Savings
        • Savings goals
        • Savings plan
        • Savings buckets
        • Sinking funds
        • Cut expenses
        • Groceries savings
        • Smart saving strategies
        • Saving in a recession
        • Savings tips
        • Savvy saver
        • Maximize your savings
        • Debt-to-Income Ratio Calculator
        • Savings Calculator
        • Savings Goal Calculator to Help You Master Your
        • Monthly 50/30/20 Budget Calculator to Maximize
        • When to Use a High-Yield Savings Account vs
        • 14 Simple Ways to Cut Monthly Expenses
        • How to Set Up Savings Buckets in 20 Minutes
        • How to Create a Savings Plan
        • How to Build a 6-Month Savings Plan for Financial
        • How to Set Realistic Savings Goals and Hit Them
        • The 52-Week Savings Challenge
        • How to Maximize Savings
      • Emergency fund
        • Emergency fund
        • How much to save
        • Where to keep it
        • Rainy day fund
        • Emergency savings
        • Emergency buffer
        • Best emergency fund tips
        • Emergency Fund Calculator
        • Building a Rainy Day Fund
        • How to Calculate Your Emergency Fund
        • Sinking Funds vs. Emergency Fund
        • 5 Best High-Yield Savings Accounts for Emergency
        • Emergency Funds
        • Why an Emergency Fund Is Non-Negotiable
        • Why an Emergency Fund Is Crucial for Financial
        • Millions Can’t Cover an Emergency Expense. Here’s
        • 5 High-Liquidity Places to Park Your First $1,000
        • Saving Strategies for Emergency Funds and Retirement
        • Short-Term Savings Goals vs Emergency Fund
        • Emergency Fund Explained
        • Emergency Fund vs. Investing
        • Emergency Fund Guide
        • How Much Emergency Fund Do You Need?
        • Build Your Emergency Fund Fast
      • Money habits
        • Money management
        • Money management basics
        • Money habits
        • Money mindset
        • Money matters
        • Monthly financial reviews
        • Spend tracking
        • Smart spending
        • Cash flow
        • Net worth
        • Know your money
        • Financial literacy
        • Net Worth Calculator
        • How to Calculate Your True Debt-to-Income Ratio
        • What a Simple 7-Question Money Quiz Reveals About
        • Do Personal Money Management Tools Work?
        • The 3 Key Personal Finance Metrics Every Household
        • How to Build a Simple Monthly Financial Review Habit
        • Beginner’s Guide to Tracking Spending
        • Building a Savings Habit
        • What Is Financial Literacy?
        • Are Financial Advisor Fees Negotiable?
        • Psychology of Money Management
        • Should You Skip That Charitable Donation at the
      • Financial planning
        • Financial planning
        • Financial goals
        • Financial wellness
        • Financial freedom
        • Financial independence
        • Financial resilience
        • Financial self-assessment
        • Finance
        • Finance tips
        • Compound interest
        • Long-term wealth
        • Wealth building
        • Life-stage financial planning
        • Compound Interest Calculator
        • The Cashflow Calendar
        • What to Expect When Meeting with a Financial Advisor
        • How to Map Short, Medium, and Long Financial Goals
        • Financial Independence Roadmap
        • 50/30/20 Budget Rule
        • Personal Finance Mastery
        • How to Start a Budget
        • 5 Proven Saving Strategies to Reach Your Financial
        • Steps to Build Financial Resilience for Life Events
        • The Ultimate Guide to Financial Literacy
      • Income
        • Side hustles
        • Side hustle ideas
        • Side income
        • Extra income
        • Using extra income
        • Passive income
        • Gig economy
        • Gig work
        • Gig earnings
        • Freelance finance
        • Irregular income
        • Online income
        • Renting out assets
        • Selling unused items
        • Small business ideas
        • How to make money online
        • Salary
        • Selling Handmade Crafts Online
        • 10 Side Hustles You Can Start this Weekend
        • How to Start Freelance Writing
        • Budgeting for Irregular Income
        • Short-Term Income Boosters
        • Explore the Lucrative World of Delivery Driving
        • Building Your Credit as a Gig Worker
      • Family & life events
        • Family finance
        • Family costs
        • Family financial education
        • Teen money skills
        • New immigrant finance
        • Recovery after job loss
        • Healthcare costs
        • Healthcare savings
        • Cost of living
        • How to Rebuild Savings After a Job Loss
        • 529 Plans 101
        • How to Teach Financial Literacy to Teenagers
        • Real Cost of Raising Two Kids
        • Family Budgeting
        • Family of Four Budget
        • Winter Break Childcare
        • Thanksgiving Hosting on a Budget
        • Gifts for Kids on a Tight Pay Cycle
        • The Small Holiday Costs That Add Up
        • Holiday Gift Budget for Couples
        • Gift Cards After the Holidays
        • Holiday Returns and Refunds
        • Holiday Spending on a Pay Schedule
        • When Your Payday Moves Early
      • Big purchases & cars
        • Major money decisions
        • Major purchase planning
        • Major purchases
        • Buying a car
        • Buying a used car
        • Car buying
        • Moving expenses
        • How to Plan for a Major Purchase Without Going into
        • What to Check When Buying a Used Car
        • A Beginner’s Guide to Car Buying
        • Insurance in a Household Budget
        • Transportation Budget
        • First Paycheck, First Lease
        • Moving Without Draining Your Account
        • How Much Should You Keep for Car Repairs?
        • Saving for a Car Down Payment on a Paycheck Schedule
        • Moving In Together
        • Car Insurance Due in One Lump?
        • Should Your Car Count Toward Net Worth?
      • Money & the economy
        • The economy
        • Economic trends
        • Jobs report
        • U.S. financial system basics
        • Personal finance news
        • Free Interest Rate Calculator
        • Managing Your Savings During a Recession
        • Emergency Fund for a Recession
        • How to Navigate US Financial Systems as a New
        • How to Manage Your Savings During a Recession
        • Social Security COLA
        • Gig Economy Playbook
    • Debt & Credit
      • Debt & CreditPay it down, then make your score work for youPayoff plans that fit a pay cycle, and the credit moves that stick.Explore Debt & Credit ›36 guides · 109 articles
      • Pay off debt
        • Debt payoff
        • Debt-free journey
        • Credit card debt
        • Debt consolidation
        • HELOC payoff strategy
        • Debt as a single parent
        • Debt-Snowball vs. Debt-Avalanche
        • The Pros and Cons of Debt Consolidation
        • Debt Snowball vs Avalanche
        • Consolidating Debt
        • Saving for a Wedding Without Going Into Debt
        • Emergency Buffer While Paying Down Debt
        • How to Build a Realistic 6-Month Debt Payoff
        • Rolling Over a 401 to Pay Down Debt Without
        • Payoff Strategies for Single Parents with Multiple
        • How to Use Extra Cash to Crush Debt Fast
      • Loans
        • Student loans
        • Auto loans
        • Auto loan debt
        • Personal loans
        • Personal loan debt
        • Personal loan refinance
        • Refinancing a personal loan
        • Medical debt
        • How to Refinance a Personal Loan
        • Can You Refinance a Personal Loan?
        • What to Know Before Taking Out a Personal Loan
        • How to Deal With Personal Loan Debt
        • 5 Tips for Paying Off Your Auto Loan Early
        • Best Personal Loans
        • When to Refinance a Personal Loan
        • Student Loan Repayment Options
        • Medical Debt in America
        • Medical Debt Explained
        • Student Loans 101
        • Dealing With Student Loans
        • Auto Loans Explained
        • Budgeting with a High-Interest Personal Loan
        • Fast and Simple Auto Financing
        • Creating a Debt-Repayment Fund for Unexpected Loans
      • Credit score
        • Credit score
        • What credit scores mean
        • How credit scores are calculated
        • Checking your credit score
        • Improve your credit score
        • Build credit
        • Credit health
        • Credit reports
        • Credit basics
        • Credit for gig workers
        • How to Remove Negative Items from Your Credit Report
        • How to Build Credit
        • Understanding Credit Utilization
        • What Is Credit?
        • How to Build Credit From Scratch at Any Age and
        • How to Start or Rebuild Credit
        • Credit Utilization
        • How Long Do Negative Marks Stay on Your Credit
        • How to Read Your Credit Report and Dispute Errors
        • How to Check and Improve Your Credit Score
        • How Long Negative Items Stay on Your Credit Report
        • Credit Score 101
        • Dispute a Credit Report Item
        • Medical Bills on Your Credit Report
      • Credit cards
        • Credit cards
        • Credit cards for beginners
        • Credit card rewards
        • Balance transfer cards
        • Best Credit Cards to Build or Rebuild Credit and
        • Balance Transfers Explained
        • Best Starter Credit Cards for Building Credit
        • What to Do If Your Credit Card is Lost or Stolen
        • How to Pay Off Credit Card Debt Fast
        • How to Pick the Best Rewards Credit Card for
        • Best Practices for Responsible Credit Card Use
        • Using a Balance Transfer Credit Card to Pay Off
        • 10 Ways to Pay Off Credit Card Debt
        • Using a HELOC to Pay Off High-Interest Credit Card
        • Credit Card Hacks
        • Beginner’s Plan to Pay Off Credit Card Debt Fast
        • Financial Advice for Single Parents
        • How to Use Credit Cards Safely to Earn Rewards
        • Secured Credit Cards and Credit-Builder Loans
        • Credit Card Basics
        • Secured vs. Unsecured Credit Cards
        • AmEx and Fanatics to Partner on New Credit Card
        • American Express Gold Card Unveils New and Updated
        • 5 Things to Know About the Robinhood Platinum Card
      • Relief & protection
        • Debt relief
        • Bankruptcy
        • Negotiating with creditors
        • Predatory lenders
        • Wage garnishment
        • Credit freeze
        • Credit protection
        • Fraud awareness
        • Truth About Credit Freezes and When to Use One
        • How to Freeze and Unfreeze Your Credit with All 3
        • How to Negotiate with Creditors
        • Credit Freeze Guide
        • How to Avoid Predatory Lenders and Spot Scams
        • Personal Loan Debt Relief Options
        • How to Freeze and Thaw Your Credit Report
        • How to Freeze and Unfreeze Your Credit
        • When Bankruptcy Might be an Option
        • Budgeting Around Wage Garnishment
        • Identity Theft Checklist
        • Monitoring vs Freezes
    • Invest & Retire
      • Invest & RetireStart small, stay boring, retire on timeIndex funds, brokerages and retirement accounts without the jargon.Explore Invest & Retire ›54 guides · 168 articles
      • Start investing
        • Investing
        • How to start investing
        • Start investing with little money
        • Start investing with $100
        • Fear of investing
        • Brokerage setup
        • Investing risk
        • Investments
        • Investment Calculator
        • Why the Price-to-Earnings Ratio Matters
        • How to Start Investing with Little Money
        • Best Apps for Beginner Investors
        • Dollar-Cost Averaging Investing Strategy
        • Investing for Beginners
        • How to Build a Diversified Investment Portfolio
        • Investing Basics for Beginners
        • I’m 25. Here’s How I Got Started Investing
        • How to Start Investing While Paying Down Debt
        • How to Start Investing and Build Your Financial
        • How to Start Investing and Build Wealth
        • How to Start Investing if You’re Scared of the
      • Strategy
        • Investing strategy
        • Investment strategies
        • Your investing portfolio
        • Diversification
        • Diversifying your investments
        • Investing mistakes
        • Investing tips
        • Investment tips
        • Best investing tips
        • Risk management
        • Understanding Custodial Accounts
        • Recession-Proof Your Portfolio
        • How to Rebalance Your Portfolio
        • When to Use Dollar-Cost Averaging vs Lump Sum
        • 5 Simple Portfolios for New Investors
        • Diversification Strategies
        • Top 11 Investments to Consider
        • Asset Allocation for the Mid-Career Investor
        • How to Understand Investment Risk and Protect Your
        • 5 Smart Diversification Strategies to Spread Your
        • Behavioral Mistakes New Investors Make
        • Set-It-And-Forget It
        • Investing Mistakes New Investors Make and How to
        • Diversification Tips for High-Income Earners with
      • Stocks
        • Stock market
        • Stock market basics
        • How to start investing in stocks
        • Stock analysis
        • Stock trading
        • Stock trading strategies
        • S&P 500
        • Options trading
        • Margin trading
        • Short selling
        • How to Make Money in Stocks
        • How to Short a Stock in 5 Easy Steps
        • Bullish vs. Bearish
        • Top 8 Investment Account Options for Children
        • How to Read Stock Charts
        • How the Stock Market Works
        • Investing 101
        • How Stock Trading Works
        • Finding the Best Stocks to Weather Inflation
        • How to Start Investing in Stocks with Little Money
        • Beginner’s Guide to Analyzing Stocks in 5 Steps
        • How to Protect Your Investments in a Stock Market
        • Identify Recession-Resistant Stocks to Outperform
        • Margin Trading Explained
      • Funds & assets
        • Index funds
        • Index funds for beginners
        • Best S&P 500 index funds
        • ETFs
        • Dividend investing
        • Bonds
        • Bond investing
        • Crypto
        • Investment types
        • The 7 Best S&P 500 Index Funds
        • Index Funds vs. Actively Managed Funds
        • Beginner’s Guide to Index Funds
        • Choosing the Best S&P 500 Index Fund for Your
        • Mutual Funds vs. ETFs
        • The Best Low-Cost ETFs for Beginners to Buy Right
        • How to Start Investing in ETFs
        • Index Funds vs. ETFs
        • 7 Best Index Funds Beyond the S&P 500
        • How to Invest in Index Funds
        • Dividend Investing for Beginners
        • How Index Funds Track the S&P 500 Index
        • How to Start Investing in S&P 500 Index Funds
        • How Bond Index Funds Provide Stability and Income
        • Common Beginner Mistakes When Investing in ETFs
      • Platforms
        • Brokerages
        • Investment platforms
        • Stock brokerage platforms
        • Robo-advisors
        • Fidelity
        • Fidelity Go Review
        • Choosing between Vanguard and Fidelity for
        • Robinhood vs. E*TRADE
        • How to Manage Multiple Brokerage Accounts
        • Opening a Brokerage Account and Its Benefits
        • Fidelity vs. Schwab
        • Manage Multiple Brokerage Accounts
        • Robo-Advisors vs. Human Advisors
        • How Brokerage Fees and Commissions Affect Your
        • Robo-Advisors vs. Traditional Brokers
        • Maximizing Returns
        • Robo-Advisors vs DIY Investing
        • How to Choose the Best Brokerage Account for
      • Retirement
        • Retirement
        • Retirement planning
        • Retirement planning basics
        • Retirement saving
        • Retirement accounts
        • Retirement income
        • 401(k)
        • IRA
        • Social Security
        • Estate planning
        • Estate basics
        • Wealth transfer
        • Roth IRA vs. Traditional IRA
        • Target-Date Funds Explained and When to Use Them
        • Tax-Advantaged Accounts
        • How to Build a Simple, Low-Stress Retirement
        • Social Security Basics
        • How to Maximize Employer 401 Match
        • How to Choose the Right ETF for Your Goals
        • Stock Investing for Major Life Goals
        • Long-Term Care for Retirement
        • 401 Basics
        • Are You Making These Retirement Mistakes?
        • Retirement Planning Essentials
    • Home & Insurance
      • Home & InsuranceBuy, borrow and insure the biggest thing you ownFrom the first down payment to the policy that protects it.Explore Home & Insurance ›39 guides · 114 articles
      • Buying
        • Home buying
        • First-time home buyer
        • Home affordability
        • Home down payment
        • Down payment strategies
        • How Much House Can I Afford?
        • Buying a Fixer-Upper House?
        • What First-Time Home Buyers Need to Know About
        • Renting vs. Buying
        • How Much Home Can You Afford?
        • How to Save for a Home Down Payment Without
        • How Much Down Payment Do You Really Need to Buy a
        • Why Every First Time Home Buyer Should Attend a
        • Is Renting Better Than Buying?
        • Unlocking Down-Payment Assistance
        • Best Down Payment Strategies for First-Time Home
        • Understanding First-Time Home Buyer Loans and
        • 9 Steps to Successfully Buy a House
        • First-Time Home Buyers Top 21 Checklist
        • Saving for a Down Payment to Buy a House
        • From Pre‑Approval to Closing a New Home
      • Mortgage
        • Mortgage
        • Mortgage basics
        • Mortgage types
        • Adjustable-rate mortgages
        • Mortgage rates
        • Mortgage application
        • Mortgage payment
        • Mortgage payoff strategies
        • Mortgage refinance
        • Mortgage tips
        • How to Calculate the Debt-to-Income Ratio for a
        • Mortgage Amortization Calculator
        • How to Refinance a Mortgage with Low Credit
        • Refinance Your Mortgage
        • Free Mortgage Calculator To Estimate Your Monthly
        • First-Time Homebuyer Checklist
        • Fixed vs. Adjustable Mortgage
        • Leveraging Credit Score Improvements Before
        • Navigating Rising Mortgage Rates
        • Refinance, Rate Locks and More
        • Credit Scores to Closing Costs
        • The Mortgage Playbook
        • Understanding ARM Mortgage Outlook Homebuyers
        • Understanding Mortgages
      • Owning
        • Home ownership
        • Owning a home
        • Home equity
        • Home improvement
        • Home renovation
        • How to Cover the Cost of Emergency Home Fixes in 8
        • Hidden Costs of Home Ownership
      • Real estate
        • Real estate
        • Real estate investing
        • Getting started in real estate
        • Rental property
        • REITs
        • Evaluating Short-Term Rental Return on Investment
        • Investing in Real Estate Owned Properties
        • Analyzing Real Estate Investment Trusts for Passive
        • Calculating Rental Property Cash Flow Accurately
        • Building a Real Estate Investment Analysis
        • Evaluating a Multi-Family Real Estate Property
        • Evaluating Real Estate Crowdfunding Platforms
        • Estimating Real Estate Property Appreciation for
        • Starting a House Hacking Strategy
        • How to Use Real Estate Wholesaling Strategy for
        • Evaluating Fix-and-Flip Real Estate Opportunities
        • Using Leverage Wisely in Real Estate
        • Structuring a Real Estate Portfolio for Tax
        • Using a 1031 Exchange to Defer Capital Gains Taxes
        • Using Real Estate Syndications to Access Larger
      • Insurance
        • Home insurance
        • Best home insurance
        • Coverage basics
        • Home insurance deductibles
        • Home insurance rates
        • Home insurance claims
        • Policy add-ons
        • Home insurance tips
        • Best home insurance companies
        • How to choose a policy
        • Compare home insurance quotes
        • Instant home insurance quotes
        • Car insurance
        • Life insurance
        • Top 6 Home Insurance Companies
        • Understanding Your Home Insurance Deductible
        • Compare Home and Insurance Quotes
        • Get Your Free Home Insurance Policy Quotes Today
        • The Ultimate Guide to Homeowners Insurance
        • How to Get the Best Home Insurance Policy Quotes
        • Home Insurance Premiums Explained
        • How to Compare Term vs. Whole Life Insurance for
        • Instant Insurance Quotes for Your Home
        • How to Estimate True Homeownership Costs
    • Taxes
      • TaxesKnow what lowers your bill before April doesDeductions, credits and the forms behind them, in the order you meet them.Explore Taxes ›25 guides · 53 articles
      • Filing
        • How to file taxes
        • Tax filing basics
        • Your tax bill
        • Tax refunds
        • Adjusted gross income
        • Adjusted Gross Income Explained
        • Tax Prep Checklist
        • Free File Tax Program Remains Woefully Underused
        • How to File a Tax Extension Online
        • Tax Refund Loan
        • Georgia State Income Tax
        • 6 Smart Ways to Cut Taxes in Retirement and Keep
        • Handling Back Taxes
      • Deductions & credits
        • Deductions
        • Tax deductions, itemized
        • Tax credits
        • Deductions vs credits
        • Saver’s credit
        • Claiming Moving Expense Deductions
        • Understanding Tax Credits vs. Deductions
        • Tax Filing for Beginners
        • How to Lower Your Tax Bill
        • Tax Deductions 101
        • Tax Credit vs. Tax Deduction
        • Earned Income Tax Credit
        • Sales Tax Deduction
        • Mortgage Interest Tax Deduction
        • Itemized Deductions
        • Popular Tax Credits Explained
        • Popular Tax Deductions and Tax Breaks
        • Qualifying for and Claiming the Saver’s Credit
      • Family
        • Child tax planning
        • Child tax credit
        • Child care credit
        • Dependent care credit
        • Maximizing the Child and Dependent Care Credit
        • The Child Tax Credit
        • Child Tax Credit Explained
        • Child and Dependent Care Credit Explained
      • Situations
        • Freelance taxes
        • Gig work taxes
        • Investment taxes
        • Capital gains taxes
        • Retirement taxes
        • HSA
        • Health savings accounts
        • How to File Taxes if You’re Freelancing
        • Capital Gains Tax Rates
        • Understanding Capital Gains Taxes
        • Contributing to HSA
        • How Side-Gig Income Affects Your Taxes
        • Saver’s Credit Explained
        • Tax Strategies for Side Hustles and Gig Working
        • What to Consider Before Moving to a State With No
        • Massachusetts State Income Tax
        • How to Use Health Savings Accounts to Lower Your
      • Planning
        • Tax planning & strategies
        • Tax strategy
        • Tax savings
        • Tax tips
        • Tax Mistakes that Trigger Audits
        • Tax-Advantaged Accounts for Education
        • Wealth Transfer
        • What to Know About Changing Your Tax Withholding
        • How to Choose the Right Tax Software for Your Tax
        • Tax Basics for New Investors
        • How Federal Tax Brackets and Rates Work
        • California State Income Tax Guide
        • Colorado State Income Tax
        • What Is a Marginal Tax Rate?
        • Illinois State Income Tax
        • Year-End Tax Checklist
    • Banking
      • Start hereBanking, without the fees you forgot you payChecking, savings and CDs, explained the way you’d tell a friend.Explore Banking ›14 guides · 215 articles
      • Basics
        • Banking basics
        • Open your first account
        • How to choose a bank
        • Compare banks
        • Bank fees
        • Best Online Bank Accounts
        • How to Open Your First Bank Account
        • Wire Transfer Fees
        • Returned Deposit Fees Explained
        • Open a Bank Account Online
        • Chase Banking
        • How to Avoid Bank Fees
        • Online Bank vs. Brick-and-Mortar
        • Online vs. Traditional Banking
        • Truist Banking Review
        • Switching Banks?
        • Chase vs. Wells Fargo vs. Capital One
        • Credit One Banking
        • Can a Bank Reopen a Closed Account?
        • How to Read Your Bank Statement Like a Pro
        • Can Someone Steal Money With Your Routing Number?
        • How to Setup a Personal Bank Account Online in 5
        • PNC Banking
        • Regions Banking
      • Checking & debit
        • Checking accounts
        • Best checking accounts
        • Debit cards
        • Best Checking Accounts with No Monthly Fees
        • Best Checking Accounts for High-Interest Earnings
        • Understanding the Time It Takes for a Check to Clear
        • Beginner’s Guide to Overdraft Protection
        • How to Mobile Deposit Checks for Beginners
        • Best Checking Accounts with Overdraft Protection
        • Maximizing Rewards
        • When to Stop a Check Payment and the Fees Involved
        • Second Chance Checking vs. Regular Accounts
        • Where to Buy Cheap and Affordable Personal Checks
        • Best Checking Accounts for Joint Accounts
        • How to Choose the Right Checking Account for Your
        • Cashing Checks at Any Bank
        • Best Checking Accounts with Excellent Mobile
        • Two Checking Accounts at One Bank
        • How Much Cash Should You Keep in Each Checking and
        • Begin Anew With Second Chance Checking in the U.S
        • Switching Checking Accounts
        • Overdraft Fees
        • Online vs. Traditional Banks
        • Missing Debit Card?
      • Savings & CDs
        • Savings accounts
        • CD Calculator
        • Understanding the Basics of Savings Account Minimum
        • Money Market Account vs. Savings Account
        • Savings Accounts vs. CDs
        • 5 Common Savings Account Fees You Should Avoid
        • High-Yield vs. Traditional Savings
        • How to Choose the Best High-Yield Savings Account
        • Learn How to Open a Savings Account in Simple Steps
        • Emergency Fund Essentials
        • Maximizing Interest
        • How to Calculate Interest Earnings in Your Savings
        • High-Yield Savings Accounts Explained
        • Determining the Right Number of Savings Accounts
        • How to Use a Money Market Account vs. a Savings
        • Savings Account Hacks for Travel Goals
        • When to Save and When to Invest
        • What is a CD and When It Makes Sense for Your
        • From CDs to Treasurys, What Happens to Yields When
        • CD and HELOC Fees
        • PNC High-Yield Savings Account Interest Rate
        • How I Chased Savings Rates at the Same Bank
        • Bread Savings CD Rates
      • Deposits & joint accounts
        • Joint bank accounts
        • Chase Joint Bank Accounts Review
        • Discover Joint Bank Accounts Review
        • How to Set Up Direct Deposit in Minutes
        • Bank of America Joint Accounts
        • Capital One Joint Bank Accounts
        • Beginner’s Guide to Early Direct Deposit with Banks
        • Wells Fargo Joint Bank Accounts
        • When to Open a Joint Bank Account
        • How to Open a Joint Bank Account Online
        • Regions Joint Account
        • TD Bank Joint Account
        • What Time Does Citizens Direct Deposit Hit?
        • What Time Does Netspend Direct Deposit Hit?
        • How to Set Up Direct Deposit With Chase
        • How to Set Up Direct Deposit on Cash App
        • How to Set Up Direct Deposit for Social Security
        • How to Set Up Direct Deposit Without an Employer
        • How Long Does Direct Deposit Take to Set Up?
        • How to Set Up Direct Deposit
        • How to Set Up Chime Direct Deposit, With or Without
        • Truist Joint Account
        • What Time Does Truist Direct Deposit Hit?
        • Wells Fargo Joint Account
      • Smarter & safer
        • Digital banking
        • Financial safety
        • Banking how-to guides
        • Banking tips
        • Best Ways for Managing Multiple Bank Accounts
        • Stay Safe from Check Scams
        • How to Set Up Bank Account Alerts and Why They
        • How Many Savings Accounts Should You Have?
        • 5 Steps to Cancel a Lost Check Quickly and Easily
        • Cashier’s Check vs. Personal Check
        • Writing a Check From a Closed Account
        • Fake Check Scams Explained
        • How Many Checking Accounts Should You Have?
        • How to Build a Relationship with Your Bank for
        • Check Washing Scams
        • Bank Bonuses Funded My Christmas Shopping This Year
        • If the CFPB Can’t Help You, Here’s How You Can Help
        • How to Secure Your Digital Banking and Finances
    • Sign In
    • Sign Up
    Amppfy
    Home » Personal Finance » How to Navigate US Financial Systems as a New Immigrant
    Personal Finance

    How to Navigate US Financial Systems as a New Immigrant

    Thomas T.By Thomas T.March 22, 2026Updated:March 22, 202613 Mins Read
    Facebook Twitter LinkedIn Email Copy Link
    How to Navigate US Financial Systems as a New Immigrant
    Share
    Facebook Twitter LinkedIn Email Copy Link

    Moving to the United States with dreams of building a new life is exhilarating, but the financial system here can feel like learning a foreign language on top of the one you’re already mastering.

    I’ve watched countless immigrants struggle not because they lacked intelligence or work ethic, but because nobody explained the unwritten rules: why a credit score matters more than your savings account balance, how a single missed payment can haunt you for seven years, or why the IRS expects you to file taxes even before you have a Social Security Number.

    Financial literacy for new immigrants means understanding these US systems that operate differently from almost anywhere else in the world. The good news? Once you understand the logic behind American finance, you can use it to your advantage faster than most native-born citizens. This isn’t about memorizing rules; it’s about understanding a system designed around credit, taxes, and documentation so you can build wealth instead of just surviving. Let me walk you through exactly what I wish someone had told me when I first arrived.

    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store Get it on Google Play

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it

    Establishing Your First US Banking Relationship

    Opening a bank account should be your first financial priority after securing housing. Without one, you’ll lose money to check-cashing services, struggle to receive direct deposits, and have no foundation for building credit. The American banking system offers more options than most countries, but each comes with trade-offs worth understanding.

    Choosing Between National Banks, Credit Unions, and Online Platforms

    National banks like Chase, Bank of America, and Wells Fargo offer the widest ATM networks and branch access, which matters when you’re still learning the system and might need in-person help. Their downsides include higher fees and stricter requirements for new accounts. Many charge $12-15 monthly unless you maintain minimum balances of $1,500 or more.

    Credit unions operate as member-owned cooperatives, typically offering lower fees and better interest rates. The catch: membership requirements vary widely. Some accept anyone living in a certain area, while others require employer or organizational affiliations. If you qualify, credit unions often show more flexibility with non-traditional documentation.

    Online banks like Ally, Chime, and Marcus have disrupted the industry with no-fee checking accounts and savings rates around 4-5% APY compared to the national average of 0.39% at traditional banks. The trade-off is no physical branches, which can complicate cash deposits and in-person problem resolution.

    My recommendation for most new immigrants: start with a national bank for convenience and reliability, then open a high-yield online savings account once you’re comfortable. This combination gives you physical access when needed while maximizing your interest earnings.

    Required Documentation for Non-Citizens and Visa Holders

    Banks legally require two things: proof of identity and proof of address. What counts as acceptable varies significantly between institutions.

    For identity, most banks accept:

    • Valid foreign passport
    • US visa or I-94 arrival record
    • Employment Authorization Document (EAD)
    • State-issued ID or driver’s license (if you have one)

    For address verification, bring at least two of these:

    • Lease agreement or utility bill
    • Bank statement from your home country
    • Letter from your employer
    • Government correspondence

    Here’s what nobody tells you: different branches of the same bank may interpret requirements differently. If one branch refuses you, try another location or call the bank’s new accounts department directly. Some banks, including Chase and Bank of America, have specific programs for newcomers and may require only a passport and visa.

    Bring originals, not copies. Arrive with more documentation than you think necessary. And if you’re denied, ask specifically why: sometimes it’s a fixable issue like needing a different document type.

    Understanding and Building Your US Credit Score

    Your credit score will determine more about your financial life in America than your actual income or savings. Landlords check it before renting to you. Employers review it for certain jobs. Insurance companies use it to set your premiums. Understanding this system is essential for navigating US financial systems successfully.

    The Importance of FICO Scores and Credit Bureaus

    Three companies track your credit behavior: Equifax, Experian, and TransUnion. They collect data on your payment history, credit utilization, account age, credit mix, and new credit inquiries. FICO, a separate company, uses this data to calculate your score on a 300-850 scale.

    The scoring breakdown works roughly like this:

    • Payment history: 35%
    • Credit utilization: 30%
    • Length of credit history: 15%
    • Credit mix: 10%
    • New credit inquiries: 10%

    A score above 740 gets you the best rates on everything. Below 670, you’ll face higher interest rates or outright denials. Below 580, most traditional lenders won’t work with you.

    The frustrating reality for immigrants: you start with no score at all, which many systems treat as worse than a bad score. You’re not starting at zero; you’re starting invisible.

    Strategies for Building Credit Without a Social Security Number

    You can build credit before receiving a Social Security Number using an Individual Taxpayer Identification Number (ITIN). Several credit card issuers accept ITIN applications, though the list changes frequently.

    Becoming an authorized user on someone else’s credit card provides another path. If a family member or trusted friend with good credit adds you to their account, their positive payment history can appear on your credit report. You don’t even need to use the card: the account history alone helps.

    Some landlords and utility companies report payments to credit bureaus, though this isn’t universal. Services like Experian Boost allow you to add utility and subscription payments to your Experian credit file, potentially increasing your score immediately.

    Secured Credit Cards and Credit-Builder Loans

    Secured credit cards require a cash deposit that becomes your credit limit. Deposit $500, get a $500 limit. The bank holds your money as collateral, reducing their risk enough to approve applicants with no credit history.

    Look for secured cards that:

    • Report to all three credit bureaus
    • Offer a path to upgrade to an unsecured card
    • Charge no annual fee or a minimal one
    • Return your deposit when you upgrade or close the account

    Credit-builder loans work in reverse. The lender holds the loan amount in a savings account while you make monthly payments. Once you’ve paid in full, you receive the money plus any interest earned. Your payment history gets reported to credit bureaus throughout.

    Both options cost money through fees or interest, but they’re investments in your financial future. A strong credit score can save you tens of thousands of dollars over your lifetime through better loan rates.

    Managing Taxes and Legal Financial Compliance

    The US tax system operates on voluntary compliance, meaning you’re responsible for calculating and paying what you owe. The IRS doesn’t send you a bill: they expect you to figure it out yourself or hire someone who can.

    Applying for an Individual Taxpayer Identification Number (ITIN)

    If you earn income in the US but don’t qualify for a Social Security Number, you need an ITIN to file taxes legally. The IRS issues ITINs regardless of immigration status because they want tax revenue from everyone.

    The application process requires Form W-7, a completed tax return, and proof of identity and foreign status. You can mail original documents to the IRS, use a Certified Acceptance Agent who can verify documents locally, or visit an IRS Taxpayer Assistance Center in person.

    Processing takes 7-11 weeks during normal periods, longer during tax season. Apply early if possible. Your ITIN expires if unused on a tax return for three consecutive years, so file annually even if you owe nothing.

    Understanding Federal, State, and FICA Tax Obligations

    Your paycheck will show multiple deductions that can feel shocking if you’re used to different tax structures.

    Federal income tax ranges from 10% to 37% depending on your income bracket. Most workers fall in the 12-22% range. This money funds national programs and defense.

    State income tax varies dramatically. Texas, Florida, and Washington charge nothing. California tops out at 13.3%. Your state’s rate significantly impacts your take-home pay.

    FICA taxes fund Social Security and Medicare. You pay 6.2% for Social Security on income up to $168,600 in 2024, plus 1.45% for Medicare on all income. Your employer matches these amounts.

    Self-employed individuals pay both halves of FICA, totaling 15.3% before income tax. This catches many freelancers and gig workers off guard.

    Track your income and deductions throughout the year. The IRS offers free filing options for incomes below $79,000. For complex situations involving foreign income or assets, professional help is worth the cost.

    Navigating Housing and Large Purchases

    Major purchases in America depend heavily on credit history, creating a chicken-and-egg problem for newcomers. You need credit to get housing, but you need stable housing to build credit.

    Renting an Apartment Without a US Credit History

    Landlords use credit checks to predict whether you’ll pay rent reliably. Without US credit, you’ll need alternative proof of financial responsibility.

    Strategies that work:

    1. Offer larger security deposits. Two or three months’ rent upfront demonstrates financial stability and reduces landlord risk.
    2. Provide bank statements showing consistent savings. Six months of statements with healthy balances prove you can cover rent.
    3. Show proof of income. Employment verification letters and pay stubs matter more than credit scores to some landlords.
    4. Get a co-signer. Someone with established US credit who agrees to cover rent if you can’t.
    5. Target individual landlords over large property management companies. Individual owners have more flexibility to evaluate applicants holistically.
    6. Consider immigrant-friendly housing services. Some organizations specifically help newcomers find housing without traditional credit requirements.

    Expect to pay more upfront or accept less desirable units initially. This improves quickly as you build credit history over 6-12 months.

    Qualifying for Auto Loans and Mortgages as a Newcomer

    Auto loans become accessible faster than mortgages. Some dealerships work with newcomers, though interest rates will be higher without credit history. Expect rates of 10-15% compared to 6-8% for buyers with established credit.

    Strategies for better auto loan terms:

    • Make larger down payments (20%+ reduces lender risk)
    • Choose less expensive vehicles
    • Get pre-approved through credit unions before visiting dealerships
    • Bring documentation of stable employment and income

    Mortgages require more patience. Most lenders want to see two years of US employment history and established credit. Some programs exist for newcomers, but they typically require 20-25% down payments and charge higher rates.

    Foreign national mortgage programs accept applicants without Social Security Numbers but require substantial down payments, often 30% or more. Interest rates run 1-2 percentage points higher than conventional loans.

    Consider renting for your first 2-3 years while building credit and savings. The mortgage terms available to you after establishing US credit history will save far more than any equity you might build during that period.

    Protecting Your Assets with Insurance and Retirement Planning

    Insurance in America works differently than in countries with stronger social safety nets. Without proper coverage, a single medical emergency or car accident can destroy years of financial progress.

    The Essentials of US Health and Auto Insurance

    Health insurance is non-negotiable. A hospital stay can cost $10,000-50,000 without insurance. Emergency surgery might exceed $100,000. These aren’t exaggerations: they’re typical bills.

    If your employer offers health insurance, take it. Employer-sponsored plans are typically the best value because employers pay 70-80% of premiums. Review options during open enrollment each fall.

    Without employer coverage, explore Healthcare.gov marketplace plans. Subsidies reduce costs significantly for incomes up to 400% of the federal poverty level. Some states offer additional programs for immigrants regardless of status.

    Auto insurance is legally required in most states. Minimum coverage satisfies legal requirements but may not protect you adequately. Consider liability limits of at least $100,000 per person and $300,000 per accident, plus uninsured motorist coverage.

    Your driving record from your home country may help reduce premiums. Ask insurers if they accept international driving history.

    Introduction to 401(k) Plans and IRAs

    Retirement accounts offer tax advantages that accelerate wealth building. Starting early matters enormously due to compound interest.

    A 401(k) through your employer allows pre-tax contributions up to $23,000 in 2024. Many employers match contributions up to a certain percentage: this is free money. A 50% match on 6% of your salary means contributing 6% effectively becomes 9%.

    If your employer offers matching, contribute at least enough to get the full match. The math is simple: a 50% match equals a 50% instant return on your investment.

    Individual Retirement Accounts (IRAs) allow $7,000 in annual contributions. Traditional IRAs offer tax deductions now with taxes due at withdrawal. Roth IRAs use after-tax money but grow and withdraw tax-free.

    For most immigrants in their earning years, Roth IRAs make sense. You’re likely in a lower tax bracket now than you will be later, so paying taxes now at lower rates beats paying later at higher rates.

    Long-Term Financial Integration and Growth

    Building lasting wealth in America requires thinking beyond immediate needs. The immigrants who thrive financially aren’t necessarily those who earn the most: they’re those who understand how different financial systems connect.

    Your credit score, tax compliance, insurance coverage, and retirement savings work together. Strong credit reduces borrowing costs across your lifetime. Proper tax filing prevents legal problems and enables future opportunities like citizenship. Adequate insurance protects everything you build. Retirement accounts harness compound interest over decades.

    Set quarterly reviews to assess your progress. Check your credit reports at AnnualCreditReport.com for free. Review your tax withholding when circumstances change. Evaluate insurance coverage annually. Increase retirement contributions with each raise.

    The financial literacy you’re building now for navigating US systems will serve you for decades. Most native-born Americans never learn these fundamentals systematically: they absorb them haphazardly or learn through expensive mistakes. Your intentional approach gives you an advantage.

    Frequently Asked Questions

    Can I open a US bank account without a Social Security Number?
    Yes. Most major banks accept an ITIN or even just a foreign passport and visa for account opening. Requirements vary by institution, so call ahead or try multiple branches. Credit unions often show more flexibility than large national banks.

    How long does it take to build a credit score from nothing?
    You can establish a FICO score within 6 months of opening your first credit account, assuming that account reports to credit bureaus. Building a good score (700+) typically takes 12-24 months of consistent on-time payments and responsible credit use.

    Do I need to file US taxes if I only worked part of the year?
    Generally yes, if your income exceeds filing thresholds. For 2024, single filers under 65 must file if they earned more than $14,600. Even below this threshold, filing may benefit you through refundable credits. Consult a tax professional for situations involving foreign income.

    What happens to my 401(k) if I leave the United States?
    Your 401(k) remains yours regardless of where you live. You can leave it with your former employer, roll it into an IRA, or cash it out (with penalties and taxes). Withdrawal rules and tax implications depend on your residency status and any tax treaties between the US and your destination country.

    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store Get it on Google Play

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it
    Banking Tips Financial Literacy Money Management
    Share. Facebook Twitter LinkedIn Email Copy Link
    Previous ArticleUnderstanding Crypto: A Guide to Digital Asset Literacy 2026
    Next Article Free Mississippi Mortgage Calculator
    Thomas T.

    Thomas is a Personal Finance Writer and Financial Content Strategist with over 10 years of experience helping individuals make smarter financial decisions. He specializes in topics such as budgeting, debt management, saving strategies, and financial behavior, translating complex financial concepts into clear, actionable guidance. His work focuses on empowering readers to build sustainable financial habits and confidently navigate their financial lives, combining data-driven insights with practical, real-world advice.

    More Like This

    What Time Does Citizens Direct Deposit Hit? Early Pay and Posting Times

    By Thomas T.October 19, 2026

    What Time Does Netspend Direct Deposit Hit? Early Pay on a Prepaid Card

    By Thomas T.October 19, 2026

    How to Set Up Direct Deposit With Chase

    By Thomas T.October 19, 2026
    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number.

    Download on the App Store Get it on Google Play

    Prefer the web? Sign up free ›

    Amppfy dashboard on an iPhone showing the Safe to Spend number with the math under it
    Helpful Resources

    What Time Does Citizens Direct Deposit Hit? Early Pay and Posting Times

    October 19, 2026

    What Time Does Netspend Direct Deposit Hit? Early Pay on a Prepaid Card

    October 19, 2026

    How to Set Up Direct Deposit With Chase

    October 19, 2026

    How to Set Up Chime Direct Deposit, With or Without an Employer

    October 19, 2026

    Financial Clarity. Everyday Confidence.

    Facebook X (Twitter) YouTube TikTok
    Calculators

    Emergency Fund Calculator

    Compound Interest Calculator

    Interest Rate Calculator

    Net Worth Calculator

    Mortgage Calculator

    How Much Home Can I Afford

    Debt-to-Income Ratio Calculator

    Cost of Living Calculator

    Savings Calculator

    Savings Goal Calculator

    Monthly Budget Calculator

    Latest Resources

    Social Security COLA 2027: What the 3.6% Raise Means for Your Monthly Plan

    November 6, 2026

    Best Free Budget Apps in 2026: iPhone, Android, and Web

    November 6, 2026

    Federal Pay Period Calendar for 2027: Every Pay Period and Payday

    November 6, 2026

    Money Manager Expense & Budget App: Price, Ads, and Simpler Alternatives in 2026

    November 6, 2026
    About & Legal

    About Amppfy

    Documentation

    Advertise with Amppfy

    Editorial Policy

    EULA

    Terms of Use

    Acceptable Use Policy

    Privacy Policy

    Cookie Policy

    Disclaimer

    Do Not Sell or Share My Personal Information

    Acceptable Use Policy

    Disclaimer: Amppfy is committed to keeping its information transparent, accurate, and up-to-date. The information on Amppfy is provided for educational and informational purposes only and should NOT be considered financial, investment, tax, or legal advice. You should consult a qualified financial professional before making any financial decisions. This information may differ from what you find on the specific product or service provider’s website. All information, content, software, tools, products, or services on Amppfy are presented without warranty or guarantee. Please review the specific provider’s terms and conditions when evaluating products or services. By accessing Amppfy or using our AI generator tools, you acknowledge that you have read, understood, and agreed to our EULA, Terms of Use, Acceptable Use Policy, Privacy Policy, Cookie Policy, and Disclaimer. Amppfy.com uses cookies. For more information, visit Amppfy’s Cookie Policy. Amppfy may be compensated through third-party advertisers and affiliates. For more information, visit Amppfy’s Disclaimer.

    Copyright© 2026 Amppfy | All Rights Reserved

    Type above and press Enter to search. Press Esc to cancel.

    Advertiser Disclosure: Products may include affiliate links related to financial products or services. We may earn a commission at no additional cost to you. Our content remains independent and focused on helping you make informed financial decisions.
    Fact Checked
    Financial Disclaimer

    This content is for informational and educational purposes only and should not be considered financial advice. Personal finance decisions—including budgeting, saving, investing, credit, mortgages, taxes, and debt management—depend on your individual circumstances. Always consult a qualified financial professional before making financial decisions.

    Editorial Standards and Content Integrity

    Our editorial process ensures accuracy, clarity, and trust across all personal finance topics, including budgeting, saving, investing, and debt management. Content is created using credible sources such as government agencies, academic research, and established financial institutions, and may incorporate insights from industry experts when relevant. Each article is reviewed for accuracy, timeliness, and relevance before publication and updated as needed to reflect changes in financial guidelines and best practices, with the goal of providing clear, evidence-based information to help readers make informed financial decisions.

    Learn more about our editorial policy and guideline.
    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Get the app on iPhone or Android and enter your balances, bills, and payday. About ten minutes to one clear number: what’s safe to spend before payday.Your balances, bills, and payday. Ten minutes to one clear number. Learn more ›

    Download on the App Store Get it on Google Play
    Scan with your phone to get the app

    Free  ·  No credit card  ·  Just your balances

    Prefer the web? Sign up free ›

    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Enter your balances, bills, and payday once. About ten minutes to one clear number, with the math shown under it.

    Download on the App Store Get it on Google Play
    Scan with your phone to get the app

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances