
If you share rent, groceries, or a car payment with someone, you’ve probably wondered whether a shared account would make life simpler. At Regions, the answer depends on one practical question: are you starting fresh, or adding someone to an account you already have?
The two paths look similar from the outside. They aren’t. One can happen from your couch. The other needs both of you at a branch, together, with ID in hand.
This guide walks through how a Regions joint account works, what each owner can do with it, and what it costs as of October 2026. It also covers how couples tend to use one alongside their own private accounts. Everything about the bank comes from Regions’ own published pages. Where Regions doesn’t publish a detail, you’ll see that said plainly instead of a guess.
Grab a coffee. This takes about ten minutes to read, and maybe less to act on.
Joint accounts at Regions: what they are and who can be on one
Regions describes it simply: joint accounts “allow two or more people to pull their funds together.” That’s the whole idea. One account, more than one owner.
Ownership is the key word. Per Regions’ joint accounts page, each owner can deposit, withdraw, or use a debit card without permission from the other owner(s), as of October 2026. Nobody needs a co-signature for a grocery run.
Who can be on one:
- Two or more people. Regions says “two or more,” so it isn’t limited to couples.
- Adults, if you open online. Both the primary and joint holder must be the age of majority in your state to open online, as of October 2026.
- Owners, not just signers. An authorized signer is a different role, and it isn’t ownership. More on that below.
Regions offers joint versions of both checking and savings. So you can share a bills account, a savings goal, or both.
Add a partner to an existing account vs open a new joint account
This is the fork in the road. Pick the wrong branch and you’ll waste a trip.
Opening a new joint account
A new joint checking or savings account “can be opened at a branch or online,” per Regions’ joint accounts page, as of October 2026. If you’re both of age, online works fine.
Adding a partner to an account you already have
This one is stricter. Regions states: “If you already have a Regions checking or savings account and would like to add a joint owner, please visit a Regions branch with the joint owner.” Its May 4, 2026 guide to opening a joint checking account explains why. Adding a person “requires an in branch visit” because it changes legal ownership of the account, as of October 2026.
Think of it like adding a name to a house deed. You can’t do it by text. Both people show up and sign.
Which is better? If your current account has years of autopays set up, adding a partner saves you moving everything. If you’d rather keep your account private and share only bills, a fresh joint account is cleaner.
Step by step
Gather documents first. It’s the slowest part, and it’s the same list for both paths.
What Regions asks for, as of October 2026, per its joint accounts page and joint checking guide:
| Item | Who needs it |
|---|---|
| SSN or taxpayer ID | Both owners |
| Photo ID | Both owners |
| Secondary ID | Possibly, both owners |
| Birth dates | Both owners |
| Contact information | Both owners |
| Initial deposit | For the account |
Then follow the path that fits:
- Decide: new account or add to existing. This sets everything else.
- New account, both of age: apply online or at a branch.
- Adding to an existing account: book or walk into a branch, together.
- Bring the documents above for each person.
- Make the initial deposit. See the next fee section for minimums.
- Order debit cards for each owner, if you want them.
Regions doesn’t publish how long the branch visit takes. Call ahead or check your local branch if timing matters.
What each of you can see, move, and close
Equal access is the defining feature. Regions’ joint checking guide says all owners have equal access, as of October 2026. Either of you can deposit, withdraw, or swipe a debit card without asking first.
Equal access comes with equal responsibility. The same guide states that owners share liability for fees and overdrafts, as of October 2026. If one person overdraws, the overdraft belongs to the account, and so to both of you.
That’s not a reason to panic. It’s a reason to agree on a few rules before the first deposit:
- A spending line. For example, anything over $200 gets a quick text first.
- A bills list. Write down which charges come out of this account.
- A cushion. Keep a small buffer, say $300, that neither of you counts as spendable.
An authorized signer is different. A signer can be allowed to transact but is not an owner. If you want someone to help with bills without making them a legal co-owner, ask Regions about the signer role.
Regions doesn’t publish its specific rules for closing a joint account or removing an owner on these pages. Ask at a branch before you need to.
Fees, minimums, and waivers
The numbers are short. Here’s what Regions’ checking page lists, as of October 2026:
| Line | What it is |
|---|---|
| LifeGreen Checking monthly fee | “$0 or $8 or $11,” depending on how it’s avoided (as of October 2026) |
| Minimum opening deposit, Regions checking | $25 (as of October 2026) |
| Minimum opening deposit, Regions Now Checking | $10 (as of October 2026) |
The waiver details live on Regions’ LifeGreen page. Regions lists the specific ways to reach $0 there, and they’re worth reading directly rather than secondhand. This guide won’t paraphrase them, because small wording differences matter with fees.
Now the arithmetic. Say you land on the $11 tier and never change anything. That’s $11 × 12 = $132 a year, as of October 2026. On the $8 tier, it’s $8 × 12 = $96. At $0, it’s nothing.
So the gap between the top tier and a full waiver is $132 a year. That’s a real number, but it’s also a solvable one. Read the waiver list once, pick the condition you already meet, and set it up.
Joint, separate, or both: how couples actually use it
Most couples don’t go all in on one model. They pick a mix that matches how they already live.
Fully joint works when you have similar pay and similar habits. Everything goes into one pot. It’s simple to see, and harder to keep private.
Fully separate works when one partner had debt, or you married later with established finances. You split bills by Venmo or transfer. It’s private, but someone always has to do the splitting.
The hybrid is a common middle ground. Each of you keeps a private account. A shared Regions account handles rent, utilities, and groceries. Each payday, you both transfer a set amount in. If you want help picking that amount, see how much to put in a bills-only joint account each payday.
Here’s a quick example. Shared bills total $3,000 a month. One partner earns 60% of household income, the other 40%. Proportional split: $1,800 and $1,200. Clean, fair, done.
For a full comparison of each model, read bank accounts for couples: joint, separate, or both. If you’re weighing Regions against an online-only bank, here’s a rundown of online banks that offer joint accounts. And if your pay lands at Regions, timing matters too: see when Regions direct deposit hits, including Early Pay.
One number for two people
A shared account solves where the money sits. It doesn’t answer the question you both ask on a Thursday: can we spend this, or not?
Your Regions balance shows what’s there right now. It doesn’t subtract the rent due Monday or the car insurance due before payday. Two people glancing at one balance can each reach a different answer.
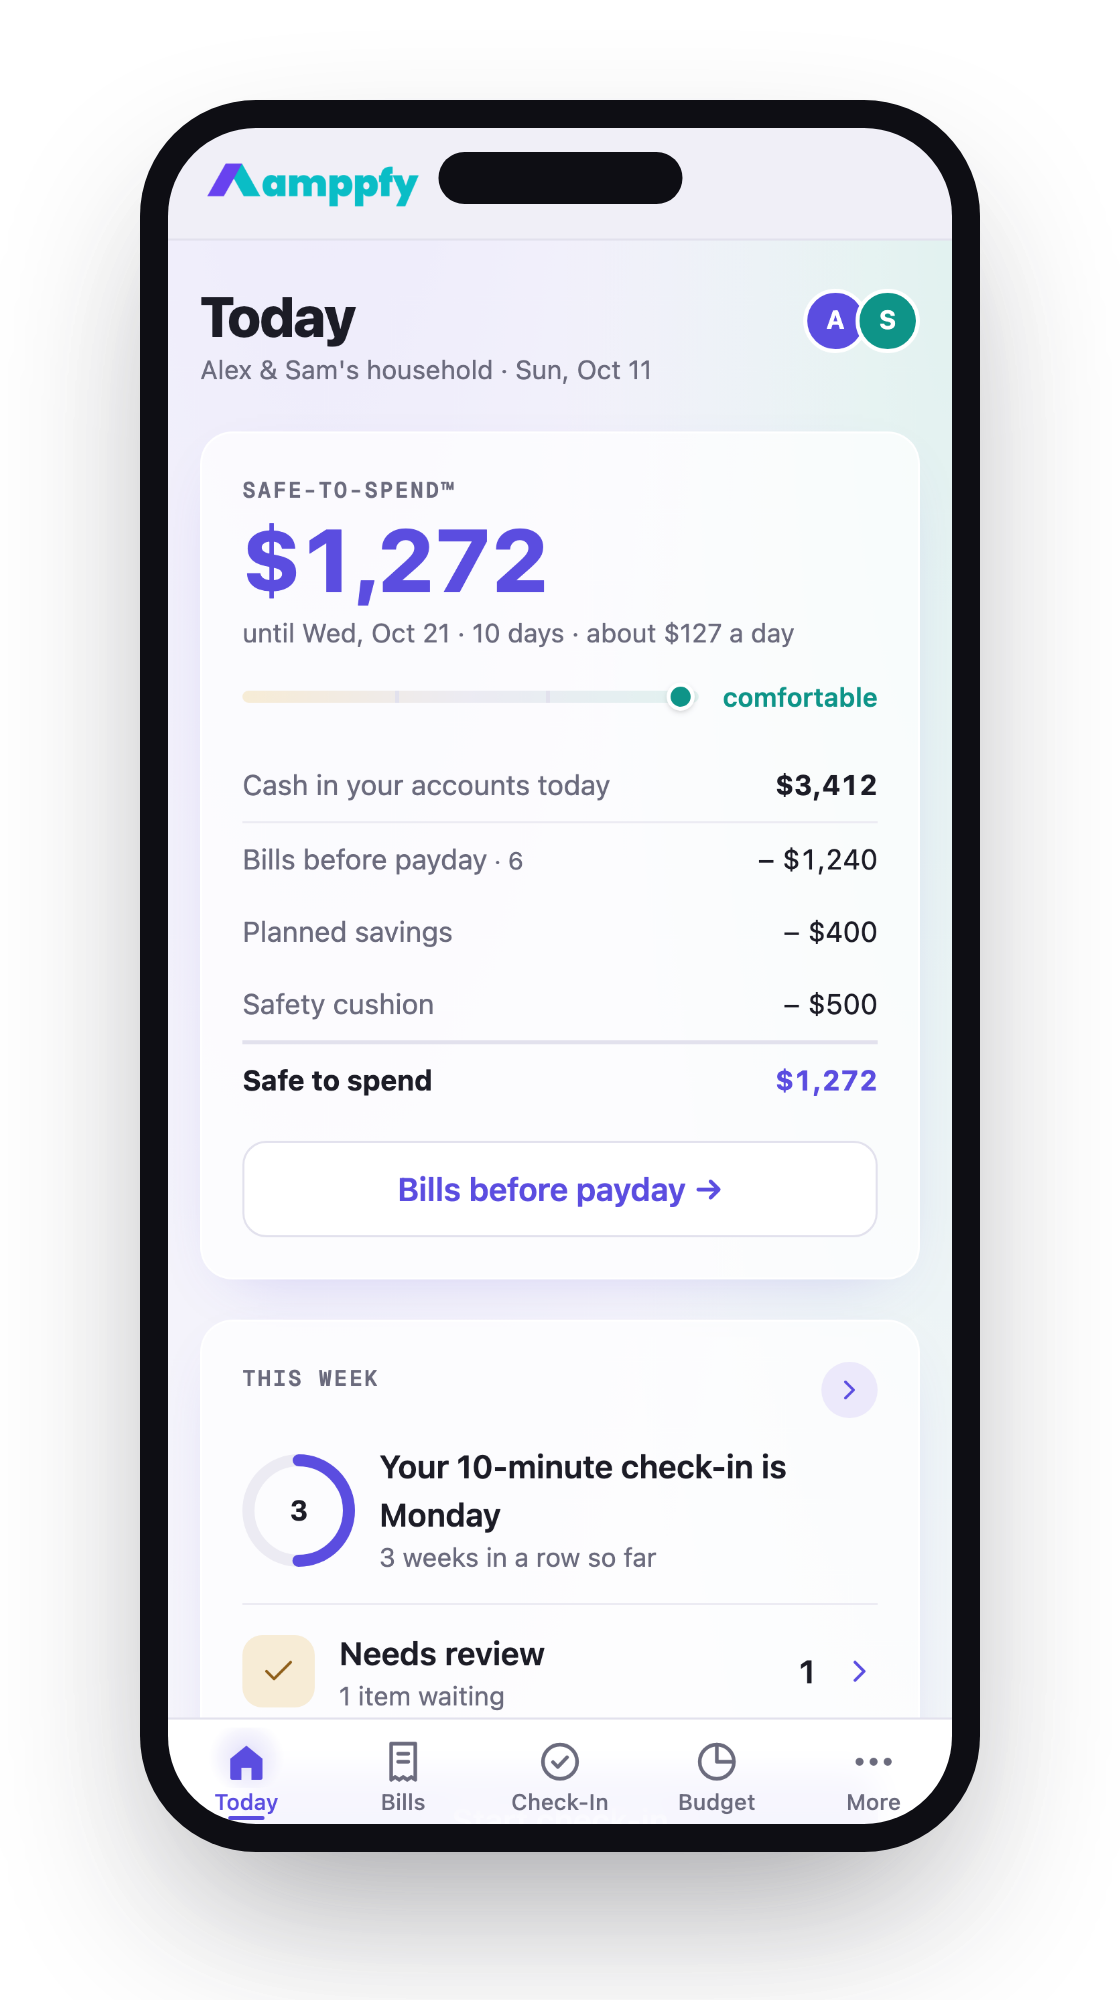
That’s the gap Amppfy was built for. You type in your balances, about 30 seconds per account, with no bank login. It shows one Safe-to-Spend™ number: available cash, minus bills due before payday, minus planned savings, minus a cushion you choose. The four-line math sits right under it.
Here’s how that looks:
- Available cash: $2,400
- Bills before payday: minus $1,350
- Planned savings: minus $200
- Cushion: minus $300
- Safe-to-Spend™: $550
Your partner gets their own login and sees the same number. Your private accounts stay private. A bills calendar marks the lowest-cash day before payday, and heads-ups warn you before a bill is due. It’s free on iPhone and the web, so a partner on Android or a laptop is covered. You can set it up for two here.
FAQ
Can we open a Regions joint account online?
Yes, for a new joint checking or savings account, as of October 2026. Both the primary and joint holders must be the age of majority in your state to open online, per Regions.
Can I add my partner to my existing account online?
No. As of October 2026, Regions asks you to visit a branch with the joint owner, because adding someone changes legal ownership of the account.
Is an authorized signer the same as a joint owner?
No. Regions states an authorized signer is not an owner, as of October 2026. Owners have equal access and shared liability for fees and overdrafts. Ask Regions what a signer can do on your specific account.
What do we need to bring?
SSN or taxpayer ID, photo ID, possibly a secondary ID, birth dates, and contact information for both of you, plus an initial deposit. The minimum is $25 for a Regions checking account or $10 for Regions Now Checking, as of October 2026.
The short version: new accounts can start online, added owners start at a branch, and both paths need the same documents. Pick your path this week, gather the papers in ten minutes, and agree on one shared number before the first bill lands.