
You check your bank app, see a decent balance, and still can’t tell whether it’ll cover rent, the car payment, and that annual renewal you forgot about. The trouble isn’t the money. It’s that your due dates live in six different places: emails, texts, autopay settings, and your memory.
A monthly bill organizer puts all of them on one page, and you can build one online for free in about 15 minutes. This guide gives you a copyable table with a worked example. It then compares the free online routes: a spreadsheet, calendar reminders, and an app.
The goal is calm, not perfection. Once every bill sits next to the paycheck that covers it, most of the guessing stops. You don’t need a finance degree or a Sunday afternoon. You need a list, a few dates, and some honest arithmetic.
What a bill organizer actually has to do
A bill organizer has three jobs. It shows what’s due, when, and which paycheck pays for it. If it can’t answer those three questions at a glance, it’s just a list.
Here’s a table you can copy into a doc, a sheet, or a notebook:
| Bill | Amount | Due date | Paid from which paycheck | Paid? |
|---|---|---|---|---|
| Rent | $1,450 | 1st | Paycheck 1 (1st) | ☐ |
| Car payment | $380 | 8th | Paycheck 1 (1st) | ☐ |
| Phone | $85 | 12th | Paycheck 1 (1st) | ☐ |
| Electric | $120 | 18th | Paycheck 2 (15th) | ☐ |
| Internet | $70 | 22nd | Paycheck 2 (15th) | ☐ |
| Credit card minimum | $150 | 25th | Paycheck 2 (15th) | ☐ |
| Streaming | $16 | 27th | Paycheck 2 (15th) | ☐ |
Now the math for this example month. You’re paid $2,100 on the 1st and the 15th.
- Paycheck 1 covers: $1,450 + $380 + $85 = $1,915. That leaves $185 for two weeks of everything else.
- Paycheck 2 covers: $120 + $70 + $150 + $16 = $356. That leaves $1,744.
The months look lopsided because they are. Rent lands on paycheck 1, so the first half of the month is tight and the second half is roomy. Seeing that split is the whole point. If the first half is always squeezed, you may be able to shift a bill. Some bills let you move the due date and some don’t, and one call can even out the month.
The “Paid?” column matters more than it looks. It’s your memory, written down.
The options
There are four practical free routes for a monthly bill organizer online. Prices and platforms below are as of October 2026. Check each provider’s own site before you commit, because plans change.
| Option | Price | Platform | Bank login needed | Reminders | Shared with a partner |
|---|---|---|---|---|---|
| Printed or doc table | Free | Paper, any doc app | No | None, you check it | Only if you share the file or fridge |
| Google Sheets | Free with a Google account, as of October 2026 | Web, iPhone, Android | No | None built in for due dates | Yes, share the sheet[1] |
| Google Calendar reminders | Free with a Google account, as of October 2026 | Web, iPhone, Android | No | Yes, per event[2] | Yes, share a calendar[3] |
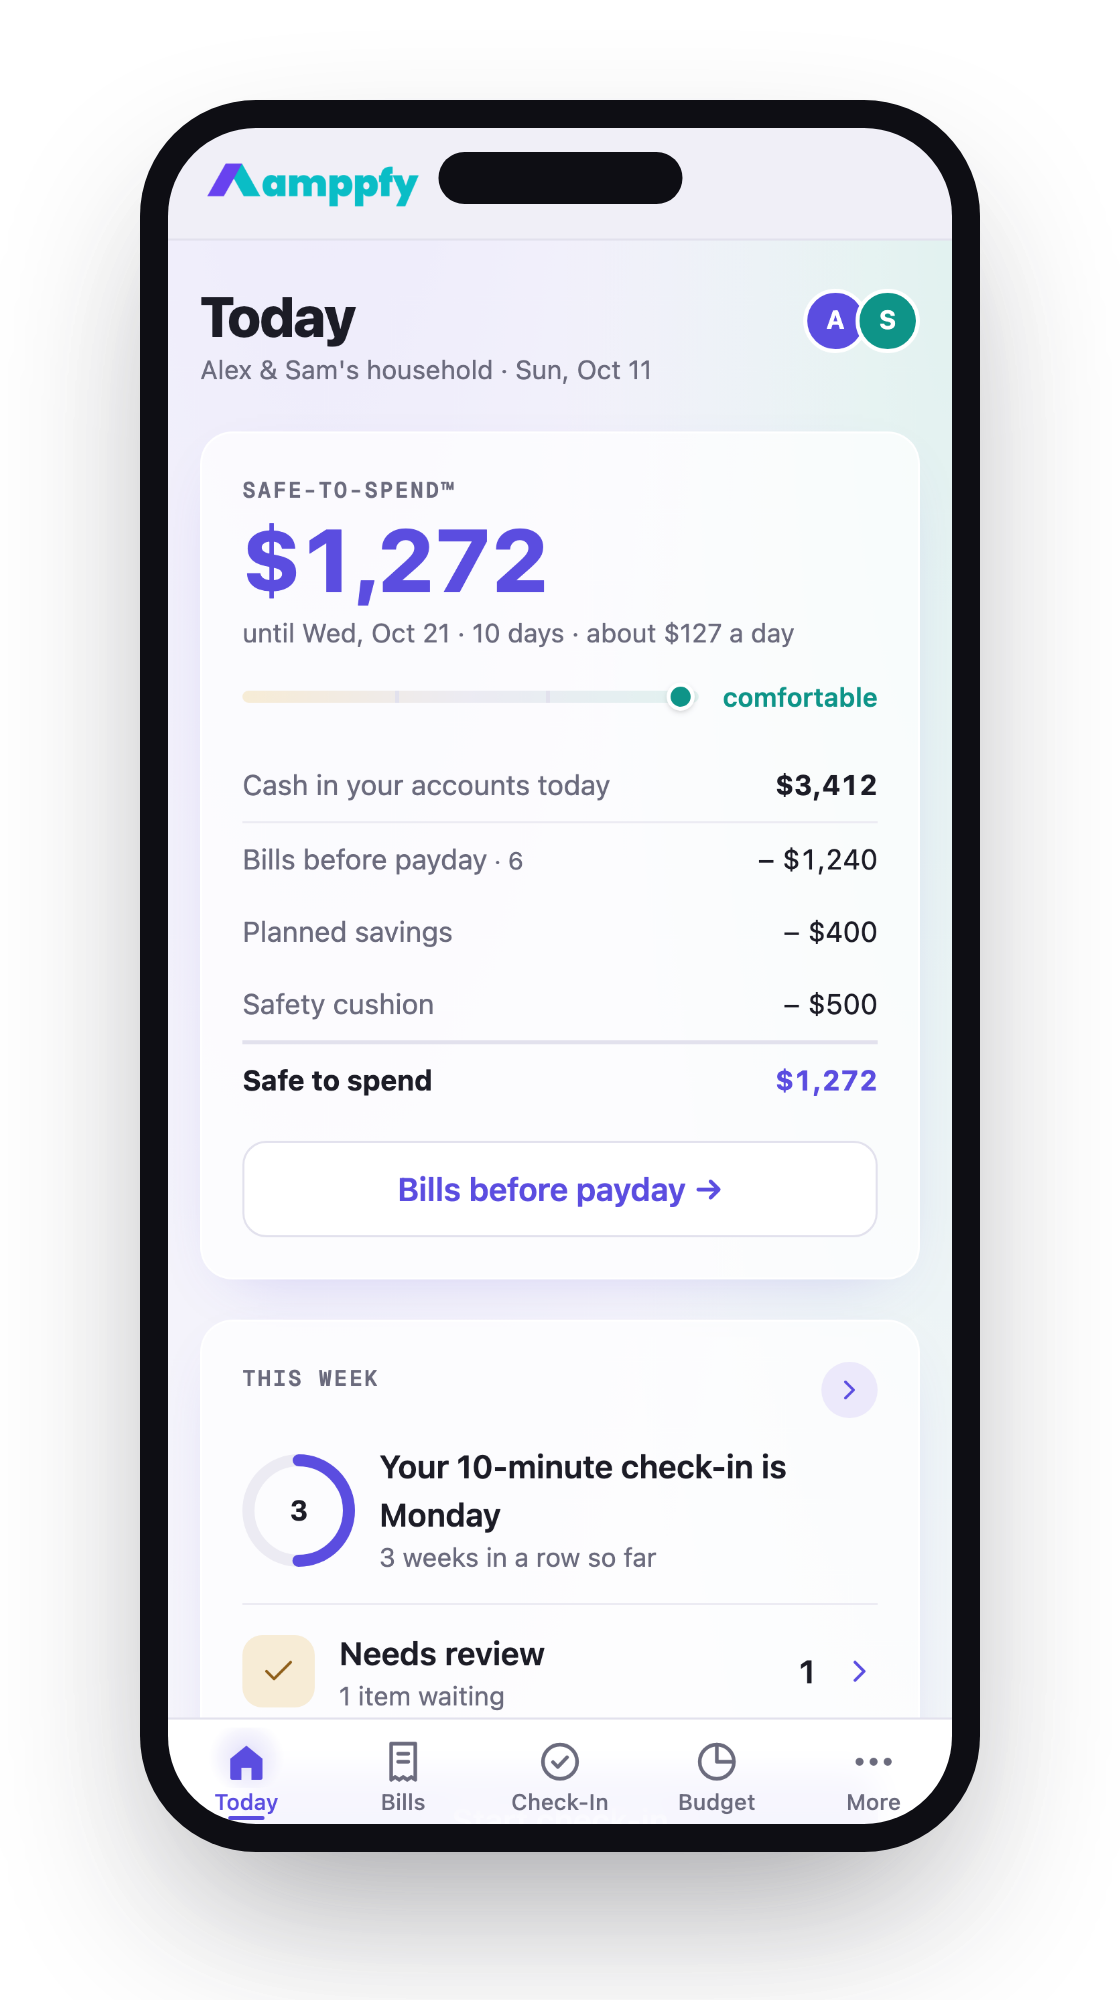
| Amppfy | Free, as of October 2026 | iPhone and web, no Android app | No, balances typed in | Yes, a heads-up the day before a bill | Yes, partner invite, private accounts stay private |
None of these needs your bank password. That’s a real trade-off, not a flaw. You type numbers yourself, which takes a minute. In return, nothing breaks when a bank changes its login screen.
Google doesn’t publish a single page that settles every limit for personal accounts in one place. So treat the Google rows as general. Confirm storage or sharing details on Google’s own help pages if they matter to you.
Each option in two paragraphs
The printed or doc table
This is the table above, copied into Notes, Word, or a sheet of paper on the fridge. It’s free, and it works on any device. It also keeps you honest, because you physically tick the “Paid?” box. For a household with seven or eight fixed bills, it’s often enough.
The weak spot is that it won’t nudge you. If you forget to look, it forgets too. It also doesn’t do any math, so the paycheck totals are yours to add up each month. Use it if you like paper and check it on payday without fail.
Google Sheets
A spreadsheet is the same table with arithmetic built in. Add a SUM under each paycheck group and the leftover calculates itself. Share the sheet with your partner and you both see the same rows. If you split bills, add a “Who pays” column.
The cost is setup and upkeep. You build the formulas, and you roll the dates forward each month. Sheets also has no due-date reminders out of the box. Plenty of people pair it with the next option for that reason.
Google Calendar reminders
Calendar is good at one thing: telling you a date is coming. Create a repeating event for each bill on its due date, with a reminder a day or two before. Put the amount in the event title, like “Electric $120.” Share a “Bills” calendar with your partner so you both get the alert.
What a calendar doesn’t do is add things up. It won’t tell you that three bills land in the same week before payday. Keep the reminders short, too. A plain, neutral line is easier to act on than a paragraph. “Phone $85 due tomorrow” is enough.
A free app
A free budgeting or bills app combines the list, the math, and the reminders. Amppfy is one option. It’s free on iPhone and the web, and you type balances in rather than linking a bank. Bills roll forward on their own. A month calendar marks the lowest-cash day before payday, and a heads-up arrives the day before a bill.
The limits are real. There’s no Android app, so an Android partner uses the web version. There’s no transaction import, so you update balances yourself during a weekly 10-minute check-in. If you want automatic syncing with your bank, look at other apps and read their own pricing pages.
What a calendar shows that a list does not: the lowest point before payday
A list tells you the total. A calendar tells you the timing. Timing is usually where the trouble starts.
Go back to the example month. Say you have $300 in checking on the morning of the 1st. Walk through it day by day:
| Date | Event | Balance |
|---|---|---|
| 1st | +$2,100 paycheck, −$1,450 rent | $950 |
| 8th | −$380 car | $570 |
| 12th | −$85 phone | $485 |
| 15th | +$2,100 paycheck | $2,585 |
The lowest point is $485, from the 12th through the 14th. That’s before groceries, gas, and a school field trip fee. If you spend $400 on everyday things in those two weeks, you’re down to $85 on the 14th. On a list, this month looks fine: $2,271 in bills against $4,200 in pay. On a calendar, you can see the thin spot.
That thin spot is the number to plan around. It’s the logic behind the Safe-to-Spend™ figure in the app row above: available cash, minus bills due before payday, minus planned savings, minus a cushion you choose. You don’t need an app to do it, though. In a spreadsheet, add a running balance column and look for the smallest value before each payday. Once you know your lowest day, you can protect it. Hold off on a purchase until the 15th, or move one bill.
How to set one up in 15 minutes
Set a timer. This is meant to be quick.
- Minutes 0 to 4: Gather the bills. Open your bank app and scroll back about 35 days. Write down every recurring charge: name, amount, date. Check your email for annual renewals too.
- Minutes 4 to 6: Note your paydays. Write the dates and take-home amounts for the next two paychecks.
- Minutes 6 to 9: Fill in the table. Use the five columns: bill, amount, due date, paid from which paycheck, paid. Assign each bill to the last paycheck that arrives before its due date.
- Minutes 9 to 11: Add it up. Total each paycheck group and subtract it from that check. Look for the tight half of the month.
- Minutes 11 to 13: Find the lowest point. Start from today’s balance and walk forward date by date. Circle the smallest number before payday.
- Minutes 13 to 15: Set reminders. Add calendar alerts or turn on app heads-ups for each bill. Pick whichever channel you actually see, whether that’s a push alert, a text, or an email.
If you share bills, send the sheet, calendar, or invite to your partner before you close the laptop. Splitting by percentage? Add one column for each person’s share. That’s it. After this, upkeep is a few minutes on each payday: tick the boxes and check the next low point.
FAQ
Is a free online bill organizer as good as a paid one?
For tracking due dates and covering them from the right paycheck, yes. Free spreadsheets, calendars, and apps handle the core jobs. Paid tools mostly add bank syncing and spending categories. If upkeep or broken sync made you quit an app before, a simpler free setup may last longer.
What if two big bills land right before payday?
First, find the lowest point on your calendar and see how thin it gets. Then call the biller and ask about moving the due date. Many lenders and utilities allow a change, but some don’t. Moving one bill by a week can even out the whole month.
How do couples with separate money use one organizer?
Add a “Who pays” column, or a percentage split, and share one view. Each person pays from their own account, and you both see the same due dates. In an app with a partner invite, shared bills appear for both of you. Private accounts stay private.
How often should I update it?
Weekly is enough for most households. Use a short check-in to confirm balances, tick off paid bills, and look at the next lowest day. Monthly works for very steady budgets. Payday is a natural moment either way.
Your bills were never the mystery. The timing was. Once every due date sits next to the paycheck that covers it, the month looks like ordinary arithmetic. Pick the route that fits how you already work. Paper suits a fridge person, a sheet suits a spreadsheet person, and a calendar or an app suits someone who wants a nudge.
Want the list, the math, and the lowest-point calendar in one place? Take 15 minutes this week and set up your bills and paydays in Amppfy. It’s free on iPhone and the web.