
Most missed bills aren’t about money you don’t have. They’re about timing. A rent payment lands two days before your paycheck, a car insurance draft hits the same morning as a phone bill, and your bank app shows a balance that was true yesterday.
A list of due dates helps a little. A month grid helps more, because it shows you when money leaves next to when money arrives. That’s the job of a bill calendar app: put every date in one place so you can see the tight spots before you reach them.
This guide covers what a good one needs to do, how five common options compare, and how to set one up in about 15 minutes. You don’t need a new budgeting philosophy or a weekend of setup. You need your bills, your paydays, and your current balances in one view you’ll actually open.
What a bill organizer actually has to do
Many apps say they “track bills.” That can mean anything from a reminder list to a full budgeting system. Strip it back, and a useful tool does six things.
- Due dates on a month grid. You see the whole month at a glance, not a scrolling list. Clusters of bills stand out right away.
- Paydays on the same grid. Income and bills share one calendar. Otherwise you’re doing the timing math in your head.
- The lowest point before payday. The app shows the day your cash dips furthest. That’s the number that decides whether a bill clears.
- Reminders before the date. A heads-up the day before gives you time to move money. A reminder on the due date is often too late.
- Partner sharing. If you split bills, both of you should see the same dates without forwarding screenshots.
- No bank login required, if you prefer. Some people want automatic sync. Others are done with broken connections and would rather type a balance in 30 seconds.
You don’t need every feature. A single person with four bills and automatic payments might only need reminders. A couple with hybrid finances and a biweekly paycheck needs paydays, sharing, and the low point.
Pick the two or three that matter most to you. Then judge each option against those, not against a feature checklist someone else wrote.
The options
Here’s how five common choices line up. Prices change, so each one is marked with a date. Check the company’s own site before you sign up.
| Option | Price | Platform | Bank login needed | Reminders | Shared with a partner |
|---|---|---|---|---|---|
| Amppfy | Free, as of October 2026 | iPhone and web | No: you type in balances | Heads-up the day before a bill | Yes: partner invite, private accounts stay private |
| Google Calendar | Free with a Google account, as of October 2026 | Web, iPhone, Android | No | Yes, you set the timing per event | Yes, by sharing a calendar |
| Rocket Money | Free tier includes bill tracking; Premium $7 to $14 a month, as of October 2026[1] | iPhone and Android; web on paid tiers | Built around linking accounts | Tracks upcoming bills | Premium only: a second login for one partner |
| YNAB | $14.99 a month or $109 a year, 34-day free trial, as of October 2026[2] | iPhone, Android, web | Optional: direct import or manual entry | Scheduled transactions show upcoming bills | Yes: YNAB Together, up to six people |
| Monarch Money | $14.99 a month or $99.99 a year, 7-day free trial, as of October 2026[3] | iPhone, Android, web | Built around linking accounts | Bills and subscriptions on one calendar | Yes: invite a partner at no extra cost[4] |
Two notes on reading this table. First, “bank login needed” is about how the app is designed to work. Several apps offer manual options, but the experience is built for sync. Second, “reminders” varies a lot in timing. Some apps let you pick the lead time and others don’t.
For a wider look at tools focused just on reminders, see this roundup of bill tracker apps that help you never miss a due date.
Each option in two paragraphs
Amppfy
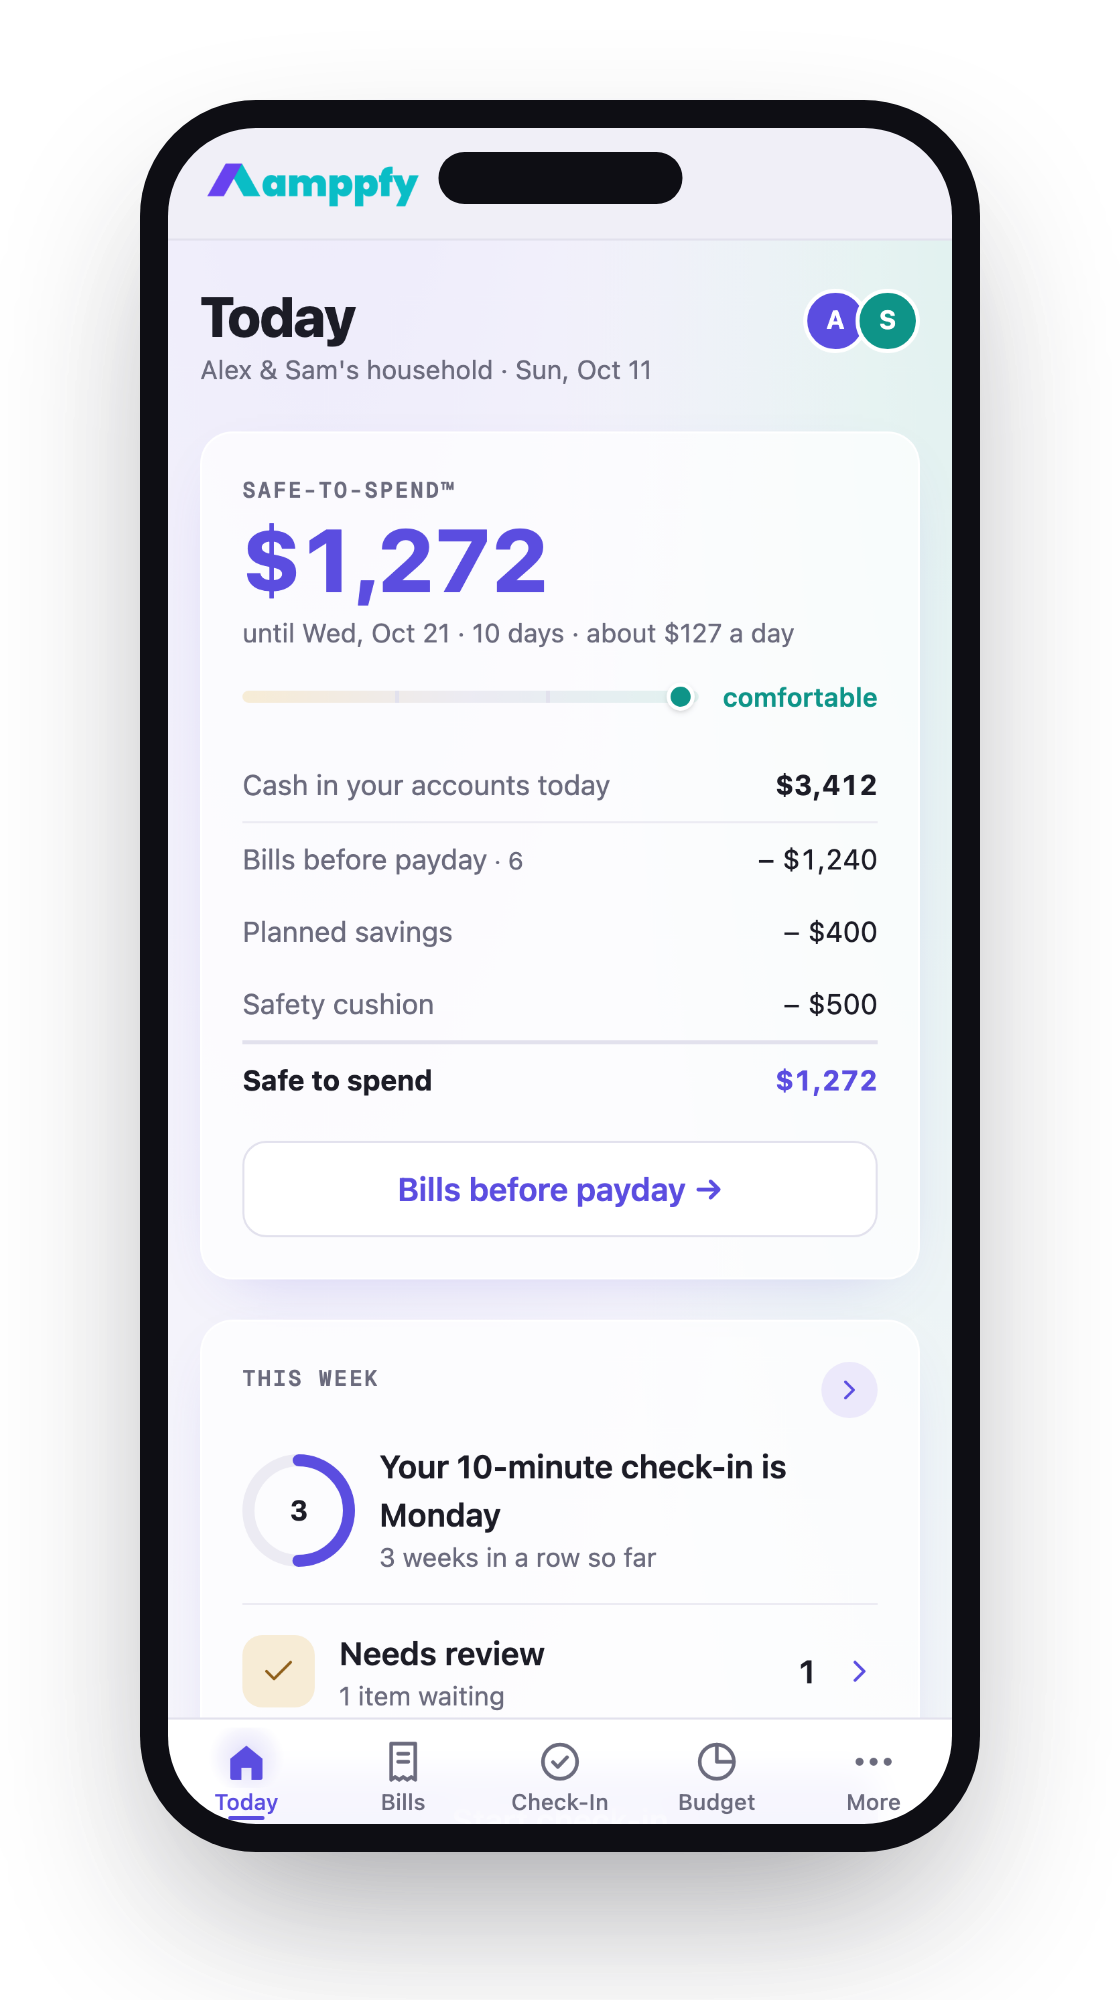
You enter your balances, bills, and paydays once. The month calendar shows bills and paydays together and marks the lowest-cash day before your next paycheck. Bills roll forward on their own, and you get a heads-up the day before each one. A weekly check-in of about 10 minutes keeps the numbers current.
The trade-off is that nothing imports. You type balances in yourself, and there’s no transaction history pulled from your bank. There’s also no Android app, so a partner on Android uses the web version. If you want automatic categorization, this isn’t that tool.
Google Calendar
It’s free, you probably already have it, and it runs everywhere. You can make a separate “Bills” calendar, set each bill as a recurring event, add paydays, and share it with a partner. Reminders are flexible, so you can set one two days ahead.
The catch: it knows nothing about money. It won’t add up what’s due before payday or show your low point. You’ll do that arithmetic yourself. And if a bill amount changes, you have to edit the event by hand.
Rocket Money
The free tier includes bill tracking, which is enough for many people. It’s designed around linking your accounts, so it can spot recurring charges and subscriptions on its own. Premium runs $7 to $14 a month as of October 2026[1].
That automation is the appeal and the risk. When a bank connection breaks, the picture goes stale until you reconnect. If you’ve left apps before because of sync problems, weigh that honestly.
YNAB
YNAB is a full budgeting system built on giving every dollar a job. Scheduled transactions show upcoming bills in the register, you can import from your bank or enter things by hand, and YNAB Together lets up to six people share one subscription. It costs $14.99 a month or $109 a year, with a 34-day free trial, as of October 2026[2].
It asks more of you than a bill calendar does. That’s on purpose. If you want a detailed budget, it’s a serious option. If you just want to stop missing due dates, it may be more system than you need.
Monarch Money
Monarch is a paid, sync-based app with a dashboard, bills and subscriptions on one calendar, and a partner invite at no extra cost[4]. It suits people who want net worth, spending, and bills in one connected place. It costs $14.99 a month or $99.99 a year, with a 7-day free trial, as of October 2026[3].
Like other sync-based tools, it depends on bank connections staying healthy. It’s also a monthly or annual cost. That’s worth it to some people and a reason others leave.
What a calendar shows that a list does not: the lowest point before payday
A list tells you what’s due. A calendar tells you when you’ll feel it. With money, the reason is simple: order matters.
Here’s an example. You have $2,400 in checking on the 1st. Payday is the 15th.
| Date | Event | Balance after |
|---|---|---|
| 1st | Starting balance | $2,400 |
| 3rd | Rent | $800 |
| 5th | Car payment | $460 |
| 8th | Phone and internet | $300 |
| 10th | Car insurance | $160 |
| 15th | Payday | $1,960 |
Bills total $2,240. You start with $2,400. A list says you’re fine: $160 left over.
The calendar shows something the list hides. Your lowest point is $160 on the 10th, and that’s before groceries, gas, and anything else. Spend $200 on groceries by the 9th and your balance dips below zero before the insurance draft. The math on the list was right. The timing wasn’t visible.
That low point is the number to watch. An overdraft fee is set by your bank, so check its fee schedule and treat the dip as the thing to avoid. The fix is calm and ordinary. Move a bill date, shift money from savings on the 9th, or hold back on spending until the 15th. You can only do that if you see the dip coming.
The best bill calendar app puts that low day on the grid for you. Use a plain calendar and you can still find it. Just add the running balance yourself, line by line.
How to set one up in 15 minutes
You don’t need a perfect setup. You need a true one. Here’s a sequence that fits in a coffee break.
- Gather your numbers (3 minutes). Open your bank app. Note your checking balance and your next two paydays. Have last month’s statement handy for bill amounts.
- List every bill with a date (4 minutes). Rent, utilities, phone, insurance, loans, credit card minimums, subscriptions. Write the usual amount and due date for each.
- Add paydays first (1 minute). Put income on the grid before bills. It anchors everything else.
- Add bills as recurring items (4 minutes). Set each one to repeat monthly, or on its real cycle. Quarterly and annual bills count too.
- Set reminders one or two days early (1 minute). That gives you time to move money if needed. Same-day reminders are a weak safety net.
- Find the low point (1 minute). Look at the stretch between now and your next payday. Note the day with the least cash. If it’s tight, decide now what you’ll move.
- Share it (1 minute). If you split bills, invite your partner. One shared view beats two separate guesses.
After setup, the upkeep is small. Once a week, update your balance and check the next two weeks. When a bill changes, fix it right then. That’s it.
One of the most useful bill calendar app tips is to schedule the check-in itself. Put a 10-minute recurring event on Sunday night or payday morning. A routine you don’t have to remember is a routine you’ll keep.
FAQ
Do I need to connect my bank to use a bill calendar?
No. A bill calendar works fine with balances you type in yourself. Sync saves typing, but connections can break and leave your view out of date. Manual entry takes about 30 seconds per account and you always know the number is current as of the moment you entered it.
Is Google Calendar good enough for bills?
It can be, especially if you have few bills and steady income. It handles dates, reminders, and sharing well. What it can’t do is add up your money or show your lowest balance before payday. You’ll do that part on paper or in your head.
How far ahead should reminders go off?
One to two days before the due date works for most people. That’s enough time to move money between accounts or adjust spending. If your bank needs extra time to process transfers, check its own site for posting details and set reminders earlier to match.
What should I do if my low point looks too tight?
Start with the simplest move. Ask whether a biller will shift your due date to just after payday. Many will. You can also move money from savings before the low day, or pause flexible spending until payday. The goal is a low point you’re comfortable with, not zero.
The right tool is the one that shows your due dates, your paydays, and your lowest day on one screen, and that you’ll open once a week. For some people that’s a shared Google Calendar. For others it’s a sync-based app with more features. If you’d like a free option on iPhone and the web with the low point marked for you, you can try the Amppfy bills calendar. Take 15 minutes this week, put next month on the grid, and find your low day before it finds you.