
You skipped a savings deposit last month. Maybe the car needed new brakes, or groceries ran higher than expected, or you just forgot. That missed savings month can feel like a reason to quit your plan entirely. It isn’t. One gap in your savings habit is fixable, and you don’t need to double up or punish yourself to get back on track. The real risk isn’t the month you missed: it’s letting a single miss turn into two, then three, then “I’ll start again in January.” Here’s how to restart quickly and keep your goal intact.
Why a missed month feels bigger than it is
Your brain treats a skipped savings deposit like a broken streak. You had momentum, and now it’s gone. That feeling is real, but it’s misleading.
Researchers have identified a pattern called the “What-the-Hell Effect,” where missing a monthly goal triggers increased discretionary spending[1] because the person feels they’ve already failed for the period. You skip $200 in savings, feel defeated, and then spend an extra $80 on takeout because the month is “already ruined.” The miss costs you $200. The reaction costs you $280.
Here’s what the habit research actually shows: one missed opportunity to perform a behavior doesn’t materially hurt the habit-formation process[2]. The real danger is a second consecutive miss, which starts building a new pattern of not saving. One month off is a blip. Two months off is a trend your brain starts to normalize.
So the goal right now isn’t to “make up” for lost time. It’s to prevent the second miss. That reframe matters. You’re not recovering from failure. You’re protecting a habit that’s still alive.
A few things that don’t help: guilt, a vow to save double next month, or pretending it didn’t happen. What does help is a small, concrete action you can take before the next payday.
What one month really costs a goal
The emotional weight of a missed month almost always outweighs the financial cost. Let’s look at the actual math.
Say you’re saving $300 a month for an emergency fund target of $3,600. You miss one month. You’re now at $3,300 after 11 deposits instead of 12. That’s 91.7% of your goal, reached one month later than planned. Not great, but not a disaster.
| Scenario | Monthly deposit | Months saved | Total saved | % of $3,600 goal |
|---|---|---|---|---|
| No miss | $300 | 12 | $3,600 | 100% |
| One missed month | $300 | 11 | $3,300 | 91.7% |
| Two missed months | $300 | 10 | $3,000 | 83.3% |
| Quit after miss | $0 | 0 remaining | Stops growing | Frozen |
The gap between one miss and quitting entirely is enormous. Quitting costs you every future deposit. One miss costs you one deposit.
For longer-term goals, compound growth does amplify the cost of delays. A 10-year delay in starting a $500-per-month investment habit at an 8% return can mean roughly $998,000 less at retirement. But that’s a decade-long delay, not a single month. One skipped month at $500 with an 8% annual return costs you about $4 in lost growth over the first year. The compounding penalty is real over years, not weeks.
The point: don’t confuse a one-month pause with a permanent setback. They’re different problems with different price tags.
Restart with a smaller amount
The fastest way to break a saving gap is to make the next deposit so small it’s impossible to skip.
If your normal target is $300, deposit $25. Or $50. Or whatever amount you can move right now without checking your balance twice. The purpose isn’t to hit your goal this month. It’s to perform the action of saving, which keeps the habit loop intact.
Why smaller works better than catching up
Doubling up after a miss sounds responsible, but it usually backfires. If $300 was already tight, $600 is a setup for another skip. And another skip starts that dangerous two-miss pattern.
A smaller restart does three things:
- It proves to yourself that you’re still a person who saves.
- It removes the decision fatigue of “can I afford the full amount?”
- It gives you a win, which makes next month’s full deposit feel normal again.
A practical restart sequence
- Pick a number between $10 and half your usual deposit.
- Transfer it today, not “next payday.”
- Next payday, return to your normal amount.
- If the normal amount still feels tight, stay at the reduced level for one more cycle.
You can track this recovery inside Amppfy’s Budget page, which breaks your month into four slices: Bills, Savings, Subscriptions, and Everyday spending. Your savings goal stays visible month by month, read from the plan you already entered. You’ll see the dip and the recovery without hunting through bank statements.
The habit research suggests complex financial behaviors can take up to 335 days to become automatic. A small deposit during a rough month keeps that clock running instead of resetting it.
Using a fresh start: payday or the 1st
Psychologists call it the “fresh start effect.” People are more likely to begin a new behavior on a date that feels like a clean boundary: a Monday, the first of the month, a birthday, a payday. You can use this deliberately.
Pick your restart date
If you’ve missed a deposit, circle your next payday or the upcoming 1st on your calendar. That’s your restart line. Don’t try to fix things mid-cycle when bills are still landing. Wait for the natural reset.
Research on optimism and saving behavior shows that dispositional optimism predicts savings behavior more strongly than financial literacy[3], especially in lower-income households. Framing your restart as a fresh beginning, not a correction, feeds that optimism. You’re starting a new month, not apologizing for the last one.
Make it automatic on that date
The best restart is one you don’t have to remember. Set up an automatic transfer for payday or the 1st. Even a small one. The transfer fires, the deposit lands, and you’ve saved without making a decision that morning.
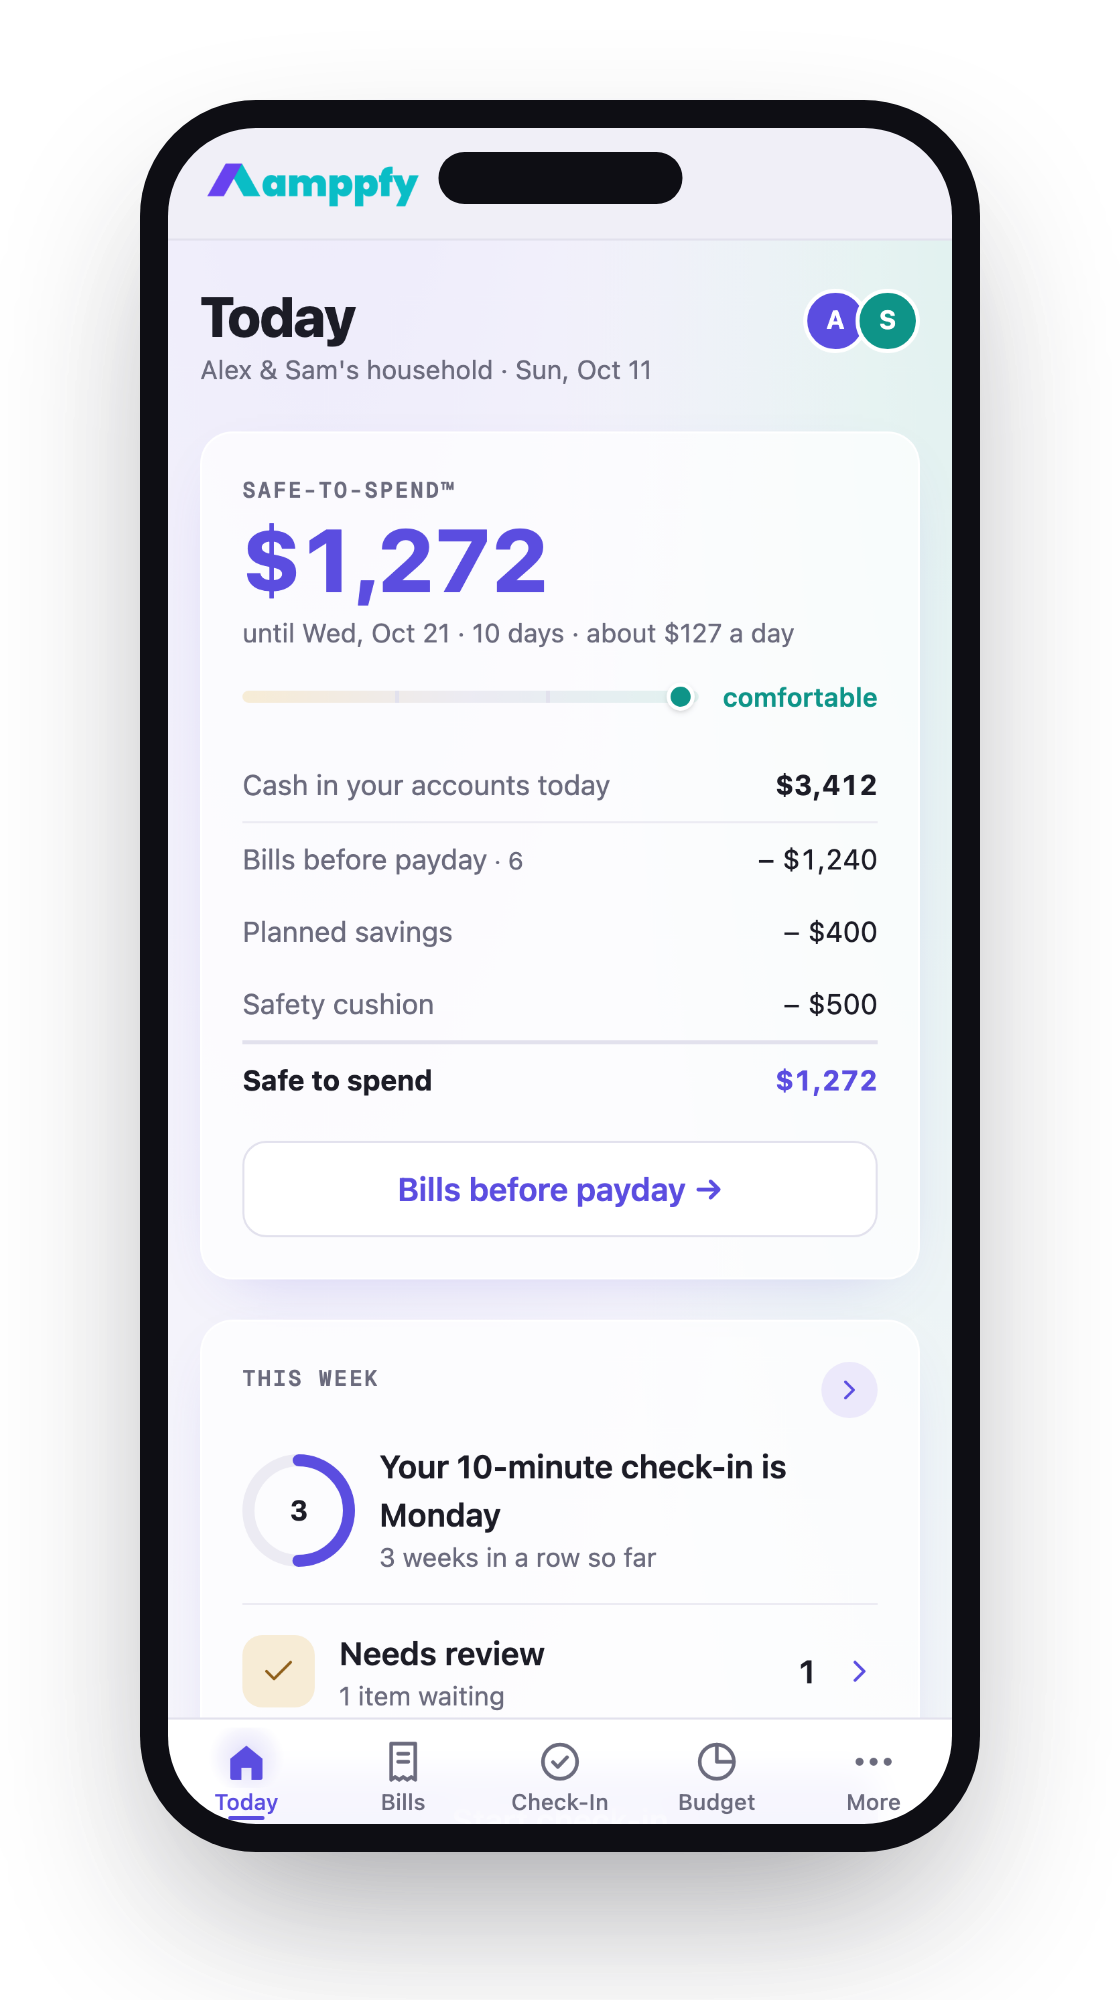
If you use Amppfy, the payday nudge reminds you to fund goals first when your check hits. Your Safe-to-Spend™ number already accounts for planned savings, so you see what’s actually available after the deposit, not before. The math looks like this:
$3,412 cash − $1,240 bills − $400 savings − $500 cushion = $1,272 Safe-to-Spend™
That $1,272 is what you can spend without touching your savings goal or falling short on bills. No guessing required.
A fresh-start date works because it separates the past month from the next one. You’re not dragging a failure forward. You’re stepping into a new cycle with a plan already in place.
Keeping the goal, adjusting the date
One missed month means your timeline shifts by roughly one month. That’s it. The goal itself doesn’t change. Your emergency fund target is still $3,600. Your vacation fund is still $1,800. You just arrive a little later.
When to adjust the date vs. the amount
| Situation | Best move |
|---|---|
| One missed month, budget is stable | Push the target date back one month |
| Two missed months, budget is tighter | Lower the monthly amount, extend the date |
| Income changed permanently | Recalculate the monthly amount from scratch |
| Goal no longer relevant | Replace it with a goal that matters now |
Pushing a date back by 30 days is painless. Trying to cram extra deposits into future months creates pressure that leads to more misses. Be honest about what happened and adjust the calendar, not your stress level.
Recalculating your plan
If your household budget has shifted since you set the goal, spend 10 minutes recalculating. Take your remaining goal balance, divide by a comfortable monthly deposit, and count forward. That’s your new target date.
Example: you need $2,400 more for your goal. You can comfortably save $250 a month. That’s about 10 months from now. Mark it. Move on.
For couples, this recalculation is a quick conversation, not a negotiation. If you’re both looking at the same savings number and the same timeline, the adjustment is just math.
The worst response to a skipped month is pretending the original deadline still works. That creates invisible pressure and sets you up for another miss. A realistic date protects the habit. An aspirational date threatens it.
Frequently Asked Questions
Should I try to make up a missed savings deposit by doubling next month?
Usually not. Doubling your deposit after a tight month increases the chance you’ll skip again. A better approach: resume your normal amount next payday. If you have genuine surplus, add a portion, but don’t commit to the full double. Consistency matters more than any single deposit size.
Does missing one month of saving ruin compound interest?
Not meaningfully. Compound growth penalizes long delays, not short pauses. Skipping one $300 deposit costs you a few dollars in lost interest over the first year. Skipping 10 years of deposits costs you hundreds of thousands. The math favors restarting quickly over restarting perfectly.
How do I stop feeling guilty about a missed month?
Reframe it. You didn’t fail a test. You paused a habit. Habit research shows one miss doesn’t damage the underlying pattern. The guilt itself is the bigger risk because it can trigger the “What-the-Hell Effect,” where you spend more because you feel the month is already lost. Make one small deposit, any amount, and the guilt fades because you’ve taken action.
What if I keep missing savings months because my budget is too tight?
That’s a signal your savings target is set too high for your current income, not that you lack willpower. Drop the monthly amount to something you can hit nine months out of twelve. A $100 deposit you actually make beats a $400 deposit you skip three times a year. Workers have been reducing their contribution rates[4] due to affordability pressure, and adjusting your target to match reality is a practical response, not a concession.
Get Back to Your Number
A skipped month is one deposit, not a verdict on your financial life. Resume saving at any amount, use your next payday as a clean starting line, and push your target date back instead of pushing yourself into another miss. The habit survives if you act within the next pay cycle.
If you want one clear number that already accounts for your savings goal, bills, and a cushion you choose, get Amppfy free. Enter your balances, bills, and payday once, about ten minutes, and your Safe-to-Spend™ number is always there. No guessing whether you can afford to save this month: the math is already done.