
Getting paid once a month can feel like a puzzle with a missing piece. Your bank account looks healthy on payday, but by week three, you’re doing mental math at the grocery store. The fix isn’t earning more or spending less on everything you enjoy. It’s building a monthly pay budget that accounts for the full 30-day stretch before a single dollar leaves your account. This approach takes about an hour to set up and ten minutes a week to maintain.
Why Monthly Pay Feels Rich on the 1st and Thin on the 25th
Most U.S. workers get paid biweekly or semimonthly. Pay frequency varies by state law rather than federal mandate[1], so if your employer chose monthly, you’re working with one deposit that has to cover everything. That single lump sum creates a specific psychological trap.
On the 1st, your checking balance is the highest it’ll be all month. Your brain reads that number as “available.” You buy the shoes. You say yes to dinner. You restock the pantry with the good cheese. None of these choices are reckless on their own. The problem is timing: your brain treats a monthly balance like a biweekly one.
By the 25th, rent has cleared. Utilities hit. The auto-pay for insurance pulled its share. What’s left has to stretch five or six more days, and it often doesn’t feel like enough. The spending wasn’t wild; it just wasn’t paced.
There’s a compounding pressure, too. Household spending expectations have climbed to about 5.0% growth[2], outpacing expected income growth of 2.8%. That gap means each month’s paycheck covers slightly less than it did a year ago. You’re not imagining the squeeze.
The fix isn’t willpower. It’s structure. You need a system that tells you what’s actually available after every obligation is accounted for, not just what the bank app shows.
Front-Load the Bills, Then Find the Real Number
Your paycheck is not your spending money. It’s a gross number that includes rent, insurance, subscriptions, savings goals, and the electric bill. The first step in a budget built around monthly pay is subtracting every fixed cost before you think about groceries or gas.
List Every Fixed Obligation
Pull up your last two months of bank statements. Write down every recurring charge with its amount and due date. Here’s a simplified example:
| Category | Monthly Amount | Due Date |
|---|---|---|
| Rent/Mortgage | $1,400 | 1st |
| Car Payment | $380 | 10th |
| Insurance (auto + renter’s) | $210 | 15th |
| Utilities (avg.) | $185 | 20th |
| Subscriptions | $62 | Various |
| Student Loan | $275 | 5th |
| Total Fixed | $2,512 |
Find Your Real Number
Once you know your fixed costs, the math is one line:
$4,800 paycheck − $2,512 bills − $350 savings goal − $400 cushion = $1,538
That $1,538 is what you actually have for food, gas, personal spending, and anything else for the month. Not $4,800. Not even close. Seeing the real number on payday, before you spend anything, is the single most useful thing you can do.
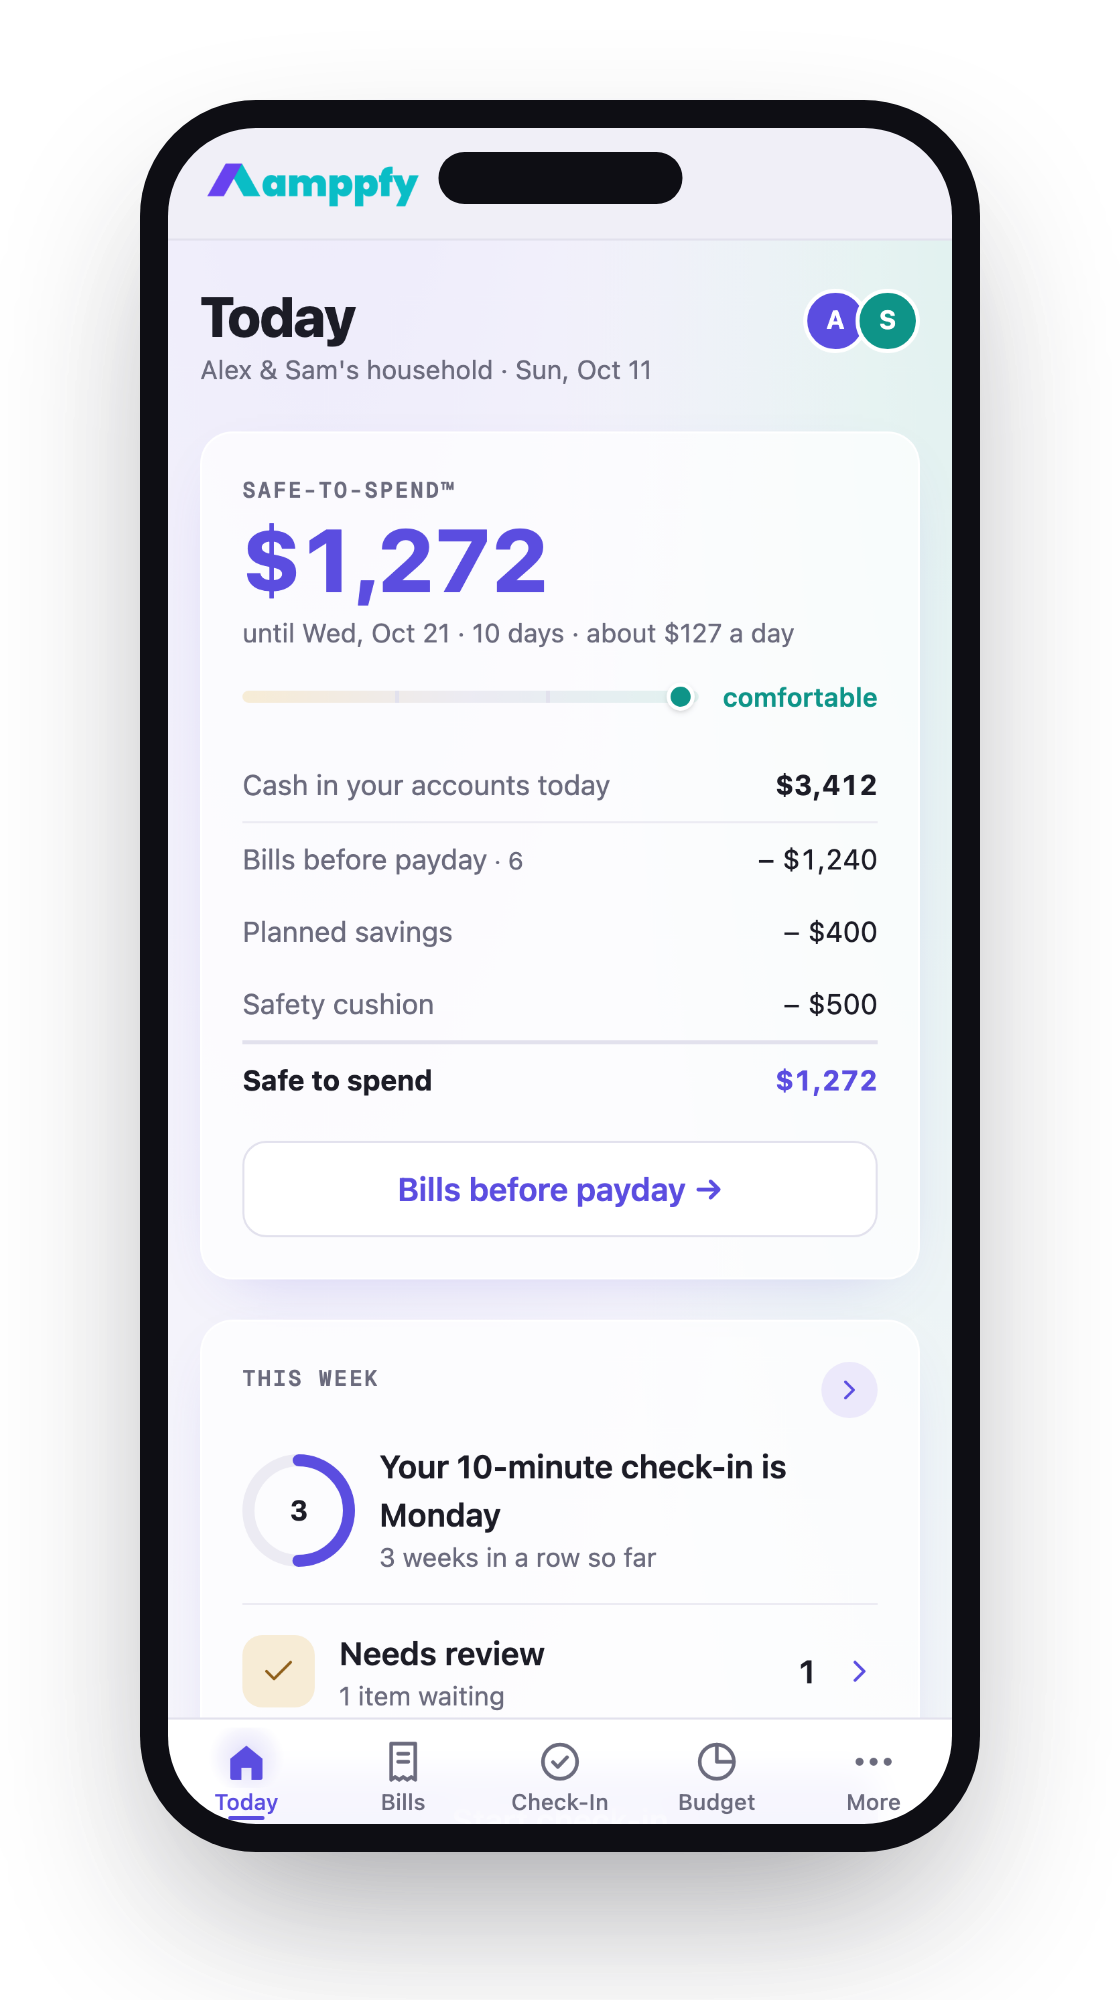
Amppfy calls this your Safe-to-Spend™ number. It’s your cash minus bills due before your next payday, minus planned savings, minus a cushion you pick. The four-line math is always visible so you know exactly where the number comes from.
Schedule every bill payment for the first five days after payday if your due dates allow it. Many creditors let you shift due dates with a phone call. Front-loading bills means the money left in your account after the 5th is genuinely yours to spend.
Splitting the Month Into Weekly Spending
Knowing your real number is half the job. The other half is pacing it across four weeks so you don’t burn through it in two.
The Weekly Allowance Method
Take your spending money and divide it by four. Using the example above:
$1,538 ÷ 4 = $384.50 per week
Round down to $380. That’s your weekly spending cap for groceries, gas, dining, entertainment, and personal purchases. The leftover few dollars each week accumulate as a small bonus by month’s end.
You can manage this a few ways:
- Separate checking account: Transfer $380 every Monday from your main account. Spend only from this account for daily purchases.
- Cash envelopes: Withdraw $380 in cash each week. When the cash is gone, the week’s spending is done.
- App-based tracking: Check your Safe-to-Spend number against your weekly target. Amppfy updates this number whenever you enter a new balance, which takes about 30 seconds per account.
Handling Irregular Weeks
Not every week costs the same. A birthday dinner falls in week two. The dog needs a vet visit in week three. You can handle this by borrowing from a future week, not a past one.
If week two costs $450, week three’s budget drops to $310. Write it down. Adjust before you spend, not after. The goal isn’t perfection. It’s awareness of the trade-off before you make it.
Some months have five weekends. If your fun spending clusters on Saturdays, those months will feel tighter. Plan for them by shaving $20 off each of the first three weeks and banking it for week five.
A Cushion Sized for the Long Stretch
A monthly pay cycle means 30 days between deposits. If something breaks or an unexpected bill shows up on the 22nd, you can’t wait three days for a biweekly check. You need a buffer inside the month, separate from your emergency fund.
How Much Cushion Is Enough
Your cushion isn’t an emergency fund. It’s a shock absorber for the current month. A good starting point is 10-15% of your take-home pay.
| Take-Home Pay | 10% Cushion | 15% Cushion |
|---|---|---|
| $3,500 | $350 | $525 |
| $4,800 | $480 | $720 |
| $6,000 | $600 | $900 |
Pick a number that lets you sleep through week four without checking your balance at 2 a.m. If you’ve never budgeted on monthly pay before, start at 15% for the first three months. You can dial it back once you trust your system.
The cushion sits in your checking account but stays subtracted from your Safe-to-Spend number. You don’t touch it unless something genuinely unplanned hits: a car repair, a medical copay, a broken appliance. If you dip into it, you replenish it from the next paycheck before funding anything else.
Paycheck-to-paycheck living continues to rise among lower-income Millennials and Gen X[3], and a missing cushion is often the difference between a tight month and a crisis month. Even $300 set aside changes the math.
What the Cushion Is Not
It’s not a savings goal. It’s not vacation money. It’s not “extra” that you sweep into investments at month’s end. Treat it like the minimum balance in your account that you pretend doesn’t exist.
A Check-In That Fits a Monthly Cycle
A budget you set once and forget will drift. A budget you review for ten minutes each week stays honest.
The Weekly Ten-Minute Review
Pick a day. Sunday morning with coffee works for a lot of people. Wednesday evening works too. Consistency matters more than the day itself.
Here’s what to cover:
- Open your bank app. Note your current checking balance.
- Compare it to your weekly spending target. Are you ahead, behind, or on track?
- Look at the next seven days. Any bills about to hit? Any planned spending (dinner out, a kid’s field trip fee)?
- Adjust next week’s target if this week ran over or under.
- Update your balances in whatever tool you use. In Amppfy, this takes about 30 seconds per account, and your Safe-to-Spend refreshes immediately.
That’s it. Five steps. No spreadsheet formulas. No hour-long reconciliation.
The End-of-Month Snapshot
On the last day of the month, take five extra minutes. Write down three things:
- How much cushion you have left (did you dip into it?)
- Whether you hit your savings goal
- One thing you’d adjust next month
This isn’t a performance review. It’s a course correction. Maybe you find that your grocery estimate is consistently $40 short. Adjust the number. Maybe subscriptions crept up by $15. Cancel one or accept the cost and reduce something else.
Couples benefit from doing this together. If you share bills, you need to see the same number. A shared Safe-to-Spend means one partner doesn’t accidentally spend what the other already committed to a bill.
Frequently Asked Questions
What if my bills aren’t evenly spread across the month?
Most people’s bills cluster in the first half of the month. That’s actually ideal for a monthly pay budget. Move as many due dates as possible to the first week after payday. Call each creditor and ask to shift your due date. Most utilities, insurance companies, and lenders will accommodate this at no charge. Once your bills clear early, the remaining balance is genuinely available for the rest of the month.
Should I use a separate account for bills?
It helps. A common setup is three accounts: one for bills (fixed costs get transferred here on payday), one for daily spending (your weekly allowance), and one for savings. This way, your spending account only holds money you can actually use. You never accidentally spend the rent. The downside is managing multiple accounts, but most banks offer free checking, and the clarity is worth the minor hassle.
How do I handle annual or quarterly expenses on monthly pay?
Divide the annual cost by 12 and set that amount aside each month. Car registration is $180 a year? That’s $15 a month into a sinking fund. Holiday gifts run $600? That’s $50 a month. Add these monthly amounts to your fixed costs before calculating your spending money. They’re predictable expenses disguised as surprises.
What happens when I get a raise or bonus?
Don’t increase your weekly spending allowance immediately. First, check your cushion. Is it at 10-15%? If not, top it up. Next, check your savings goals. Are you on track? If not, increase the contribution. Only after both are solid should you raise your weekly spending. A $200 monthly raise split across four weeks is $50 more per week, which feels small but compounds into real quality-of-life improvement over time.
Making Monthly Pay Work for You
A single paycheck stretched across 30 days doesn’t have to feel like a countdown. The structure is simple: subtract your bills and savings first, split what remains into weekly chunks, keep a cushion you don’t touch, and check in for ten minutes each week.
The hardest part is the first month. You’re building a new habit and discovering where your estimates were off. By month two, the numbers get more accurate. By month three, you stop guessing.
If you want a tool that does the subtraction for you and shows one clear number every time you open it, Amppfy is free and takes about ten minutes to set up. Enter your balances, bills, and paydays, and your Safe-to-Spend updates on its own. Take ten minutes this week to map out your fixed costs and find your real number. That’s the only step that matters right now.