
You know what your money did last month. You’ve got the bank statements, the credit card totals, maybe a spreadsheet with rows that scroll past the screen. But can you actually see it? A budget pie chart turns all those numbers into a single picture: four or five colored slices that tell you, in about two seconds, where your paycheck went. That picture is worth more than any column of figures because your brain processes shapes faster than digits. If you’ve ever stared at a spreadsheet and still felt unsure whether the month went well, this is the fix. Below, you’ll find how to read the chart, what each slice should hold, and how to build one without burning your Sunday.
Why One Picture Beats a Spreadsheet
Spreadsheets are precise. They’ll show you $47.32 at Costco on March 9th. But precision isn’t the same as understanding. A pie chart for your budget trades that detail for something more useful: proportion.
One glance at a circle tells you that rent ate half your income or that subscriptions quietly grew to 8%. You don’t need to scroll, sum, or squint. For a monthly money check, speed matters because the goal isn’t accounting: it’s a quick answer to “Am I on track?”
There’s a design rule worth knowing here. Keep the chart to five slices or fewer. The human eye struggles to compare angles once you add a sixth or seventh wedge. Four slices is the sweet spot for a household budget: enough detail to be useful, few enough to read instantly.
A spreadsheet also hides emotional weight. Digital payments reduce the psychological visibility of spending[2], which means you may not feel how large a category has grown until you see it drawn to scale. The chart makes the invisible visible, and it does it without shame or alarm. It’s just geometry.
The Four Slices and What Each One Means
A useful budget chart needs categories that match how money actually leaves your account. Four slices cover most households cleanly.
| Slice | What Goes In It | Typical Range |
|---|---|---|
| Bills | Rent/mortgage, utilities, insurance, minimum loan payments | 40-55% |
| Savings | Emergency fund, retirement, sinking funds, debt payoff above minimums | 10-20% |
| Subscriptions | Streaming, gym, apps, meal kits, any auto-renewing charge | 3-8% |
| Everyday Spending | Groceries, gas, dining, clothes, entertainment, gifts | 25-40% |
Bills
This is the non-negotiable slice. Rent, car payment, electric bill, insurance premiums. If missing it triggers a late fee or a shutoff notice, it belongs here. This slice is usually the largest, and that’s fine. The point isn’t to shrink it to zero: it’s to know exactly how much of your paycheck is spoken for before you do anything else.
Savings
Think of this slice as money you’re paying to your future self. It includes your emergency fund contributions, 401(k) deposits beyond the employer match, and any goal you’re building toward (vacation, car repair fund, down payment). Only 35% of non-retirees believe their retirement savings are on track, a figure that’s held flat since 2024 despite market gains[3]. A visible savings slice reminds you it exists every time you look at the chart.
Subscriptions
Subscriptions deserve their own slice because they’re sneaky. Each one is small. Together, they can quietly claim 8% of your income. Pulling them out of “everyday” spending forces you to see them as a group.
Everyday Spending
Everything else. Groceries, coffee, Target runs, haircuts. This is the slice you have the most control over, and it’s the one that shifts month to month.
Amppfy’s Budget page shows your month as exactly these four slices, drawn from the plan you already entered: bills, savings, subscriptions, and everyday spending. No extra setup required.
Reading a Month That Looks Wrong
The real power of a pie chart isn’t when things go right. It’s when something looks off and you can spot it in two seconds.
Here’s what to watch for:
- Everyday spending swallows the circle. If that slice is pushing past 45%, your bills-and-savings structure may be too thin, or an irregular expense hit (car repair, medical bill). Check whether it’s a one-time event or a pattern.
- Subscriptions grew a wedge. A slice that was 4% three months ago and now reads 7% means two or three new auto-charges crept in. Cancel what you forgot you signed up for.
- Savings disappeared. A razor-thin savings slice, or none at all, means you skipped contributions. That’s a signal, not a verdict. The next step is to set a small automatic transfer, even $25, so the slice reappears next month.
- Bills exceed 55%. This can happen after a rent increase or a new car payment. It doesn’t mean you failed. It means the other three slices need to adjust, and the chart shows you exactly how much room is left.
The chart won’t fix any of these problems. But it shows you where to look, and it does it without a wall of red numbers or guilt-heavy alerts. A calm picture, a clear signal, a next step. That’s the whole process.
If you’re building a household budget from your existing plan, seeing the month as a circle makes the conversation with a partner much simpler. You’re pointing at shapes, not arguing over line items.
Comparing This Month to Last Month
A single month’s chart is useful. Two months side by side is where real insight shows up.
Place January’s circle next to February’s. You don’t need exact numbers to notice that the everyday-spending slice grew or that savings shrank. Your eye catches the difference in shape before your brain processes any digits.
Here’s a practical way to compare:
- Pick the same income base for both months. If you got a bonus in January, note it, but compare the regular-paycheck months to each other.
- Look at which slice changed the most. A 5% shift in one category usually explains the entire difference between a comfortable month and a tight one.
- Ask one question: “Was that shift a choice or an accident?” Choosing to spend more on a birthday trip is fine. Accidentally letting subscriptions balloon is not.
Over three or four months, you’ll start to see your spending personality. Maybe your everyday slice always spikes in December and dips in January. Maybe your bills slice dropped after you refinanced. These patterns only emerge when you look at the shape of the month, not the rows of a ledger.
For couples, this comparison is especially powerful. Two people looking at two circles can agree on what changed without either person feeling blamed. The chart is neutral. It just shows proportion.
Amppfy tracks your savings month by month and shows net worth over time, so the comparison happens automatically. Your weekly ten-minute check-in is enough to keep the data honest.
Making the Chart Without Building One Yourself
You don’t need to open a spreadsheet app, wrestle with chart wizards, or color-code cells. Several paths get you to a working budget pie chart in minutes.
The manual route
Open any free tool: Google Sheets, Apple Numbers, or a browser-based chart maker. Create four rows: Bills, Savings, Subscriptions, Everyday. Enter dollar amounts. Insert a pie chart. Done. The downside is that you’ll repeat this process every month, and you’ll need to categorize transactions yourself.
The app route
Most budgeting apps generate a spending chart from your transactions. The catch is that many require bank login credentials, and the personal finance market is shifting toward privacy-preserving designs[4] that avoid storing sensitive data on cloud servers long-term. If privacy matters to you, look for tools that don’t require bank sync.
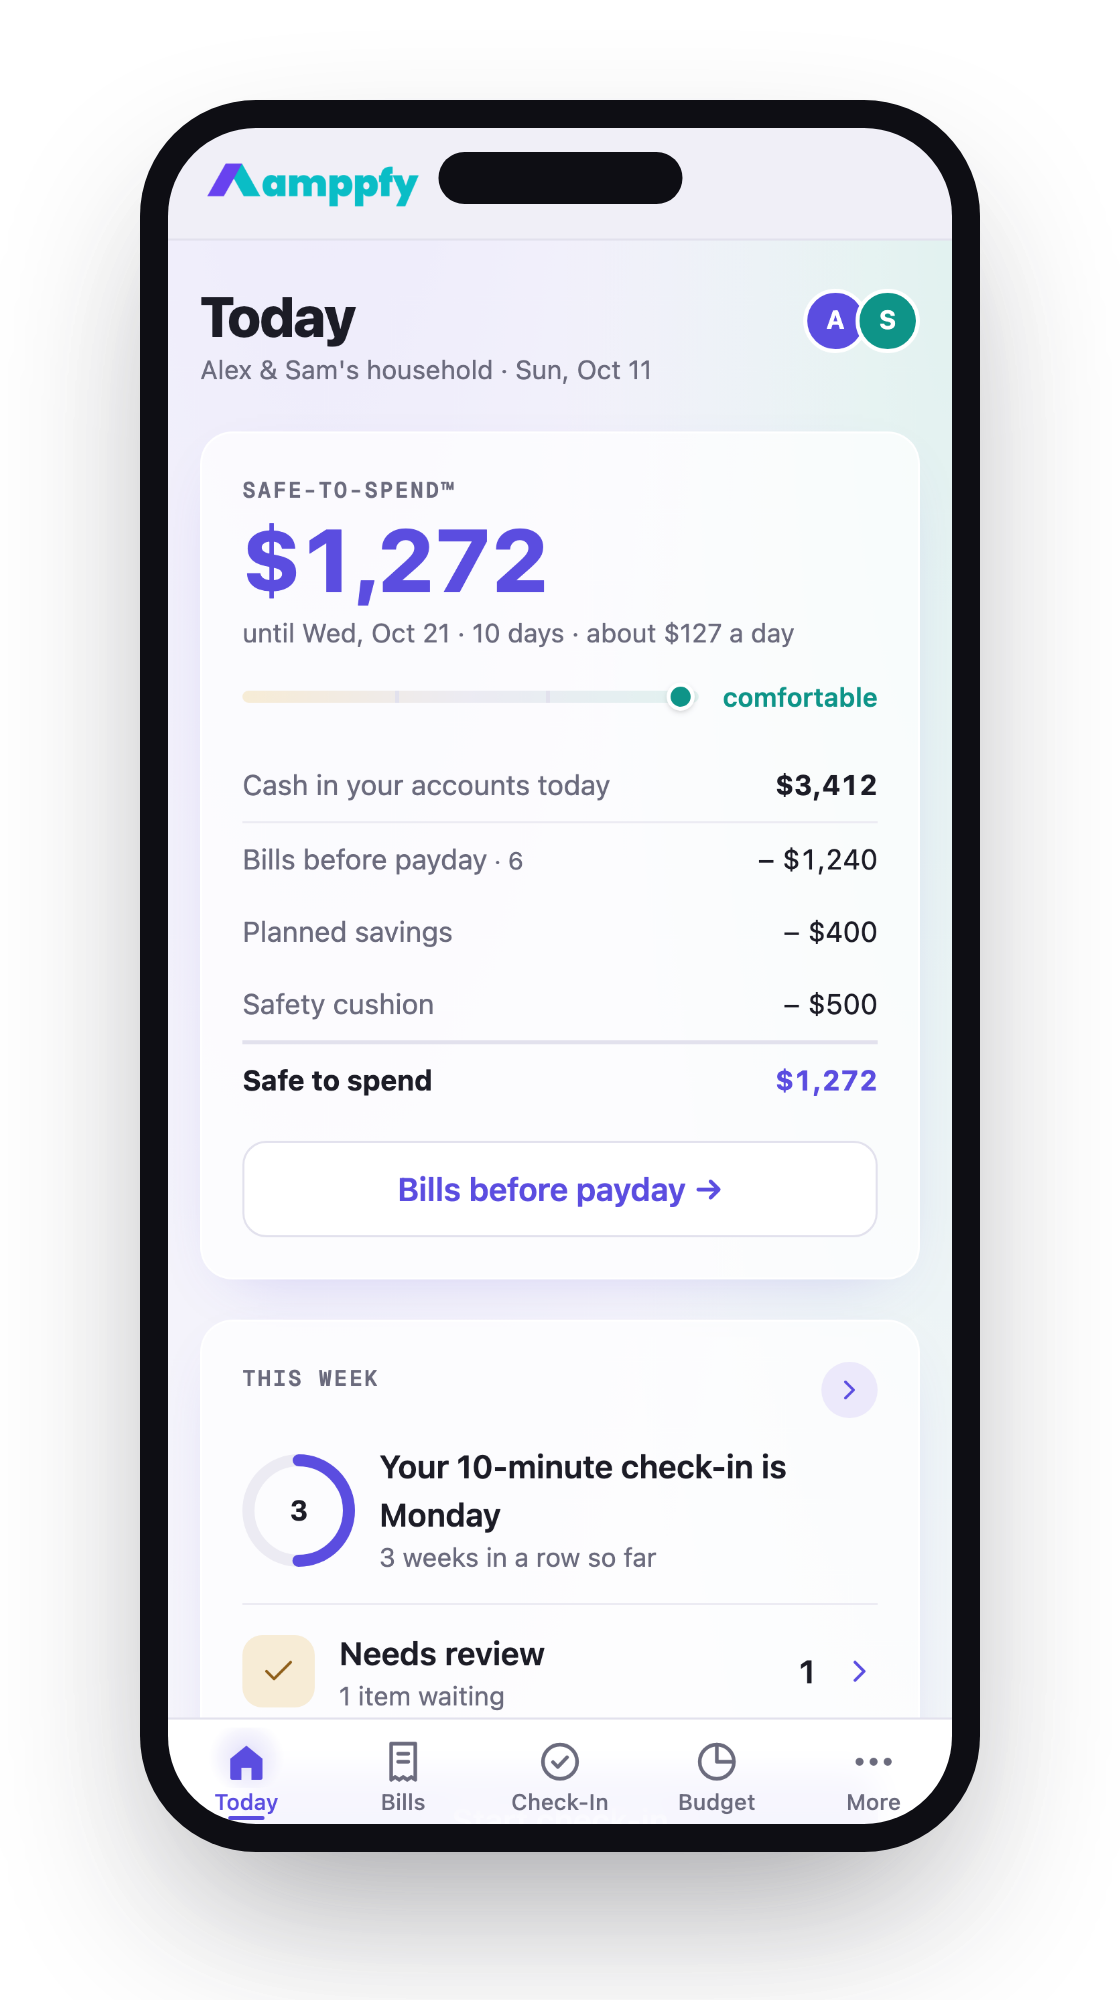
Amppfy takes a different approach. You type in your balances yourself, about 30 seconds per account, and the app builds the chart from the bills, savings goals, and subscriptions you’ve already entered. No bank login needed. The Budget page draws your four slices automatically, and your Safe-to-Spend™ number sits right alongside it: $3,412 cash − $1,240 bills − $400 savings − $500 cushion = $1,272.
Tips for either route
- Update your numbers on the same day each week. Consistency beats precision.
- Don’t create more than five slices. Merge small categories into “Everyday.”
- Save or screenshot last month’s chart before updating. You’ll want the comparison.
Frequently Asked Questions
How often should I update my budget pie chart?
Once a week is plenty. Pick a day, spend five to ten minutes updating your balances, and glance at the chart. Monthly updates work too, but weekly check-ins catch problems before they compound. The goal is a rhythm you’ll actually keep, not a chore you’ll abandon by March.
What if my income changes month to month?
Use your lowest typical paycheck as the baseline. Variable income makes the chart even more valuable because it shows you how your spending proportions shift when a bigger or smaller check arrives. If you freelance or work overtime, treat the extra as a bonus and watch whether it inflates everyday spending or lands in savings.
Should I include debt payments in the Bills slice or the Savings slice?
Minimum payments belong in Bills: they’re non-negotiable. Any extra payments above the minimum go in Savings because that’s a choice you’re making to pay down debt faster. This split keeps your Bills slice honest and gives your Savings slice credit for the extra effort.
Can two partners use the same chart?
Yes, and it works best when you do. A shared chart shows combined household proportions without requiring either person to reveal every transaction. You’re looking at slices, not individual purchases. If you use Amppfy, both partners get their own login and see the same Safe-to-Spend™ number while private balances stay private.
Your Month, One Circle
A budget pie chart does one thing well: it turns a month of money into a shape you can read in seconds. Four slices, five at most. Bills, savings, subscriptions, everyday spending. When a slice looks too big, you know where to look. When two months sit side by side, you see whether things are improving. No scrolling, no formulas, no guilt.
If you want to see your own Safe-to-Spend™ number alongside that chart before your next payday, Amppfy is free on iPhone and the web. Enter your balances, bills, and payday once, about ten minutes, and the number stays current from there. Get Amppfy free and turn your next month into one picture worth keeping.