
Most people who’ve tried budgeting on their phone have a familiar story. You download an app, connect your bank, categorize a few transactions, and then quietly stop opening it two weeks later. Finding the right free budget app for your iPhone isn’t really about features: it’s about finding something you’ll actually use past the first month. That means understanding what “free” actually costs you, what each app does well, and which one fits the way you and your household handle money. This guide compares three free options and one popular app that’s often assumed to be free, explains the trade-offs behind each free tier, and helps you pick one that sticks.
What free really means in a budget app
“Free” on the App Store doesn’t mean much by itself. Every app has to pay for servers, developers, and support. The question is how they cover those costs when you’re not paying a subscription. Knowing the business model tells you what to expect long-term.
Ad-supported vs. freemium vs. manual
Some apps show ads. Others give you a limited free plan and charge for extras. A few make money through affiliated financial products or wealth management services. One free personal finance dashboard, for example, also sells paid advisory services, with its entry tier starting at $100,000 invested. That’s a perfectly fine model: you just need to know it exists so you can evaluate the recommendations you see inside the app.
The manual-entry approach
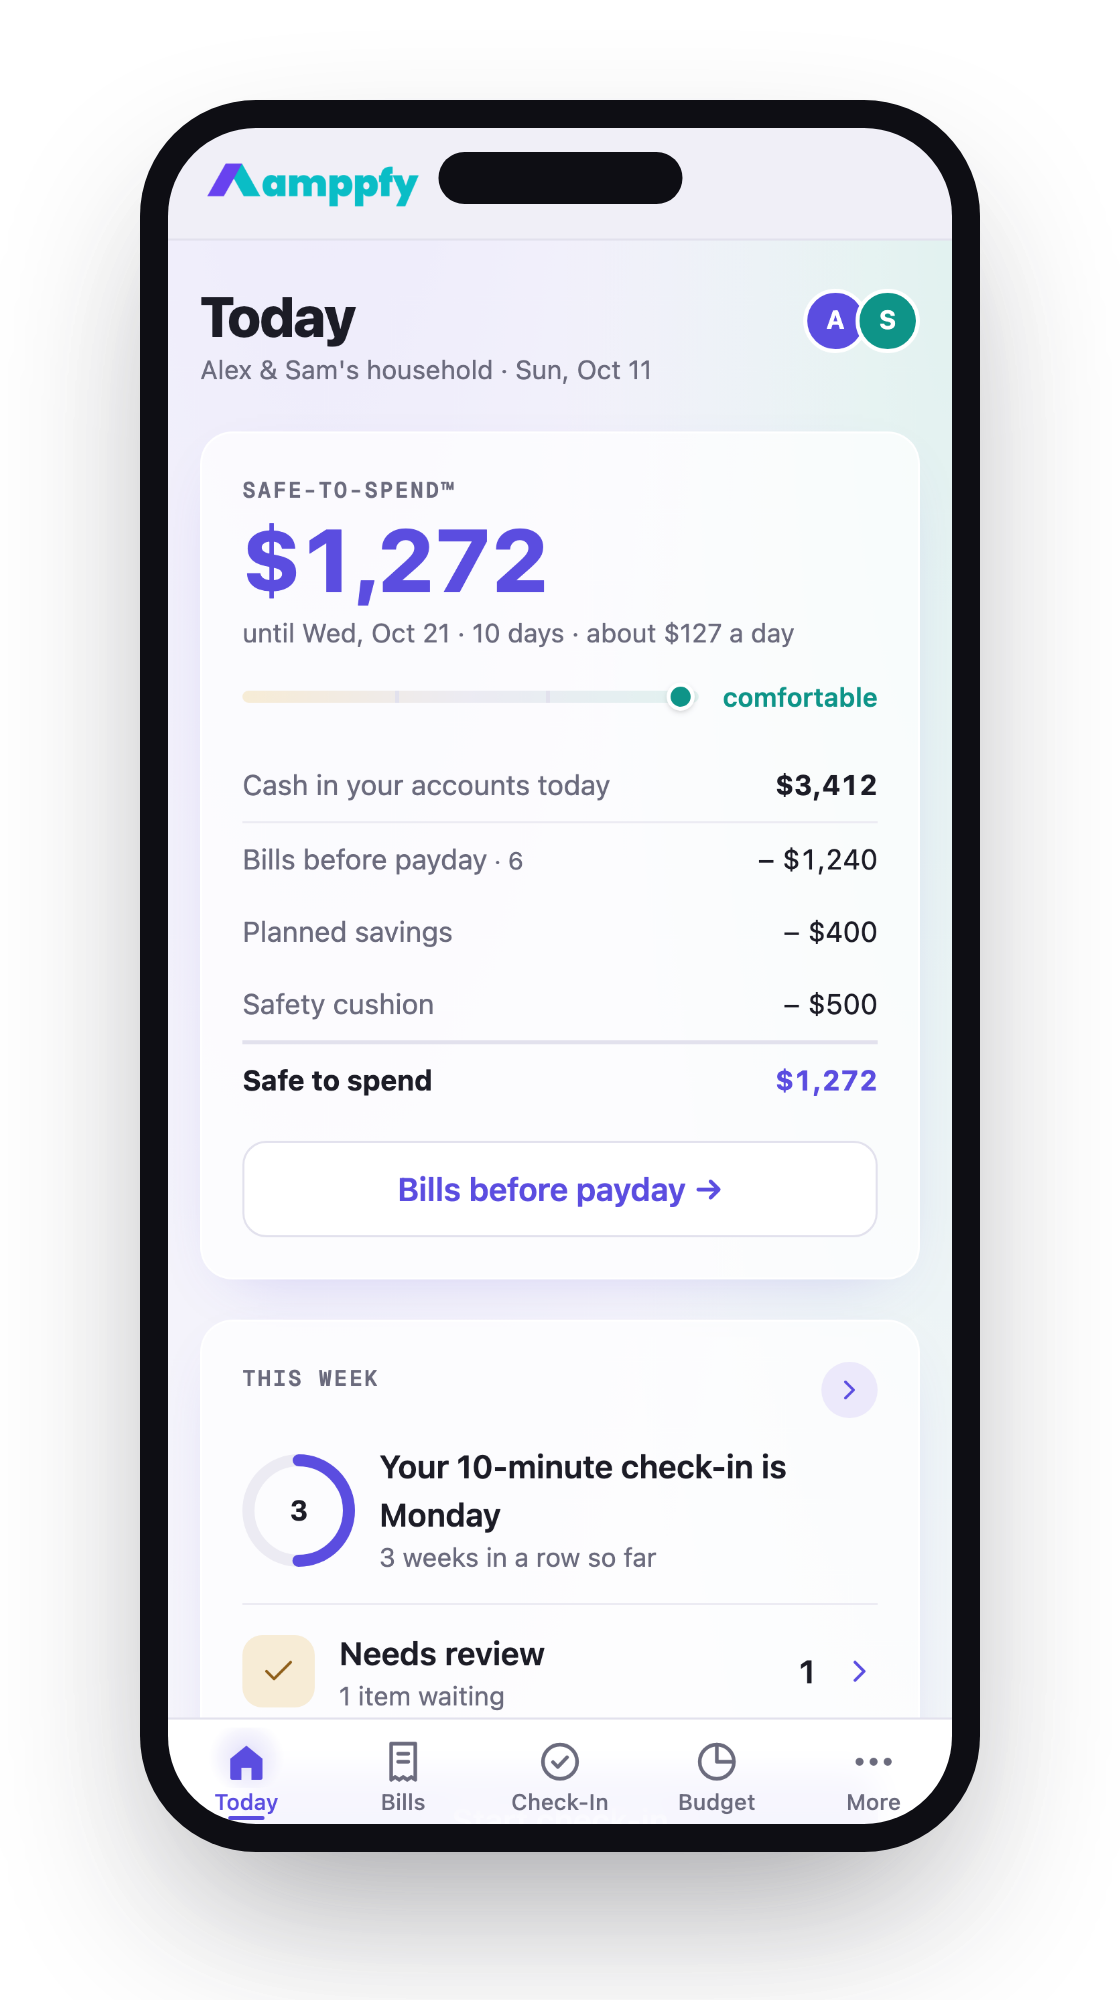
A different model skips bank connections entirely. You type in your balances yourself. There’s no bank-data connection to pay for, which makes a free product easier to offer. Amppfy works this way: it’s free on iPhone and the web, you enter your balances by hand along with bills, paydays, and savings goals, and it shows one Safe-to-Spend™ number with the four-line math printed underneath. The trade-off is that you do the typing.
Why the business model matters to you
If an app’s revenue depends on upselling you, expect nudges toward a paid tier. If it depends on managing your investments, expect prompts to link brokerage accounts. Neither is bad. But knowing the incentive helps you judge whether a feature is there for you or for the company’s revenue target.
The apps, compared
Here’s a side-by-side look at four iPhone budget apps people often consider when they want to pay nothing. Each takes a different approach to the same problem: helping you know what’s safe to spend. Prices and plan limits are from each app’s own website as of October 2026.
| Feature | EveryDollar | Goodbudget | PocketGuard | Amppfy |
|---|---|---|---|---|
| Method | Zero-based budget | Envelope budgeting | Spending tracker (“leftover” money) | Safe-to-Spend™ number |
| Bank sync (free tier) | No (Premium only) | No (Premium only; file import is free) | No free tier | No (manual entry) |
| Couple/partner support | Household feature: one budget, separate emails | Sync and share a budget across household devices | Not stated on its site | Invite a partner by email |
| Free plan limits | Manual tracking only; Premium $17.99/mo or $79.99/yr | 20 envelopes, 1 account, 2 devices, 1 year of history; Premium $10/mo or $80/yr | No free plan: 7-day trial, then Plus $12.99/mo, $74.99/yr, or $149.99 lifetime | Free on iPhone and the web; no paid tier |
| Good fit for | Dave Ramsey followers | Cash-envelope fans | Quick spending snapshot | Paycheck-to-paycheck clarity |
EveryDollar
EveryDollar uses zero-based budgeting. You assign every dollar of income to a category before the month starts. The free tier is manual-only: you log each transaction yourself. It’s clean and straightforward if you like the zero-based philosophy. The app is part of Ramsey Solutions, and bank connections, custom reports, and CSV export come with EveryDollar Premium ($17.99 a month or $79.99 a year, with a 14-day trial for new users).
Goodbudget
Goodbudget digitizes the classic envelope system. The free plan gives you 20 envelopes (10 regular plus 10 more), one account, two devices, and one year of history. You can type transactions in or upload a bank file (QFX, OFX, or CSV). A household can sync and share the same budget across devices. Premium ($10 a month or $80 a year) adds automatic bank sync for US banks, unlimited envelopes and accounts, and five devices. It works well for people who think in categories like “groceries” and “gas” rather than account balances.
PocketGuard
PocketGuard shows what’s left after bills, debt, savings, and goals, usually by connecting your accounts (its site says you can also track manually). It’s on this list because many people assume it’s free, but it has no permanent free tier. You get a seven-day free trial, then PocketGuard Plus costs $12.99 a month, $74.99 a year, or $149.99 once for lifetime access. If you want a free app, plan to cancel before the trial ends or pick one of the others.
Free plan limits to watch
Every free tier has boundaries. Some are obvious, like a cap on categories. Others only show up after you’ve invested time setting things up. Here’s what to watch for before you commit.
- Category or envelope caps. Goodbudget’s 20-envelope limit works for simple budgets but gets tight if you split spending into detailed subcategories.
- No bank sync on free tiers. EveryDollar and Goodbudget both keep bank sync for their Premium plans; the free plans rely on manual entry (Goodbudget also takes bank-file uploads). That’s not necessarily a downside: manual entry forces you to stay aware of your spending. But it’s a real time commitment if you have many accounts.
- Upsell pressure. Watch for features that appear available but require a subscription to actually use. A “bill negotiation” button that leads to a paywall, for instance, isn’t really a free feature.
- Data export restrictions. Some apps lock CSV or spreadsheet exports behind a paid tier. If you want to keep your own records, check this before you start.
- Partner access. Check how sharing works before you invite a partner. EveryDollar’s household feature uses separate emails for one shared budget, and Goodbudget syncs one budget across household devices. In both cases you’re looking at the same budget.
The honest test: can you run your full monthly budget on the free plan without hitting a wall? For simple budgets on EveryDollar or Goodbudget, often yes. PocketGuard doesn’t have a free plan to test, only a seven-day trial.
Privacy and data
Your budget app knows a lot about you: income, debts, spending habits, bill amounts. That makes privacy worth a few minutes of thought before you sign up.
Bank-linked apps
Apps that sync with your bank usually connect through a data provider. PocketGuard, for example, lists Plaid, Finicity, and Salt Edge on its pricing page. That’s a normal setup, but it means a third company sits between your bank and your budget, so it’s worth knowing who it is and what they keep.
Manual-entry apps and data exposure
Apps that don’t connect to your bank hold less sensitive data by design. They know your balances and bill amounts but don’t have your bank credentials or transaction history. That’s a meaningful difference if data breaches concern you. The trade-off is convenience: you’re doing the data entry yourself.
What to check before signing up
- Read the privacy policy’s data-sharing section. Look for language about selling or sharing data with “marketing partners.”
- Check whether the app stores your bank credentials directly or uses a third-party aggregator.
- Look for an option to delete your account and data entirely.
Choosing one for your household
The best free budget app for your iPhone depends on how your household handles money, not on which app has the longest feature list.
Singles on a regular paycheck
If you get paid every two weeks and want one answer to “what can I spend before Friday?”, a Safe-to-Spend™ approach works well. You don’t need 50 categories. You need one reliable number. Amppfy shows that number with the math underneath. For example: $3,412 cash minus $1,240 bills minus $400 savings minus $500 cushion equals $1,272. You update the balances by hand when you check in.
Couples with shared and separate money
The biggest friction point for couples isn’t the app: it’s agreeing on what’s shared. Settle which bills and accounts are shared first. Then check what each person will see in the app, because most shared budgets show both of you the same plan. In the Safe-to-Spend™ app above, each partner gets their own login by email invite: shared accounts and bills are visible to both of you, and anything you keep private stays private.
Envelope-budget fans
If you’ve used cash envelopes before and want a digital version, Goodbudget is a natural fit. Its free plan’s 20 envelopes can cover a simple budget. The mental model is familiar: when an envelope is empty, you stop spending in that category.
People who quit a budget app before
If you’ve abandoned a budgeting app because of upkeep, broken bank sync, or a price hike, your priority should be simplicity and cost. Pick the app with the fewest moving parts. Manual entry with a small number of inputs beats a complex system you won’t maintain.
Frequently Asked Questions
Is a free budget app on iPhone really enough, or do I need a paid plan?
For most people on a regular paycheck, yes. The free plans of EveryDollar and Goodbudget cover basic budgeting, and the manual-entry Safe-to-Spend™ app above is free on iPhone and the web. PocketGuard has no free plan, only a seven-day trial. If your finances are straightforward: steady income, predictable bills, a savings goal or two: a free app handles it.
Are budget apps that connect to my bank safe to use in 2026?
Many people use them without trouble, but any bank connection creates a data relationship you should understand, including which data provider the app uses. Read the app’s privacy policy before linking accounts.
How much time does a manual-entry budget app take each week?
It depends on the method. Apps where you log each purchase take longer than apps where you only type in balances. For a balance-based app, you open your bank app, glance at the balance, and type it in, then look over upcoming bills and goals. In the Safe-to-Spend™ app above, that’s about 30 seconds per account, and the weekly check-in takes about ten minutes.
Can my partner and I use the same budget app without seeing each other’s personal spending?
Usually a shared budget means both partners see the same budget. The manual-entry app above is an exception worth knowing: each of you has your own login, shared accounts and bills show for both, and anything you keep private stays private. If you keep some money separate, decide which accounts and bills go into the shared plan before you invite your partner.
Pick the app you’ll actually open next Tuesday
Features don’t matter if the app sits unopened on your second home screen. The right choice is the one that fits your habits, your household, and your patience level. Try one for a full pay cycle before you judge it. That’s two weeks of real use, not an afternoon of setup.
If you want to see your own Safe-to-Spend™ number before your next payday, Amppfy is free on iPhone and the web. Enter your balances, bills, and paydays by hand, and update the balances when you check in. Get the app free and give it one pay cycle.