Close Menu

    Subscribe to Updates

    Get the latest creative news from FooBar about art, design and business.

    What's Hot

    Average Money Left Over After Bills in 2026: What the Numbers Say and Why Yours Differs

    October 17, 2026

    Disposable Income: What It Means, and What’s Actually Yours to Spend

    October 17, 2026

    How Much Money Should You Have Left After Bills? A Per-Paycheck Answer

    October 17, 2026
    Facebook X (Twitter) Instagram
    Amppfy
    • Safe to Spend™ App
      • Amppfy on iPhone — one clear number with the status scale and the math under itYour number, in your pocketFree on iPhone, with the same account on the web.
        • Download on the App Store
        • Prefer the web? Sign up free ›
      • The app
        • OverviewOne clear number for what’s safe to spend before payday
        • Safe-to-Spend™The four-line math, always shown
        • Weekly check-inTen minutes a week keeps it honest
      • Features
        • Bills & paydaysEvery bill and payday on one calendar
        • GoalsSavings that fund themselves first
        • For couplesTwo logins, one number you both trust
        • SubscriptionsWhat you pay monthly, and what cancelling gives back
        • Calendar & heads-upsYour month at a glance, a heads-up before bills land
        • Net worth & payday nudgeThe whole picture, month by month
        • BudgetWhere the month’s money goes, month by month
      • Trust & help
        • Security & privacyJust your balances, optional two-step verification
        • Help centerSetup, the number, check-ins, FAQ
        • Open the web appSame account, any browser
    • Personal Finance
      • Money Basics
        • How to Master Money Management
        • Psychology of Money Habits
        • How to Set Financial Goals
        • Money Management for Every Life Stage
        • Beyond Budgeting: Advanced Money Skills
        • Financial Literacy
        • Money Management
        • Know Your Money
        • Cash Flow
      • Financial Wellness
        • Understand Your Money Relationship
        • Build a Healthy Money Mindset
        • 7 Money Tips for Financial Freedom
        • Take the Money Health Quiz
        • Monthly Financial Reviews
        • Money Habits
        • Money Mindset
        • Financial Goals
        • Financial Independence
      • Side Hustles & Extra Income
        • 8 Realistic Side Hustles
        • How to Make Money Online
        • Passive Income Ideas That Work
        • Passive Income 101: Ideas That Scale
        • Spot a Bad Passive Income Deal
        • Start Freelance Writing: First $1,000
        • Budgeting with Irregular Income
        • Side Hustle Ideas
        • Passive Income
        • Gig Economy
      • Major Money Decisions
        • Plan a Major Purchase Without Debt
        • Car Buying: Save, Finance, or Lease?
        • Used Car Buying & Negotiation Tips
        • What to Save For vs. Finance
        • Life Insurance 101: Coverage Needs
        • Term vs. Whole Life Insurance
        • Buying a Car
        • Major Purchase Planning
        • Home Improvement
        • Life Insurance
      • Money Tools & Calculators
        • Net Worth Calculator
        • Cost of Living Calculator
        • Compound Interest Calculator
        • Monthly Budget Calculator
        • Savings Goal Calculator
        • Emergency Fund Calculator
        • Savings Calculator
        • Do Money Management Tools Work?
        • Spend Tracking
        • Net Worth
    • Savings
      • Budgeting Tips
        • The 50/30/20 Rule Explained
        • How to Make a Monthly Budget
        • How to Budget Money in 5 Steps
        • The Envelope Method Explained
        • Best Budgeting Apps Compared
        • Common Budgeting Mistakes
        • Budgeting for Couples
        • Start a Budget
        • Budget Methods
        • 50/30/20 Budgeting
      • Ways to Save
        • Save $500 This Month
        • 14 Ways to Cut Monthly Expenses
        • How to Save Money on Groceries
        • Lower Your Utility Bills
        • Budget Swaps for Big Purchases
        • Save Money on Car Insurance
        • Cut Expenses
        • Groceries Savings
        • Smart Saving Strategies
      • Emergency Fund
        • How Much Emergency Fund to Save
        • How to Build an Emergency Fund
        • Start a Rainy Day Fund
        • Sinking Funds vs. Emergency Fund
        • Emergency Fund Essentials
        • Where to Keep Your Emergency Fund
        • Best Emergency Fund Tips
        • Emergency Savings
        • Emergency Buffer
      • Savings Goals & Plans
        • How to Create a Savings Plan
        • How to Set Savings Goals
        • Track Spending Without Spreadsheets
        • 529 College Savings on a Budget
        • Saving During a Recession
        • Budget a Debt-Free Vacation
        • Vacation Budgeting
        • Family Budgeting
        • Savings Goals
        • Recession Saving
      • Savings Tools & Planning
        • Budget Calculator
        • Savings Goal Calculator
        • Emergency Fund Calculator
        • Savings Calculator
        • Compound Interest Calculator
        • Savings Buckets
        • Sinking Funds
        • Maximize Your Savings
        • Savings Tips
        • Savvy Saver
    • Debt
      • Get Out of Debt
        • Debt Snowball vs. Avalanche
        • Pay Off Credit Card Debt Fast
        • Beginner’s Credit Card Payoff Plan
        • Build a Debt Payoff Calendar
        • Use Windfalls to Crush Debt
        • Debt Free Journey
        • Debt Payoff
        • Credit Card Debt
      • Student & Auto Loans
        • Student Loans 101
        • Get Out of Student Loan Debt
        • Income-Driven Repayment Plans
        • Best Student Loan Repayment Option
        • Auto Loans: Shop & Save on Interest
        • Pay Off Your Auto Loan Early
        • Student Loans
        • Auto Loans
        • Auto Loan Debt
      • Debt Consolidation
        • Debt Consolidation Pros & Cons
        • Is Consolidating Debt Right for You?
        • Balance Transfers to Pay Off Debt
        • HELOC to Pay Off Credit Cards
        • 401(k) Rollover to Pay Down Debt
        • How to Refinance a Personal Loan
        • Before You Take a Personal Loan
        • Personal Loans
        • Personal Loan Refinance
      • Managing Debt
        • Navigating Medical Debt
        • Budgeting with a High-Interest Loan
        • Build a Debt-Repayment Fund
        • Debt Payoff for Single Parents
        • Save for a Wedding Without Debt
        • Medical Debt
        • Single Parent Debt
        • Personal Loan Debt
      • Debt Relief & Protection
        • When Bankruptcy Is an Option
        • Avoid Predatory Lenders & Scams
        • Negotiate with Creditors: Scripts
        • Budgeting Around Wage Garnishment
        • Debt Relief
        • Bankruptcy
        • Creditor Negotiation
        • Predatory Lenders
        • Wage Garnishment
    • Credit
      • Credit Scores
        • Credit Score 101
        • Check & Improve Your Credit Score
        • Credit Utilization: A Simple Fix
        • Check Your Credit Score Free
        • Rebuild Credit After a Setback
        • How Credit Scores Are Calculated
        • What Credit Scores Mean
        • Credit Health
      • Credit Reports
        • Read & Dispute Your Credit Report
        • Dispute Template That Works
        • How Long Negative Marks Last
        • Remove Negative Items
        • What to Expect as Items Age Off
        • Understanding Credit Utilization
        • Credit Basics
        • Checking Your Credit Score
      • Building Credit
        • Best Starter Credit Cards
        • Secured vs. Unsecured Cards
        • Secured Cards & Credit-Builder Loans
        • Build Credit as a Gig Worker
        • Boost Your Score Before a Mortgage
        • Borrow Now vs. Wait
        • Build Credit
        • Credit Cards for Beginners
        • Credit for Gig Workers
      • Credit Cards
        • Best Rewards Credit Cards
        • Credit Card Hacks: Intro APRs
        • Balance Transfers Explained
        • Earn Rewards Without Debt
        • Responsible Card Use & Rewards Tips
        • Lost or Stolen Card: What to Do
        • Credit Card Rewards
        • Balance Transfer Cards
      • Credit Protection & Safety
        • Identity Theft Checklist
        • Truth About Credit Freezes
        • How to Freeze & Thaw Your Credit
        • Credit Monitoring vs. Freezes
        • Credit Protection
        • Credit Freeze
        • Fraud Awareness
        • Financial Safety
    • Investing
      • Start Investing
        • Investing 101: Beginner’s Guide
        • Start Investing with $100
        • Start with $50/Month
        • Scared of the Market? Start Here
        • Open a Brokerage Account
        • Invest While Paying Down Debt
        • How to Start Investing
        • Start with Little Money
        • Fear of Investing
      • Investing Strategy
        • Roth IRA vs. Traditional IRA
        • Dollar-Cost Averaging Explained
        • DCA vs. Lump-Sum Investing
        • 5 Simple Starter Portfolios
        • Asset Allocation Beyond 60/40
        • How to Rebalance Your Portfolio
        • Diversify Your Portfolio
        • Investing Mistakes to Avoid
        • Investment Strategies
        • Diversification
      • Stocks
        • How the Stock Market Works
        • How to Make Money in Stocks
        • How to Read Stock Charts
        • Analyze Stocks in 5 Steps
        • P/E Ratio for Beginners
        • Bullish vs. Bearish Explained
        • How Stock Trading Works
        • Stock Market Basics
        • Stock Analysis
        • Stock Trading Strategies
      • Funds & Wealth Building
        • Beginner’s Guide to Index Funds
        • Best S&P 500 Index Funds
        • Mutual Funds vs. ETFs
        • How to Invest in ETFs
        • Dividend Investing for Beginners
        • Build a Dividend Income Stream
        • Maximize Your 401(k) Match
        • Build a Retirement Portfolio
        • Index Funds
        • Dividend Investing
      • Brokerages & Platforms
        • Vanguard vs. Fidelity
        • Fidelity vs. Schwab
        • Robinhood vs. E*Trade
        • Robo-Advisors vs. Human Advisors
        • Robo-Advisor or DIY Investing?
        • How Brokerage Fees Affect Returns
        • Manage Multiple Brokerage Accounts
        • Brokerages
        • Investment Platforms
        • Robo Advisors
    • Home
      • Home Buying
        • First-Time Homebuyer Checklist
        • How Much Down Payment You Need
        • How Much Home Can You Afford?
        • Renting vs. Buying
        • True Costs of Homeownership
        • Qualify as a First-Time Buyer
        • Buying a Fixer-Upper
        • First-Time Home Buyer
        • Home Affordability
      • Mortgage
        • First-Time Buyer’s Mortgage Guide
        • Fixed vs. Adjustable Mortgage
        • How to Refinance a Mortgage
        • Mortgage Payoff Strategies
        • Winning in a High-Rate Market
        • Mortgage Amortization Calculator
        • Down Payment Assistance Programs
        • Mastering Refinance Rate Locks
        • Mortgage Rates
        • Mortgage Refinance
        • Debt-to-Income Calculator
      • Real Estate Investing
        • Real Estate Crowdfunding Platforms
        • Rental Property Cash Flow
        • REITs for Passive Income
        • REITs vs. Direct Ownership
        • Fix-and-Flip Opportunities
        • Airbnb & Short-Term Rental ROI
        • Buying a Multi-Family Property
        • 1031 Exchange to Defer Taxes
        • Real Estate Investing
        • Rental Property
      • Home Insurance
        • Homeowners Insurance Guide
        • Compare Home Insurance Quotes
        • Best Home Insurance Companies
        • Choose Your Deductible
        • Renters vs. Homeowners Insurance
        • File a Property Insurance Claim
        • Home Insurance Coverage Basics
        • Home Insurance Rates
        • Home Insurance Claims
      • Home Equity & Ownership
        • Smart Ways to Use Home Equity
        • Save for a Down Payment
        • Down Payment Strategies
        • Estimate Property Appreciation
        • Home Equity
        • HELOC Payoff Strategy
        • Home Down Payment
        • Home Ownership
        • Home Renovation
    • Bank
      • Banking Basics
        • Open Your First Bank Account
        • Online Banks vs. Traditional Banks
        • How to Avoid Bank Fees
        • How to Switch Banks
        • Read Your Bank Statement
        • Second-Chance Checking Accounts
        • Get Better Rates from Your Bank
        • Banking Basics
        • How to Choose a Bank
        • Compare Banks
      • Checking Accounts
        • Best Checking Accounts
        • Choose the Right Checking Account
        • Overdraft Protection Guide
        • Stop Paying Overdraft Fees
        • The True Cost of Checking Fees
        • Mobile Check Deposits
        • How Long Checks Take to Clear
        • Checking Accounts
        • Best Checking Account
      • Savings Accounts & CDs
        • High-Yield Savings Explained
        • Best High-Yield Savings Account
        • Savings Accounts vs. CDs
        • What Is a CD?
        • Money Market vs. Savings Account
        • HYSA vs. Treasury Bills
        • How Savings Interest Is Calculated
        • Savings Account Minimum Balances
        • Savings Account
      • Bank Smarter
        • Top Banks for High-APY Savings
        • How Much Cash in Each Account
        • How Many Savings Accounts to Have
        • Managing Multiple Bank Accounts
        • Where to Put Your Money
        • When to Save vs. When to Invest
        • Savings Account Fees to Avoid
        • Banking Tips
        • Digital Banking
      • Banking Safety & Security
        • Set Up Bank Account Alerts
        • Avoid Check Scams
        • Missing Debit Card: Next Steps
        • When to Stop a Check Payment
        • Bank Fees
        • Debit Cards
        • Joint Bank Accounts
        • Banking How-To Guides
    • Sign In
    • Sign Up
    Amppfy
    Home » Banking » Pending Direct Deposit: What It Means and When You Can Spend It
    Banking

    Pending Direct Deposit: What It Means and When You Can Spend It

    Learn what a pending deposit means, when weekends delay it, and how to cover rent before the money unlocks.
    Thomas T.By Thomas T.October 17, 2026Updated:October 17, 202610 Mins Read
    Facebook Twitter LinkedIn Email Copy Link
    Pending Direct Deposit: What It Means and When You Can Spend It
    Share
    Facebook Twitter LinkedIn Email Copy Link

    Your banking app shows a new line near the top: a deposit, with “pending” next to it. The amount looks right. Payday is supposed to be today. But your available balance hasn’t moved, and rent comes out tomorrow morning.

    This moment is common, and it’s usually not a problem. A deposit in pending status is money on its way. It’s not money that vanished. The confusion comes from two numbers on the same screen telling slightly different stories.

    The goal here is plain. You’ll learn what that label means and which rules decide when the money unlocks. You’ll see how weekends shift the timing, and how to plan around the gap without stress. You’ll also learn why the balance you see once it clears still isn’t the number to spend from.

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

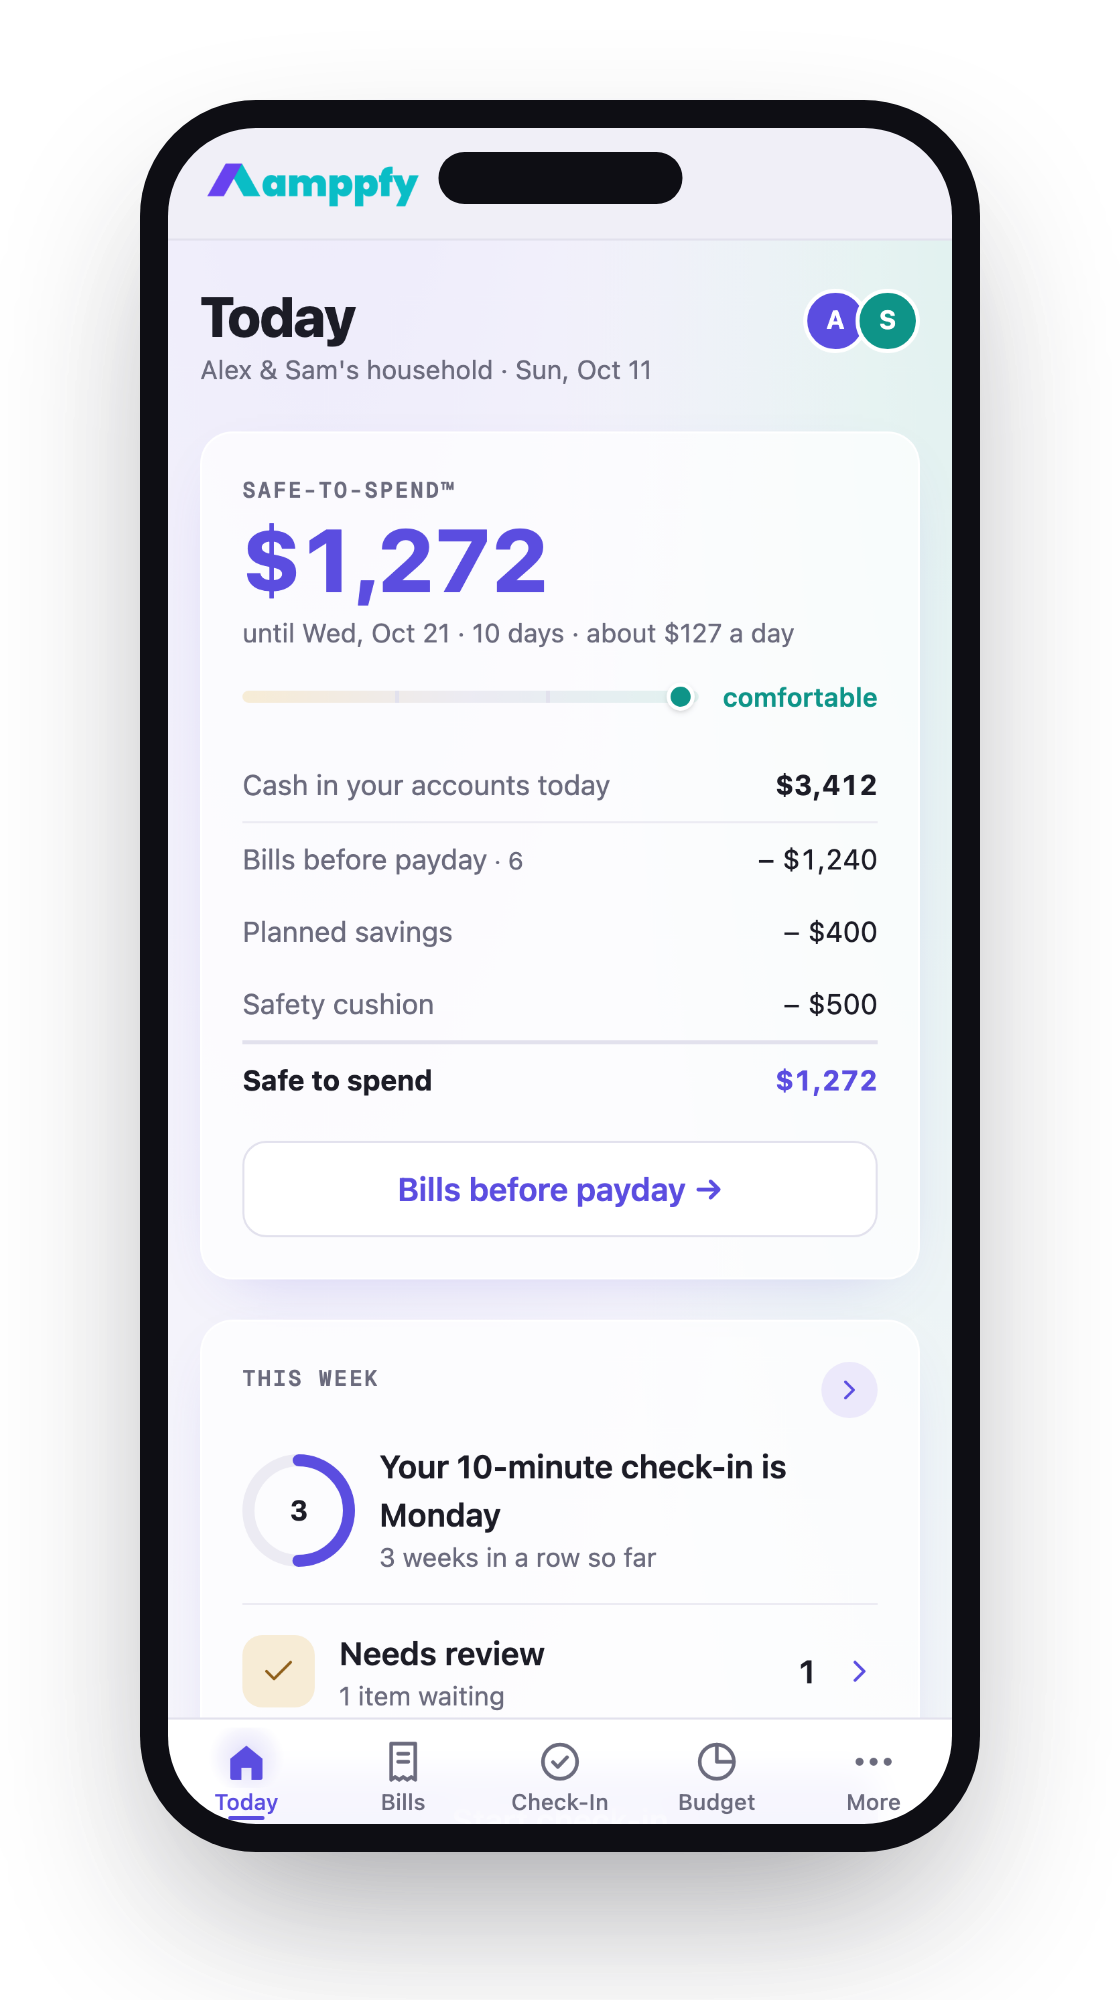
    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it

    If you’ve ever refreshed your bank app five times before 9 a.m. on payday, this is for you. The answer is calmer than it feels.

    The short answer

    A pending direct deposit is money your bank can see coming but hasn’t finished processing. You usually can’t spend it yet. Once it settles, it moves into your available balance.

    For electronic direct deposits like paychecks, federal rules set a ceiling on the wait. Under Regulation CC, the federal funds availability rule, electronic payments received for deposit must be available no later than the first business day after the banking day they’re received[1]. Many banks release funds sooner, based on their own policy.

    There’s also a network-level rule for the ACH system that carries most paychecks. As of September 18, 2026, banks must make standard ACH credit funds available for withdrawal by 9:00 AM local time on the settlement date[2]. The organization behind that rule put it simply: faster availability “provides a real benefit to receivers of ACH credits, such as employees”[3].

    Here’s what that means for you, as of October 2026:

    • Pending = seen, not spendable (in most cases)
    • Available = spendable now
    • Typical wait = hours, sometimes up to the next business day
    • Your bank’s policy = can be faster than the federal floor, never slower

    If your deposit shows pending on a weekday morning, the most likely outcome is that it clears that day.

    What ‘pending’ means for a deposit

    Think of a pending deposit like a package marked “out for delivery.” The tracking says it’s coming. You just can’t open it yet.

    When your employer runs payroll, they send a file through the ACH network a day or more ahead. Your bank receives notice that money is coming on a set date. Some banks show this as pending right away. Others wait until settlement and show nothing until it’s available.

    That’s the key difference from a pending purchase. A pending purchase is money leaving your account. The merchant has placed a hold, and your available balance usually drops right away, even before the charge is final. A pending deposit works the other way: money arriving that usually doesn’t add to your available balance until it settles.

    So the two can feel lopsided. Spending shows up fast. Income shows up slow. That’s normal, and it’s by design. Banks protect themselves from releasing money that might bounce back.

    If you want the purchase side explained, see this guide on how pending transactions work and how to plan around them. This article stays focused on money coming in.

    One more distinction. Check deposits follow different rules than direct deposits. As of October 2026, the first $275 of a day’s check deposits must be available by the next business day, and banks may hold the part of a check deposit above $6,725 longer[4]. Paychecks sent electronically don’t get those extended holds in the same way.

    Bank-by-bank summary table: when a pending deposit becomes spendable

    Every bank sets its own funds availability policy within the federal limits, and the only source that counts for a bank’s timing is that bank’s own site. Here is what each one publishes, as of October 2026. None of them gives a clock time for when a pending deposit becomes available; where a bank says nothing about timing at all, the row says “Not published.”

    Bank What the bank publishes about timing (as of October 2026) Federal ceiling for electronic direct deposit
    Chime Early direct deposit up to 2 days early; funds generally available the day the payment file is received. No clock time[5] Next business day at the latest
    Cash App Up to 2 days early compared to many banks. No clock time[6] Next business day at the latest
    Wells Fargo Early Pay Day up to 2 business days early, not guaranteed; the day and time depend on when the bank gets the deposit information. No clock time[7] Next business day at the latest
    Chase Secure Banking: eligible deposits up to 2 business days early; timing depends on the payer. No clock time[8] Next business day at the latest
    Bank of America Electronic payments such as direct deposit are typically available the same day they are received. No early-pay feature on its deposit-holds page. No clock time[9] Next business day at the latest
    Capital One 360 Checking Early Paycheck up to 2 days early; may land 2 days early, 1 day early, or on payday. No clock time[10] Next business day at the latest
    SoFi Up to 2 days before the scheduled payment date; may vary. No clock time[11] Next business day at the latest
    Ally Eligible paychecks up to 2 days before payday; no signup. No clock time[12] Next business day at the latest

    The right-hand column is the part you can count on. It comes from Regulation CC’s funds availability rules. No bank on this list can legally hold an electronic paycheck longer than that.

    To find your own bank’s exact timing, look for these in your app or on its website:

    1. Funds availability policy: usually in the account agreement or disclosures.
    2. Early pay or “get paid early” terms: some banks release deposits before settlement. Eligibility rules vary.
    3. Deposit cut-off time: this decides which business day a deposit counts toward.

    It takes about five minutes. Do it once, and you’ll know your rhythm for every payday after.

    What changes on weekends and holidays

    The ACH network settles on business days only. Saturdays, Sundays, and federal holidays don’t count. That’s the single biggest reason a deposit seems late.

    Here’s a common pattern. Your payday falls on a Monday holiday. Your employer knows this and usually sends payroll to settle the Friday before. If they don’t, your deposit settles Tuesday. Either way, a pending entry might sit on your screen all weekend without moving.

    Same-day processing has limits too. Same Day ACH entries submitted by the 4:45 p.m. ET deadline of the third daily window settle at 6:00 p.m. ET the same day[13]. Miss the cutoff, and it rolls to the next business day.

    A quick way to plan for this:

    • Look at the calendar for your next two paydays.
    • Mark any holiday that lands on or just before payday.
    • Assume the later date if you’re not sure. If money arrives early, that’s a bonus.

    The arithmetic is simple. One holiday can add one business day. A holiday weekend can stretch a Friday payday wait to Tuesday. Knowing that ahead of time turns a scare into a non-event.

    Planning bills around a pending deposit

    The real stress isn’t the pending label. It’s a bill that hits before the deposit clears. Fixing that is a scheduling problem, not a money problem.

    Start with a quick check. Look at bills set to auto-pay within one business day of payday. Those are the only ones at risk.

    Say your paycheck is $2,400 and settles Friday. Your phone bill of $85 auto-pays Friday at midnight. Your available balance Thursday night is $140. On paper, you’re fine: $140 minus $85 leaves $55. But if your $60 streaming and gym renewals also hit that night, you’re at negative $5 for a few hours.

    Three calm fixes:

    1. Move due dates. Most utilities and card issuers let you pick a due date. Set them two or three days after payday.
    2. Keep a small buffer. Even $100 left in checking absorbs timing gaps like the one above.
    3. Pay manually on deposit day. For a bill you can’t move, pay it once the money shows available.

    This doesn’t require a full budget overhaul. It’s one pass through your bills, maybe ten minutes. After that, payday timing stops being something you watch.

    A month calendar that marks your lowest-cash day helps here. You’ll see the tight spot before it happens, not after.

    What is safe to spend once it clears

    The deposit clears. Your available balance jumps. It’s tempting to treat that bigger number as spending money. It isn’t, quite.

    Your available balance is everything in the account right now. It doesn’t know about rent on the 1st or the car payment on the 10th. Those bills still have claims on that money.

    How the math actually works

    The number that matters is what’s left after the near-term claims come off. Here’s the formula:

    Safe-to-Spend™ = available cash − bills due before next payday − planned savings − cushion

    Take a real example:

    Line Amount
    Available after deposit clears $2,640
    Bills due before next payday (rent, phone, insurance) −$1,610
    Planned savings −$300
    Cushion you choose −$200
    What’s left to spend $530

    That $530 is your honest figure. It’s well below $2,640, but it’s real. You can spend it without wondering about Thursday.

    The bills line only counts what’s due before the next paycheck. Later bills will be covered by later income. That keeps the number fresh and focused on now.

    FAQ

    Can I spend a pending direct deposit?
    Usually not. Most banks keep pending deposits out of your available balance until they settle. Some offer early access, so check your own bank’s published terms.

    Why does my deposit show pending but my friend’s at another bank is already available?
    Banks set their own policies within federal limits. Some release funds as soon as the payroll file arrives. Others wait for the settlement date. Both are allowed.

    What if my deposit is still pending after the next business day?
    That’s past the federal ceiling for electronic payments under Regulation CC. Contact your bank first, then your employer’s payroll team to confirm the send date.

    Can a pending deposit be reversed?
    It can happen, for instance if payroll sent the wrong amount. It’s uncommon. If you’re unsure, wait until the deposit is available before spending against it.

    Once it lands

    A pending deposit is just money in transit. Federal rules cap the wait for electronic paychecks at the next business day. Network rules now push availability to the morning of settlement. Weekends and holidays are the main reason it ever feels slow.

    The part people miss comes after. Once the deposit lands, your balance is not what’s safe to spend. Bills due before your next payday come out first. Then your planned savings. Then a cushion you pick. What remains is yours.

    Amppfy does this arithmetic for you. You type in your balances, no bank login, and it shows one Safe-to-Spend™ number with the math printed underneath. Bills calendar, heads-ups, and a weekly 10-minute check-in keep it current. It’s free on iPhone and the web.

    Take ten minutes this week and set up your Safe-to-Spend™ number in Amppfy. Next payday, you’ll know exactly what you have.

    1. federalreserve.gov

    2. nacha.org

    3. nacha.org

    4. consumerfinance.gov

    5. chime.com

    6. cash.app

    7. wellsfargo.com

    8. chase.com

    9. bankofamerica.com

    10. capitalone.com

    11. sofi.com

    12. ally.com

    13. nacha.org

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it
    Banking Basics Banking How-To Guides Banking Tips Checking Account Digital Banking
    Share. Facebook Twitter LinkedIn Email Copy Link
    Previous ArticleDirect Deposit on a Holiday or Weekend: When Your Paycheck Actually Lands
    Next Article Bank Accounts for Couples: Joint, Separate, or Both, and How to Set Each One Up
    Thomas T.

    Thomas is a Personal Finance Writer and Financial Content Strategist with over 10 years of experience helping individuals make smarter financial decisions. He specializes in topics such as budgeting, debt management, saving strategies, and financial behavior, translating complex financial concepts into clear, actionable guidance. His work focuses on empowering readers to build sustainable financial habits and confidently navigate their financial lives, combining data-driven insights with practical, real-world advice.

    More Like This

    Truist Joint Account: How to Add a Partner to Checking

    By Thomas T.October 17, 2026

    U.S. Bank Joint Account: Adding a Partner or Opening One Together

    By Thomas T.October 17, 2026

    Online Banks That Offer Joint Accounts: Who Does, Who Doesn’t, and How to Open One

    By Thomas T.October 17, 2026
    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number.

    Download on the App Store

    Prefer the web? Sign up free ›

    Amppfy dashboard on an iPhone showing the Safe to Spend number with the math under it
    Helpful Resources

    Truist Joint Account: How to Add a Partner to Checking

    October 17, 2026

    U.S. Bank Joint Account: Adding a Partner or Opening One Together

    October 17, 2026

    Online Banks That Offer Joint Accounts: Who Does, Who Doesn’t, and How to Open One

    October 17, 2026

    Joint Bank Accounts for Unmarried Couples: What Changes, What Doesn’t, and How to Set One Up

    October 17, 2026

    Financial Clarity. Everyday Confidence.

    Facebook X (Twitter) YouTube LinkedIn
    Calculators

    Emergency Fund Calculator

    Compound Interest Calculator

    Interest Rate Calculator

    Net Worth Calculator

    Mortgage Calculator

    How Much Home Can I Afford

    Debt-to-Income Ratio Calculator

    Cost of Living Calculator

    Savings Calculator

    Savings Goal Calculator

    Monthly Budget Calculator

    Latest Resources

    Average Money Left Over After Bills in 2026: What the Numbers Say and Why Yours Differs

    October 17, 2026

    Disposable Income: What It Means, and What’s Actually Yours to Spend

    October 17, 2026

    How Much Money Should You Have Left After Bills? A Per-Paycheck Answer

    October 17, 2026

    Truist Joint Account: How to Add a Partner to Checking

    October 17, 2026
    About & Legal

    About Amppfy

    Documentation

    Editorial Policy

    EULA

    Terms of Use

    Acceptable Use Policy

    Privacy Policy

    Cookie Policy

    Disclaimer

    Do Not Sell or Share My Personal Information

    Acceptable Use Policy

    Disclaimer: Amppfy is committed to keeping its information transparent, accurate, and up-to-date. The information on Amppfy is provided for educational and informational purposes only and should NOT be considered financial, investment, tax, or legal advice. You should consult a qualified financial professional before making any financial decisions. This information may differ from what you find on the specific product or service provider’s website. All information, content, software, tools, products, or services on Amppfy are presented without warranty or guarantee. Please review the specific provider’s terms and conditions when evaluating products or services. By accessing Amppfy or using our AI generator tools, you acknowledge that you have read, understood, and agreed to our EULA, Terms of Use, Acceptable Use Policy, Privacy Policy, Cookie Policy, and Disclaimer. Amppfy.com uses cookies. For more information, visit Amppfy’s Cookie Policy. Amppfy may be compensated through third-party advertisers and affiliates. For more information, visit Amppfy’s Disclaimer.

    Copyright© 2026 Amppfy | All Rights Reserved

    Type above and press Enter to search. Press Esc to cancel.

    Advertiser Disclosure: Products may include affiliate links related to financial products or services. We may earn a commission at no additional cost to you. Our content remains independent and focused on helping you make informed financial decisions.
    Fact Checked
    Financial Disclaimer

    This content is for informational and educational purposes only and should not be considered financial advice. Personal finance decisions—including budgeting, saving, investing, credit, mortgages, taxes, and debt management—depend on your individual circumstances. Always consult a qualified financial professional before making financial decisions.

    Editorial Standards and Content Integrity

    Our editorial process ensures accuracy, clarity, and trust across all personal finance topics, including budgeting, saving, investing, and debt management. Content is created using credible sources such as government agencies, academic research, and established financial institutions, and may incorporate insights from industry experts when relevant. Each article is reviewed for accuracy, timeliness, and relevance before publication and updated as needed to reflect changes in financial guidelines and best practices, with the goal of providing clear, evidence-based information to help readers make informed financial decisions.

    Learn more about our editorial policy and guideline.
    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Download the app and enter your balances, bills, and payday. About ten minutes to one clear number: what’s safe to spend before payday.Your balances, bills, and payday. Ten minutes to one clear number. Learn more ›

    Download on the App Store
    Scan with your iPhone to get the app

    Free  ·  No credit card  ·  Just your balances

    Prefer the web? Sign up free ›

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Enter your balances, bills, and payday once. About ten minutes to one clear number, with the math shown under it.

    Download on the App Store
    Scan with your iPhone to get the app

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances