Close Menu

    Subscribe to Updates

    Get the latest creative news from FooBar about art, design and business.

    What's Hot

    Average Money Left Over After Bills in 2026: What the Numbers Say and Why Yours Differs

    October 17, 2026

    Disposable Income: What It Means, and What’s Actually Yours to Spend

    October 17, 2026

    How Much Money Should You Have Left After Bills? A Per-Paycheck Answer

    October 17, 2026
    Facebook X (Twitter) Instagram
    Amppfy
    • Safe to Spend™ App
      • Amppfy on iPhone — one clear number with the status scale and the math under itYour number, in your pocketFree on iPhone, with the same account on the web.
        • Download on the App Store
        • Prefer the web? Sign up free ›
      • The app
        • OverviewOne clear number for what’s safe to spend before payday
        • Safe-to-Spend™The four-line math, always shown
        • Weekly check-inTen minutes a week keeps it honest
      • Features
        • Bills & paydaysEvery bill and payday on one calendar
        • GoalsSavings that fund themselves first
        • For couplesTwo logins, one number you both trust
        • SubscriptionsWhat you pay monthly, and what cancelling gives back
        • Calendar & heads-upsYour month at a glance, a heads-up before bills land
        • Net worth & payday nudgeThe whole picture, month by month
        • BudgetWhere the month’s money goes, month by month
      • Trust & help
        • Security & privacyJust your balances, optional two-step verification
        • Help centerSetup, the number, check-ins, FAQ
        • Open the web appSame account, any browser
    • Personal Finance
      • Money Basics
        • How to Master Money Management
        • Psychology of Money Habits
        • How to Set Financial Goals
        • Money Management for Every Life Stage
        • Beyond Budgeting: Advanced Money Skills
        • Financial Literacy
        • Money Management
        • Know Your Money
        • Cash Flow
      • Financial Wellness
        • Understand Your Money Relationship
        • Build a Healthy Money Mindset
        • 7 Money Tips for Financial Freedom
        • Take the Money Health Quiz
        • Monthly Financial Reviews
        • Money Habits
        • Money Mindset
        • Financial Goals
        • Financial Independence
      • Side Hustles & Extra Income
        • 8 Realistic Side Hustles
        • How to Make Money Online
        • Passive Income Ideas That Work
        • Passive Income 101: Ideas That Scale
        • Spot a Bad Passive Income Deal
        • Start Freelance Writing: First $1,000
        • Budgeting with Irregular Income
        • Side Hustle Ideas
        • Passive Income
        • Gig Economy
      • Major Money Decisions
        • Plan a Major Purchase Without Debt
        • Car Buying: Save, Finance, or Lease?
        • Used Car Buying & Negotiation Tips
        • What to Save For vs. Finance
        • Life Insurance 101: Coverage Needs
        • Term vs. Whole Life Insurance
        • Buying a Car
        • Major Purchase Planning
        • Home Improvement
        • Life Insurance
      • Money Tools & Calculators
        • Net Worth Calculator
        • Cost of Living Calculator
        • Compound Interest Calculator
        • Monthly Budget Calculator
        • Savings Goal Calculator
        • Emergency Fund Calculator
        • Savings Calculator
        • Do Money Management Tools Work?
        • Spend Tracking
        • Net Worth
    • Savings
      • Budgeting Tips
        • The 50/30/20 Rule Explained
        • How to Make a Monthly Budget
        • How to Budget Money in 5 Steps
        • The Envelope Method Explained
        • Best Budgeting Apps Compared
        • Common Budgeting Mistakes
        • Budgeting for Couples
        • Start a Budget
        • Budget Methods
        • 50/30/20 Budgeting
      • Ways to Save
        • Save $500 This Month
        • 14 Ways to Cut Monthly Expenses
        • How to Save Money on Groceries
        • Lower Your Utility Bills
        • Budget Swaps for Big Purchases
        • Save Money on Car Insurance
        • Cut Expenses
        • Groceries Savings
        • Smart Saving Strategies
      • Emergency Fund
        • How Much Emergency Fund to Save
        • How to Build an Emergency Fund
        • Start a Rainy Day Fund
        • Sinking Funds vs. Emergency Fund
        • Emergency Fund Essentials
        • Where to Keep Your Emergency Fund
        • Best Emergency Fund Tips
        • Emergency Savings
        • Emergency Buffer
      • Savings Goals & Plans
        • How to Create a Savings Plan
        • How to Set Savings Goals
        • Track Spending Without Spreadsheets
        • 529 College Savings on a Budget
        • Saving During a Recession
        • Budget a Debt-Free Vacation
        • Vacation Budgeting
        • Family Budgeting
        • Savings Goals
        • Recession Saving
      • Savings Tools & Planning
        • Budget Calculator
        • Savings Goal Calculator
        • Emergency Fund Calculator
        • Savings Calculator
        • Compound Interest Calculator
        • Savings Buckets
        • Sinking Funds
        • Maximize Your Savings
        • Savings Tips
        • Savvy Saver
    • Debt
      • Get Out of Debt
        • Debt Snowball vs. Avalanche
        • Pay Off Credit Card Debt Fast
        • Beginner’s Credit Card Payoff Plan
        • Build a Debt Payoff Calendar
        • Use Windfalls to Crush Debt
        • Debt Free Journey
        • Debt Payoff
        • Credit Card Debt
      • Student & Auto Loans
        • Student Loans 101
        • Get Out of Student Loan Debt
        • Income-Driven Repayment Plans
        • Best Student Loan Repayment Option
        • Auto Loans: Shop & Save on Interest
        • Pay Off Your Auto Loan Early
        • Student Loans
        • Auto Loans
        • Auto Loan Debt
      • Debt Consolidation
        • Debt Consolidation Pros & Cons
        • Is Consolidating Debt Right for You?
        • Balance Transfers to Pay Off Debt
        • HELOC to Pay Off Credit Cards
        • 401(k) Rollover to Pay Down Debt
        • How to Refinance a Personal Loan
        • Before You Take a Personal Loan
        • Personal Loans
        • Personal Loan Refinance
      • Managing Debt
        • Navigating Medical Debt
        • Budgeting with a High-Interest Loan
        • Build a Debt-Repayment Fund
        • Debt Payoff for Single Parents
        • Save for a Wedding Without Debt
        • Medical Debt
        • Single Parent Debt
        • Personal Loan Debt
      • Debt Relief & Protection
        • When Bankruptcy Is an Option
        • Avoid Predatory Lenders & Scams
        • Negotiate with Creditors: Scripts
        • Budgeting Around Wage Garnishment
        • Debt Relief
        • Bankruptcy
        • Creditor Negotiation
        • Predatory Lenders
        • Wage Garnishment
    • Credit
      • Credit Scores
        • Credit Score 101
        • Check & Improve Your Credit Score
        • Credit Utilization: A Simple Fix
        • Check Your Credit Score Free
        • Rebuild Credit After a Setback
        • How Credit Scores Are Calculated
        • What Credit Scores Mean
        • Credit Health
      • Credit Reports
        • Read & Dispute Your Credit Report
        • Dispute Template That Works
        • How Long Negative Marks Last
        • Remove Negative Items
        • What to Expect as Items Age Off
        • Understanding Credit Utilization
        • Credit Basics
        • Checking Your Credit Score
      • Building Credit
        • Best Starter Credit Cards
        • Secured vs. Unsecured Cards
        • Secured Cards & Credit-Builder Loans
        • Build Credit as a Gig Worker
        • Boost Your Score Before a Mortgage
        • Borrow Now vs. Wait
        • Build Credit
        • Credit Cards for Beginners
        • Credit for Gig Workers
      • Credit Cards
        • Best Rewards Credit Cards
        • Credit Card Hacks: Intro APRs
        • Balance Transfers Explained
        • Earn Rewards Without Debt
        • Responsible Card Use & Rewards Tips
        • Lost or Stolen Card: What to Do
        • Credit Card Rewards
        • Balance Transfer Cards
      • Credit Protection & Safety
        • Identity Theft Checklist
        • Truth About Credit Freezes
        • How to Freeze & Thaw Your Credit
        • Credit Monitoring vs. Freezes
        • Credit Protection
        • Credit Freeze
        • Fraud Awareness
        • Financial Safety
    • Investing
      • Start Investing
        • Investing 101: Beginner’s Guide
        • Start Investing with $100
        • Start with $50/Month
        • Scared of the Market? Start Here
        • Open a Brokerage Account
        • Invest While Paying Down Debt
        • How to Start Investing
        • Start with Little Money
        • Fear of Investing
      • Investing Strategy
        • Roth IRA vs. Traditional IRA
        • Dollar-Cost Averaging Explained
        • DCA vs. Lump-Sum Investing
        • 5 Simple Starter Portfolios
        • Asset Allocation Beyond 60/40
        • How to Rebalance Your Portfolio
        • Diversify Your Portfolio
        • Investing Mistakes to Avoid
        • Investment Strategies
        • Diversification
      • Stocks
        • How the Stock Market Works
        • How to Make Money in Stocks
        • How to Read Stock Charts
        • Analyze Stocks in 5 Steps
        • P/E Ratio for Beginners
        • Bullish vs. Bearish Explained
        • How Stock Trading Works
        • Stock Market Basics
        • Stock Analysis
        • Stock Trading Strategies
      • Funds & Wealth Building
        • Beginner’s Guide to Index Funds
        • Best S&P 500 Index Funds
        • Mutual Funds vs. ETFs
        • How to Invest in ETFs
        • Dividend Investing for Beginners
        • Build a Dividend Income Stream
        • Maximize Your 401(k) Match
        • Build a Retirement Portfolio
        • Index Funds
        • Dividend Investing
      • Brokerages & Platforms
        • Vanguard vs. Fidelity
        • Fidelity vs. Schwab
        • Robinhood vs. E*Trade
        • Robo-Advisors vs. Human Advisors
        • Robo-Advisor or DIY Investing?
        • How Brokerage Fees Affect Returns
        • Manage Multiple Brokerage Accounts
        • Brokerages
        • Investment Platforms
        • Robo Advisors
    • Home
      • Home Buying
        • First-Time Homebuyer Checklist
        • How Much Down Payment You Need
        • How Much Home Can You Afford?
        • Renting vs. Buying
        • True Costs of Homeownership
        • Qualify as a First-Time Buyer
        • Buying a Fixer-Upper
        • First-Time Home Buyer
        • Home Affordability
      • Mortgage
        • First-Time Buyer’s Mortgage Guide
        • Fixed vs. Adjustable Mortgage
        • How to Refinance a Mortgage
        • Mortgage Payoff Strategies
        • Winning in a High-Rate Market
        • Mortgage Amortization Calculator
        • Down Payment Assistance Programs
        • Mastering Refinance Rate Locks
        • Mortgage Rates
        • Mortgage Refinance
        • Debt-to-Income Calculator
      • Real Estate Investing
        • Real Estate Crowdfunding Platforms
        • Rental Property Cash Flow
        • REITs for Passive Income
        • REITs vs. Direct Ownership
        • Fix-and-Flip Opportunities
        • Airbnb & Short-Term Rental ROI
        • Buying a Multi-Family Property
        • 1031 Exchange to Defer Taxes
        • Real Estate Investing
        • Rental Property
      • Home Insurance
        • Homeowners Insurance Guide
        • Compare Home Insurance Quotes
        • Best Home Insurance Companies
        • Choose Your Deductible
        • Renters vs. Homeowners Insurance
        • File a Property Insurance Claim
        • Home Insurance Coverage Basics
        • Home Insurance Rates
        • Home Insurance Claims
      • Home Equity & Ownership
        • Smart Ways to Use Home Equity
        • Save for a Down Payment
        • Down Payment Strategies
        • Estimate Property Appreciation
        • Home Equity
        • HELOC Payoff Strategy
        • Home Down Payment
        • Home Ownership
        • Home Renovation
    • Bank
      • Banking Basics
        • Open Your First Bank Account
        • Online Banks vs. Traditional Banks
        • How to Avoid Bank Fees
        • How to Switch Banks
        • Read Your Bank Statement
        • Second-Chance Checking Accounts
        • Get Better Rates from Your Bank
        • Banking Basics
        • How to Choose a Bank
        • Compare Banks
      • Checking Accounts
        • Best Checking Accounts
        • Choose the Right Checking Account
        • Overdraft Protection Guide
        • Stop Paying Overdraft Fees
        • The True Cost of Checking Fees
        • Mobile Check Deposits
        • How Long Checks Take to Clear
        • Checking Accounts
        • Best Checking Account
      • Savings Accounts & CDs
        • High-Yield Savings Explained
        • Best High-Yield Savings Account
        • Savings Accounts vs. CDs
        • What Is a CD?
        • Money Market vs. Savings Account
        • HYSA vs. Treasury Bills
        • How Savings Interest Is Calculated
        • Savings Account Minimum Balances
        • Savings Account
      • Bank Smarter
        • Top Banks for High-APY Savings
        • How Much Cash in Each Account
        • How Many Savings Accounts to Have
        • Managing Multiple Bank Accounts
        • Where to Put Your Money
        • When to Save vs. When to Invest
        • Savings Account Fees to Avoid
        • Banking Tips
        • Digital Banking
      • Banking Safety & Security
        • Set Up Bank Account Alerts
        • Avoid Check Scams
        • Missing Debit Card: Next Steps
        • When to Stop a Check Payment
        • Bank Fees
        • Debit Cards
        • Joint Bank Accounts
        • Banking How-To Guides
    • Sign In
    • Sign Up
    Amppfy
    Home » Budgeting and Saving » How Much Money Should You Have Left After Bills? A Per-Paycheck Answer
    Budgeting and Saving

    How Much Money Should You Have Left After Bills? A Per-Paycheck Answer

    Work four lines of arithmetic on a receipt to find how much of your paycheck is free before the next deposit.
    Thomas T.By Thomas T.October 17, 2026Updated:October 17, 202611 Mins Read
    Facebook Twitter LinkedIn Email Copy Link
    How Much Money Should You Have Left After Bills? A Per-Paycheck Answer
    Share
    Facebook Twitter LinkedIn Email Copy Link

    Payday lands. Your bank app shows a nice, round balance. Then rent clears, the car insurance pulls, and by Thursday you’re not sure what’s actually yours to spend. The question isn’t really “how much is normal.” It’s “how much of this balance is free right now, before the next deposit?”

    That question has a clear answer. It isn’t a percentage pulled from a chart or a figure a coworker mentioned. It’s a short piece of arithmetic you can do on the back of a receipt in about two minutes.

    This guide walks through that arithmetic. It covers the four lines, where people usually slip, and what national averages can and can’t tell you about your own paycheck. You’ll also see when doing it by hand works fine and when it helps to let something repeat the math for you.

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

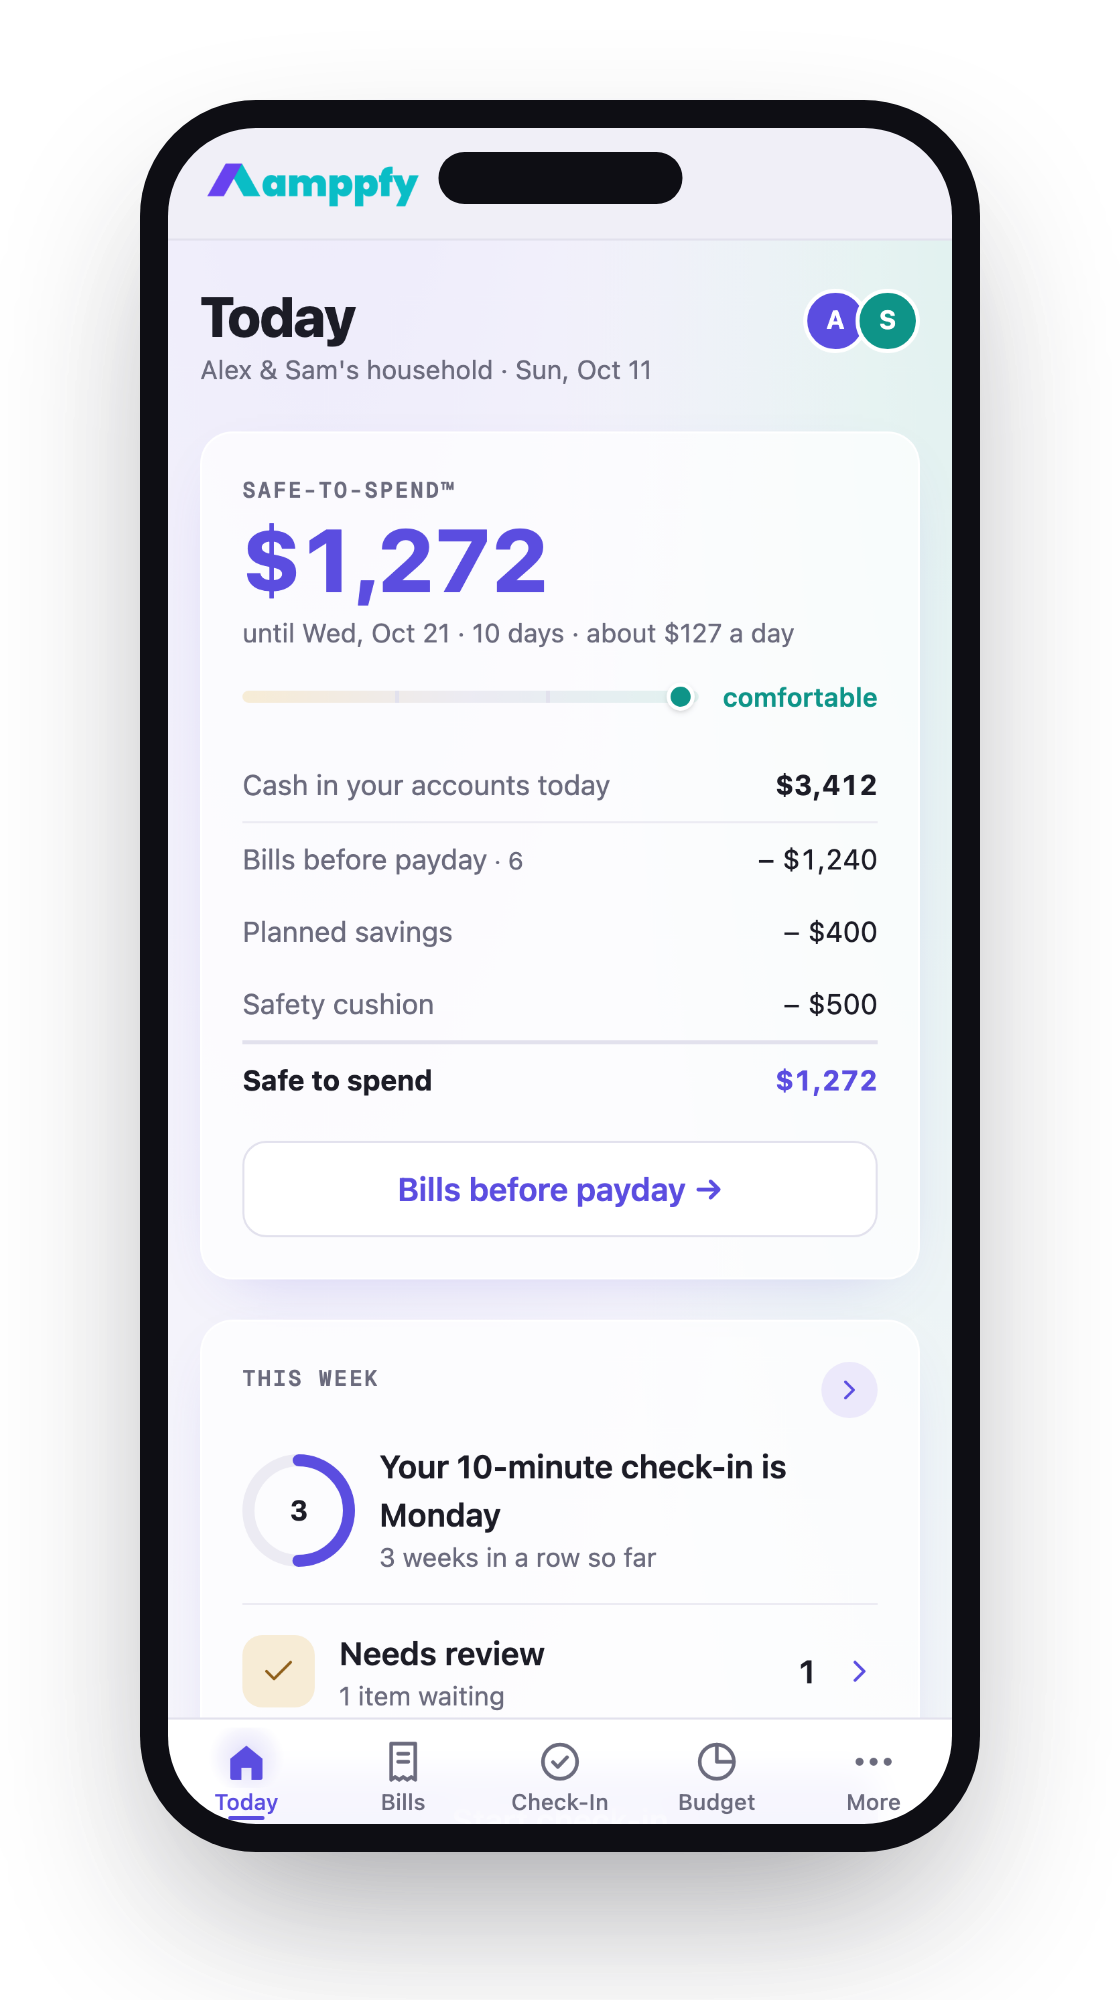
    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it

    What Safe-to-Spend™ means

    Safe-to-Spend™ is the amount you can spend between now and your next payday without shorting a bill, skipping savings, or draining your buffer. It’s one number. It changes as days pass and bills clear.

    Most people ask how much money should you have left over after bills as if there’s a correct dollar amount. There isn’t. A nurse in Phoenix, a teacher in Ohio, and a couple splitting rent in Brooklyn will all get different answers. The honest answer is this: the right amount is whatever remains after three things come out.

    • Bills due before your next payday. These are bills that hit before the next deposit, not every bill this month.
    • Planned savings. This is the amount you’ve decided to set aside from this paycheck.
    • A cushion. This is a buffer you choose, so a surprise charge doesn’t tip you negative.

    Why per paycheck and not per month? Because your money arrives in pieces. If you’re paid every two weeks, your rent might come out of paycheck one while your phone bill lands after paycheck two. A monthly view blends those together and hides the tight spots. A per-paycheck view shows you the next stretch only, from today until the next deposit. Later bills don’t count yet, because the next paycheck covers them.

    There’s a longer explanation in what Safe-to-Spend™ is and why your bank app doesn’t show it. The short version: your balance tells you what’s in the account. It doesn’t tell you what’s already spoken for.

    The four-line math, worked

    Here’s the formula. It’s four lines.

    Line What it is
    Cash available What’s in checking (and any account you spend from) right now
    − Bills due before payday Only bills that will clear before your next deposit
    − Planned savings What you’re moving to savings from this paycheck
    − Cushion A fixed buffer you pick and leave alone

    And here it is with real numbers:

    $3,412 cash − $1,240 bills due before payday − $400 planned savings − $500 cushion = $1,272 Safe-to-Spend™.

    Walk through it once, slowly.

    1. Confirm your cash: $3,412. Open your bank app and add up the balances you actually spend from. Leave out retirement accounts and money you’ve already earmarked elsewhere.
    2. List bills due before payday: $1,240. Say payday is the 15th and today is the 2nd. Rent ($950), the electric bill ($110), and car insurance ($180) all hit before the 15th. That adds up to $1,240. Your streaming subscriptions on the 20th aren’t on this list. The next paycheck handles them.
    3. Subtract planned savings: $400. Pick an amount and treat it like a bill. If you move it on payday, even better, because it’s gone before you’re tempted.
    4. Subtract your cushion: $500. This covers the timing gap when a charge posts a day early or a pending hold sits longer than expected.

    What’s left is $1,272. That’s groceries, gas, dinners out, the kid’s field trip, and whatever else comes up over the next 13 days. Divide by 13 and you get roughly $98 a day. That gives you a quick gut-check when you’re standing in a checkout line.

    A physical picture can help here. Think of your balance as a full water jug. Before you pour a glass, you mark three lines on the side: the bills, the savings, and the cushion. You only drink from above the top line.

    Where the number goes wrong

    The math is simple. The inputs are where things slip. Most bad numbers come from one of three places.

    Counting bills that fall after payday

    This is the most common error, and it usually runs in a cautious direction. People subtract every bill in the month, which makes the number look tiny and stressful. Then they ignore it.

    The fix is to look at dates, not totals. Pull up your bills and check each due date against your next payday. If it clears after the deposit, leave it off this round. There’s a step-by-step method in counting only the bills due before payday.

    The opposite mistake happens too. Annual or quarterly bills, like car registration or a renter’s insurance renewal, get forgotten because they don’t show up every month. Put them on a calendar once, and they’ll appear in the right pay period when their turn comes.

    Treating savings as “whatever’s left”

    If savings only happens when money remains at the end, it rarely happens. Subtracting it up front changes the order. Savings becomes a line in the math, not a hope. Start small if you need to. Even $50 per paycheck is a real line, and you can raise it later.

    Picking a cushion that’s too thin or too thick

    There’s no official cushion size. A cushion of $0 means any early-posting charge or forgotten subscription can push you into the red. A cushion of $3,000 in checking might be money that belongs in a savings account instead.

    A practical starting point is your largest typical surprise. That might be a co-pay, a car repair deductible, or one week of groceries. Pick a number, use it for a month, and adjust. The cushion isn’t an emergency fund. It’s a small pad against timing gaps.

    What the averages say, and why yours differs

    People often want a benchmark, and that’s fair. Here’s what the official data shows, and why it can’t stand in for your own answer.

    The Bureau of Labor Statistics runs the Consumer Expenditure Survey. Its most recent annual release came out December 19, 2025, covering data year 2024. It found that consumer units had average annual expenditures of $78,535 against average income before taxes of $104,207. If you’re curious how that spending splits across housing, food, and transportation, see how Americans split their household budget in the latest BLS data.

    It’s tempting to subtract one figure from the other and call the gap “money left over.” Be careful. Those are pre-tax income figures, and BLS did not publish a 2024 after-tax income figure in that release. So the difference doesn’t tell you what the average household had left after taxes and bills. Treat it as background, not a target.

    Even with a perfect national average, your number would still differ. Here’s why.

    • Location. Rent and childcare vary widely from one state, and even one zip code, to the next.
    • Household size. Two incomes and one kid behave differently from one income and two kids.
    • Pay rhythm. Biweekly, semimonthly, and weekly pay create different tight spots, even at the same salary.
    • Bill timing. Two people with identical bills can have very different paychecks if rent lands right after one payday and right before another.
    • Debt. A car loan or student loan payment changes the bills line a lot.

    That’s the case for per-paycheck math. An average describes a population. Your four lines describe your next two weeks. When you’re deciding whether you can afford dinner out on Friday, the second one is the one that helps.

    Doing it by hand vs letting an app do it daily

    Doing it by hand is fine. Truly. A notes app, a sticky note, or a spreadsheet works. Here’s a by-hand routine that takes about 10 minutes a week.

    1. Pick a check-in day. Sunday evening or the morning after payday both work well.
    2. Update balances. Look up each account you spend from and write down the current number.
    3. List bills before the next payday. Check due dates, not monthly totals.
    4. Subtract savings and cushion. Use the same amounts each time unless you’ve decided to change them.
    5. Write the result somewhere visible. Put it on your phone’s lock screen note or the fridge whiteboard. Wherever you’ll glance at it.

    The weak spot of doing it by hand isn’t the math. It’s that the number goes stale. On Monday it’s accurate. By Thursday you’ve bought groceries, a bill cleared early, and the figure on the sticky note is out of date. You can redo it daily, but most people won’t.

    That’s the only thing an app adds. It repeats the same four lines every day, so the number stays current between check-ins. It doesn’t make the math smarter. It just keeps it fresh.

    If you share money with a partner, staleness doubles. Each of you spends from the same pool and each of you has a slightly different mental number. A shared view, where both people see one figure with the math printed underneath, removes the “wait, did you pay the electric?” text.

    Amppfy is one option built around this idea. It’s free on iPhone and the web as of October 2026. You type your balances in yourself, so there’s no bank login and no transaction import. It shows a bills calendar with the lowest point before payday marked, and it sends a heads-up the day before a bill. A partner can join with their own login and see the same number while private accounts stay private. There’s no Android app, but a partner on Android can use the web version.

    Whichever route you choose, the test is the same. Can you say your number in one breath, right now? If yes, your system is working.

    FAQ

    How much money should you have left over after bills each paycheck?

    There’s no single right dollar amount. The right amount is what remains after the bills due before your next payday, your planned savings, and a cushion you choose. If that leaves $1,272 for 13 days, that’s your answer for this pay period. It will be different next time, and that’s normal.

    Should I count all my monthly bills or just some of them?

    Count only the bills that clear before your next deposit. Bills due after payday belong to the next paycheck’s math. Counting everything at once makes the number look smaller than it is and tends to make people stop checking.

    What if my Safe-to-Spend™ number comes out negative?

    A negative result is information, not a verdict. It tells you that this pay period’s bills, savings, and cushion add up to more than your current cash. Start by lowering planned savings for this cycle. Then look at whether any bill can move to after payday by calling the company and asking. Shrinking the cushion temporarily is the last lever, and you can rebuild it next round.

    How big should my cushion be?

    Pick an amount that covers your most common surprise. That could be a typical co-pay, a week of groceries, or a charge that sometimes posts early. Many people start somewhere between a few hundred dollars and one week of spending, then adjust after a month. Keep it in the account you spend from so it actually catches timing gaps.


    The question of what should remain after bills has a calm, arithmetic answer. Take your cash and subtract what’s due before payday, what you’re saving, and your cushion. What’s left is yours. National averages can give you context, but your four lines tell you what you can actually spend this week.

    Take 10 minutes this week and run the numbers once by hand. If you’d like that number kept current every day, with the math shown underneath, try the Safe-to-Spend™ view in Amppfy. Either way, you’ll know your number before the next payday arrives.

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it
    Budgeting Basics budgeting tips Cash Flow Fix Cashflow and Budget Money Management Basics Monthly Budget Spend Tracking
    Share. Facebook Twitter LinkedIn Email Copy Link
    Previous ArticleTruist Joint Account: How to Add a Partner to Checking
    Next Article Disposable Income: What It Means, and What’s Actually Yours to Spend
    Thomas T.

    Thomas is a Personal Finance Writer and Financial Content Strategist with over 10 years of experience helping individuals make smarter financial decisions. He specializes in topics such as budgeting, debt management, saving strategies, and financial behavior, translating complex financial concepts into clear, actionable guidance. His work focuses on empowering readers to build sustainable financial habits and confidently navigate their financial lives, combining data-driven insights with practical, real-world advice.

    More Like This

    Average Money Left Over After Bills in 2026: What the Numbers Say and Why Yours Differs

    By Thomas T.October 17, 2026

    Disposable Income: What It Means, and What’s Actually Yours to Spend

    By Thomas T.October 17, 2026

    Discretionary Income Per Paycheck: How to Find Your Spendable Amount

    By Thomas T.October 17, 2026
    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number.

    Download on the App Store

    Prefer the web? Sign up free ›

    Amppfy dashboard on an iPhone showing the Safe to Spend number with the math under it
    Helpful Resources

    Average Money Left Over After Bills in 2026: What the Numbers Say and Why Yours Differs

    October 17, 2026

    Disposable Income: What It Means, and What’s Actually Yours to Spend

    October 17, 2026

    Discretionary Income Per Paycheck: How to Find Your Spendable Amount

    October 17, 2026

    What Is Safe to Spend? The Number Your Bank App Doesn’t Show

    October 17, 2026

    Financial Clarity. Everyday Confidence.

    Facebook X (Twitter) YouTube LinkedIn
    Calculators

    Emergency Fund Calculator

    Compound Interest Calculator

    Interest Rate Calculator

    Net Worth Calculator

    Mortgage Calculator

    How Much Home Can I Afford

    Debt-to-Income Ratio Calculator

    Cost of Living Calculator

    Savings Calculator

    Savings Goal Calculator

    Monthly Budget Calculator

    Latest Resources

    Average Money Left Over After Bills in 2026: What the Numbers Say and Why Yours Differs

    October 17, 2026

    Disposable Income: What It Means, and What’s Actually Yours to Spend

    October 17, 2026

    How Much Money Should You Have Left After Bills? A Per-Paycheck Answer

    October 17, 2026

    Truist Joint Account: How to Add a Partner to Checking

    October 17, 2026
    About & Legal

    About Amppfy

    Documentation

    Editorial Policy

    EULA

    Terms of Use

    Acceptable Use Policy

    Privacy Policy

    Cookie Policy

    Disclaimer

    Do Not Sell or Share My Personal Information

    Acceptable Use Policy

    Disclaimer: Amppfy is committed to keeping its information transparent, accurate, and up-to-date. The information on Amppfy is provided for educational and informational purposes only and should NOT be considered financial, investment, tax, or legal advice. You should consult a qualified financial professional before making any financial decisions. This information may differ from what you find on the specific product or service provider’s website. All information, content, software, tools, products, or services on Amppfy are presented without warranty or guarantee. Please review the specific provider’s terms and conditions when evaluating products or services. By accessing Amppfy or using our AI generator tools, you acknowledge that you have read, understood, and agreed to our EULA, Terms of Use, Acceptable Use Policy, Privacy Policy, Cookie Policy, and Disclaimer. Amppfy.com uses cookies. For more information, visit Amppfy’s Cookie Policy. Amppfy may be compensated through third-party advertisers and affiliates. For more information, visit Amppfy’s Disclaimer.

    Copyright© 2026 Amppfy | All Rights Reserved

    Type above and press Enter to search. Press Esc to cancel.

    Advertiser Disclosure: Products may include affiliate links related to financial products or services. We may earn a commission at no additional cost to you. Our content remains independent and focused on helping you make informed financial decisions.
    Fact Checked
    Financial Disclaimer

    This content is for informational and educational purposes only and should not be considered financial advice. Personal finance decisions—including budgeting, saving, investing, credit, mortgages, taxes, and debt management—depend on your individual circumstances. Always consult a qualified financial professional before making financial decisions.

    Editorial Standards and Content Integrity

    Our editorial process ensures accuracy, clarity, and trust across all personal finance topics, including budgeting, saving, investing, and debt management. Content is created using credible sources such as government agencies, academic research, and established financial institutions, and may incorporate insights from industry experts when relevant. Each article is reviewed for accuracy, timeliness, and relevance before publication and updated as needed to reflect changes in financial guidelines and best practices, with the goal of providing clear, evidence-based information to help readers make informed financial decisions.

    Learn more about our editorial policy and guideline.
    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Download the app and enter your balances, bills, and payday. About ten minutes to one clear number: what’s safe to spend before payday.Your balances, bills, and payday. Ten minutes to one clear number. Learn more ›

    Download on the App Store
    Scan with your iPhone to get the app

    Free  ·  No credit card  ·  Just your balances

    Prefer the web? Sign up free ›

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Enter your balances, bills, and payday once. About ten minutes to one clear number, with the math shown under it.

    Download on the App Store
    Scan with your iPhone to get the app

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances