Close Menu

    Subscribe to Updates

    Get the latest creative news from FooBar about art, design and business.

    What's Hot

    Average Money Left Over After Bills in 2026: What the Numbers Say and Why Yours Differs

    October 17, 2026

    Disposable Income: What It Means, and What’s Actually Yours to Spend

    October 17, 2026

    How Much Money Should You Have Left After Bills? A Per-Paycheck Answer

    October 17, 2026
    Facebook X (Twitter) Instagram
    Amppfy
    • Safe to Spend™ App
      • Amppfy on iPhone — one clear number with the status scale and the math under itYour number, in your pocketFree on iPhone, with the same account on the web.
        • Download on the App Store
        • Prefer the web? Sign up free ›
      • The app
        • OverviewOne clear number for what’s safe to spend before payday
        • Safe-to-Spend™The four-line math, always shown
        • Weekly check-inTen minutes a week keeps it honest
      • Features
        • Bills & paydaysEvery bill and payday on one calendar
        • GoalsSavings that fund themselves first
        • For couplesTwo logins, one number you both trust
        • SubscriptionsWhat you pay monthly, and what cancelling gives back
        • Calendar & heads-upsYour month at a glance, a heads-up before bills land
        • Net worth & payday nudgeThe whole picture, month by month
        • BudgetWhere the month’s money goes, month by month
      • Trust & help
        • Security & privacyJust your balances, optional two-step verification
        • Help centerSetup, the number, check-ins, FAQ
        • Open the web appSame account, any browser
    • Personal Finance
      • Money Basics
        • How to Master Money Management
        • Psychology of Money Habits
        • How to Set Financial Goals
        • Money Management for Every Life Stage
        • Beyond Budgeting: Advanced Money Skills
        • Financial Literacy
        • Money Management
        • Know Your Money
        • Cash Flow
      • Financial Wellness
        • Understand Your Money Relationship
        • Build a Healthy Money Mindset
        • 7 Money Tips for Financial Freedom
        • Take the Money Health Quiz
        • Monthly Financial Reviews
        • Money Habits
        • Money Mindset
        • Financial Goals
        • Financial Independence
      • Side Hustles & Extra Income
        • 8 Realistic Side Hustles
        • How to Make Money Online
        • Passive Income Ideas That Work
        • Passive Income 101: Ideas That Scale
        • Spot a Bad Passive Income Deal
        • Start Freelance Writing: First $1,000
        • Budgeting with Irregular Income
        • Side Hustle Ideas
        • Passive Income
        • Gig Economy
      • Major Money Decisions
        • Plan a Major Purchase Without Debt
        • Car Buying: Save, Finance, or Lease?
        • Used Car Buying & Negotiation Tips
        • What to Save For vs. Finance
        • Life Insurance 101: Coverage Needs
        • Term vs. Whole Life Insurance
        • Buying a Car
        • Major Purchase Planning
        • Home Improvement
        • Life Insurance
      • Money Tools & Calculators
        • Net Worth Calculator
        • Cost of Living Calculator
        • Compound Interest Calculator
        • Monthly Budget Calculator
        • Savings Goal Calculator
        • Emergency Fund Calculator
        • Savings Calculator
        • Do Money Management Tools Work?
        • Spend Tracking
        • Net Worth
    • Savings
      • Budgeting Tips
        • The 50/30/20 Rule Explained
        • How to Make a Monthly Budget
        • How to Budget Money in 5 Steps
        • The Envelope Method Explained
        • Best Budgeting Apps Compared
        • Common Budgeting Mistakes
        • Budgeting for Couples
        • Start a Budget
        • Budget Methods
        • 50/30/20 Budgeting
      • Ways to Save
        • Save $500 This Month
        • 14 Ways to Cut Monthly Expenses
        • How to Save Money on Groceries
        • Lower Your Utility Bills
        • Budget Swaps for Big Purchases
        • Save Money on Car Insurance
        • Cut Expenses
        • Groceries Savings
        • Smart Saving Strategies
      • Emergency Fund
        • How Much Emergency Fund to Save
        • How to Build an Emergency Fund
        • Start a Rainy Day Fund
        • Sinking Funds vs. Emergency Fund
        • Emergency Fund Essentials
        • Where to Keep Your Emergency Fund
        • Best Emergency Fund Tips
        • Emergency Savings
        • Emergency Buffer
      • Savings Goals & Plans
        • How to Create a Savings Plan
        • How to Set Savings Goals
        • Track Spending Without Spreadsheets
        • 529 College Savings on a Budget
        • Saving During a Recession
        • Budget a Debt-Free Vacation
        • Vacation Budgeting
        • Family Budgeting
        • Savings Goals
        • Recession Saving
      • Savings Tools & Planning
        • Budget Calculator
        • Savings Goal Calculator
        • Emergency Fund Calculator
        • Savings Calculator
        • Compound Interest Calculator
        • Savings Buckets
        • Sinking Funds
        • Maximize Your Savings
        • Savings Tips
        • Savvy Saver
    • Debt
      • Get Out of Debt
        • Debt Snowball vs. Avalanche
        • Pay Off Credit Card Debt Fast
        • Beginner’s Credit Card Payoff Plan
        • Build a Debt Payoff Calendar
        • Use Windfalls to Crush Debt
        • Debt Free Journey
        • Debt Payoff
        • Credit Card Debt
      • Student & Auto Loans
        • Student Loans 101
        • Get Out of Student Loan Debt
        • Income-Driven Repayment Plans
        • Best Student Loan Repayment Option
        • Auto Loans: Shop & Save on Interest
        • Pay Off Your Auto Loan Early
        • Student Loans
        • Auto Loans
        • Auto Loan Debt
      • Debt Consolidation
        • Debt Consolidation Pros & Cons
        • Is Consolidating Debt Right for You?
        • Balance Transfers to Pay Off Debt
        • HELOC to Pay Off Credit Cards
        • 401(k) Rollover to Pay Down Debt
        • How to Refinance a Personal Loan
        • Before You Take a Personal Loan
        • Personal Loans
        • Personal Loan Refinance
      • Managing Debt
        • Navigating Medical Debt
        • Budgeting with a High-Interest Loan
        • Build a Debt-Repayment Fund
        • Debt Payoff for Single Parents
        • Save for a Wedding Without Debt
        • Medical Debt
        • Single Parent Debt
        • Personal Loan Debt
      • Debt Relief & Protection
        • When Bankruptcy Is an Option
        • Avoid Predatory Lenders & Scams
        • Negotiate with Creditors: Scripts
        • Budgeting Around Wage Garnishment
        • Debt Relief
        • Bankruptcy
        • Creditor Negotiation
        • Predatory Lenders
        • Wage Garnishment
    • Credit
      • Credit Scores
        • Credit Score 101
        • Check & Improve Your Credit Score
        • Credit Utilization: A Simple Fix
        • Check Your Credit Score Free
        • Rebuild Credit After a Setback
        • How Credit Scores Are Calculated
        • What Credit Scores Mean
        • Credit Health
      • Credit Reports
        • Read & Dispute Your Credit Report
        • Dispute Template That Works
        • How Long Negative Marks Last
        • Remove Negative Items
        • What to Expect as Items Age Off
        • Understanding Credit Utilization
        • Credit Basics
        • Checking Your Credit Score
      • Building Credit
        • Best Starter Credit Cards
        • Secured vs. Unsecured Cards
        • Secured Cards & Credit-Builder Loans
        • Build Credit as a Gig Worker
        • Boost Your Score Before a Mortgage
        • Borrow Now vs. Wait
        • Build Credit
        • Credit Cards for Beginners
        • Credit for Gig Workers
      • Credit Cards
        • Best Rewards Credit Cards
        • Credit Card Hacks: Intro APRs
        • Balance Transfers Explained
        • Earn Rewards Without Debt
        • Responsible Card Use & Rewards Tips
        • Lost or Stolen Card: What to Do
        • Credit Card Rewards
        • Balance Transfer Cards
      • Credit Protection & Safety
        • Identity Theft Checklist
        • Truth About Credit Freezes
        • How to Freeze & Thaw Your Credit
        • Credit Monitoring vs. Freezes
        • Credit Protection
        • Credit Freeze
        • Fraud Awareness
        • Financial Safety
    • Investing
      • Start Investing
        • Investing 101: Beginner’s Guide
        • Start Investing with $100
        • Start with $50/Month
        • Scared of the Market? Start Here
        • Open a Brokerage Account
        • Invest While Paying Down Debt
        • How to Start Investing
        • Start with Little Money
        • Fear of Investing
      • Investing Strategy
        • Roth IRA vs. Traditional IRA
        • Dollar-Cost Averaging Explained
        • DCA vs. Lump-Sum Investing
        • 5 Simple Starter Portfolios
        • Asset Allocation Beyond 60/40
        • How to Rebalance Your Portfolio
        • Diversify Your Portfolio
        • Investing Mistakes to Avoid
        • Investment Strategies
        • Diversification
      • Stocks
        • How the Stock Market Works
        • How to Make Money in Stocks
        • How to Read Stock Charts
        • Analyze Stocks in 5 Steps
        • P/E Ratio for Beginners
        • Bullish vs. Bearish Explained
        • How Stock Trading Works
        • Stock Market Basics
        • Stock Analysis
        • Stock Trading Strategies
      • Funds & Wealth Building
        • Beginner’s Guide to Index Funds
        • Best S&P 500 Index Funds
        • Mutual Funds vs. ETFs
        • How to Invest in ETFs
        • Dividend Investing for Beginners
        • Build a Dividend Income Stream
        • Maximize Your 401(k) Match
        • Build a Retirement Portfolio
        • Index Funds
        • Dividend Investing
      • Brokerages & Platforms
        • Vanguard vs. Fidelity
        • Fidelity vs. Schwab
        • Robinhood vs. E*Trade
        • Robo-Advisors vs. Human Advisors
        • Robo-Advisor or DIY Investing?
        • How Brokerage Fees Affect Returns
        • Manage Multiple Brokerage Accounts
        • Brokerages
        • Investment Platforms
        • Robo Advisors
    • Home
      • Home Buying
        • First-Time Homebuyer Checklist
        • How Much Down Payment You Need
        • How Much Home Can You Afford?
        • Renting vs. Buying
        • True Costs of Homeownership
        • Qualify as a First-Time Buyer
        • Buying a Fixer-Upper
        • First-Time Home Buyer
        • Home Affordability
      • Mortgage
        • First-Time Buyer’s Mortgage Guide
        • Fixed vs. Adjustable Mortgage
        • How to Refinance a Mortgage
        • Mortgage Payoff Strategies
        • Winning in a High-Rate Market
        • Mortgage Amortization Calculator
        • Down Payment Assistance Programs
        • Mastering Refinance Rate Locks
        • Mortgage Rates
        • Mortgage Refinance
        • Debt-to-Income Calculator
      • Real Estate Investing
        • Real Estate Crowdfunding Platforms
        • Rental Property Cash Flow
        • REITs for Passive Income
        • REITs vs. Direct Ownership
        • Fix-and-Flip Opportunities
        • Airbnb & Short-Term Rental ROI
        • Buying a Multi-Family Property
        • 1031 Exchange to Defer Taxes
        • Real Estate Investing
        • Rental Property
      • Home Insurance
        • Homeowners Insurance Guide
        • Compare Home Insurance Quotes
        • Best Home Insurance Companies
        • Choose Your Deductible
        • Renters vs. Homeowners Insurance
        • File a Property Insurance Claim
        • Home Insurance Coverage Basics
        • Home Insurance Rates
        • Home Insurance Claims
      • Home Equity & Ownership
        • Smart Ways to Use Home Equity
        • Save for a Down Payment
        • Down Payment Strategies
        • Estimate Property Appreciation
        • Home Equity
        • HELOC Payoff Strategy
        • Home Down Payment
        • Home Ownership
        • Home Renovation
    • Bank
      • Banking Basics
        • Open Your First Bank Account
        • Online Banks vs. Traditional Banks
        • How to Avoid Bank Fees
        • How to Switch Banks
        • Read Your Bank Statement
        • Second-Chance Checking Accounts
        • Get Better Rates from Your Bank
        • Banking Basics
        • How to Choose a Bank
        • Compare Banks
      • Checking Accounts
        • Best Checking Accounts
        • Choose the Right Checking Account
        • Overdraft Protection Guide
        • Stop Paying Overdraft Fees
        • The True Cost of Checking Fees
        • Mobile Check Deposits
        • How Long Checks Take to Clear
        • Checking Accounts
        • Best Checking Account
      • Savings Accounts & CDs
        • High-Yield Savings Explained
        • Best High-Yield Savings Account
        • Savings Accounts vs. CDs
        • What Is a CD?
        • Money Market vs. Savings Account
        • HYSA vs. Treasury Bills
        • How Savings Interest Is Calculated
        • Savings Account Minimum Balances
        • Savings Account
      • Bank Smarter
        • Top Banks for High-APY Savings
        • How Much Cash in Each Account
        • How Many Savings Accounts to Have
        • Managing Multiple Bank Accounts
        • Where to Put Your Money
        • When to Save vs. When to Invest
        • Savings Account Fees to Avoid
        • Banking Tips
        • Digital Banking
      • Banking Safety & Security
        • Set Up Bank Account Alerts
        • Avoid Check Scams
        • Missing Debit Card: Next Steps
        • When to Stop a Check Payment
        • Bank Fees
        • Debit Cards
        • Joint Bank Accounts
        • Banking How-To Guides
    • Sign In
    • Sign Up
    Amppfy
    Home » Banking » What Time Does Capital One Direct Deposit Hit? Early Paycheck and Posting Times
    Banking

    What Time Does Capital One Direct Deposit Hit? Early Paycheck and Posting Times

    Learn when Capital One posts your paycheck, why some arrive early, and whether a pending deposit can pay today's bill.
    Thomas T.By Thomas T.October 17, 2026Updated:October 17, 202610 Mins Read
    Facebook Twitter LinkedIn Email Copy Link
    What Time Does Capital One Direct Deposit Hit? Early Paycheck and Posting Times
    Share
    Facebook Twitter LinkedIn Email Copy Link

    Payday morning has a familiar rhythm. You wake up, open the Capital One app, and check whether the money is there yet. Some mornings it is. Some mornings the balance looks the same as it did last night, and the day’s plans start to wobble.

    If you’ve ever wondered what time Capital One direct deposit hits, you’re asking two questions at once. The first is about the clock: when does the money show up? The second is about what the money means. Can you pay the electric bill today, or should you wait?

    This guide answers both, calmly and in order. It covers what Capital One actually publishes and what it doesn’t. It explains why some paychecks arrive early, why some arrive late, and what a “pending” label means for your spending. It also gives you a short checklist for the morning nothing lands.

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

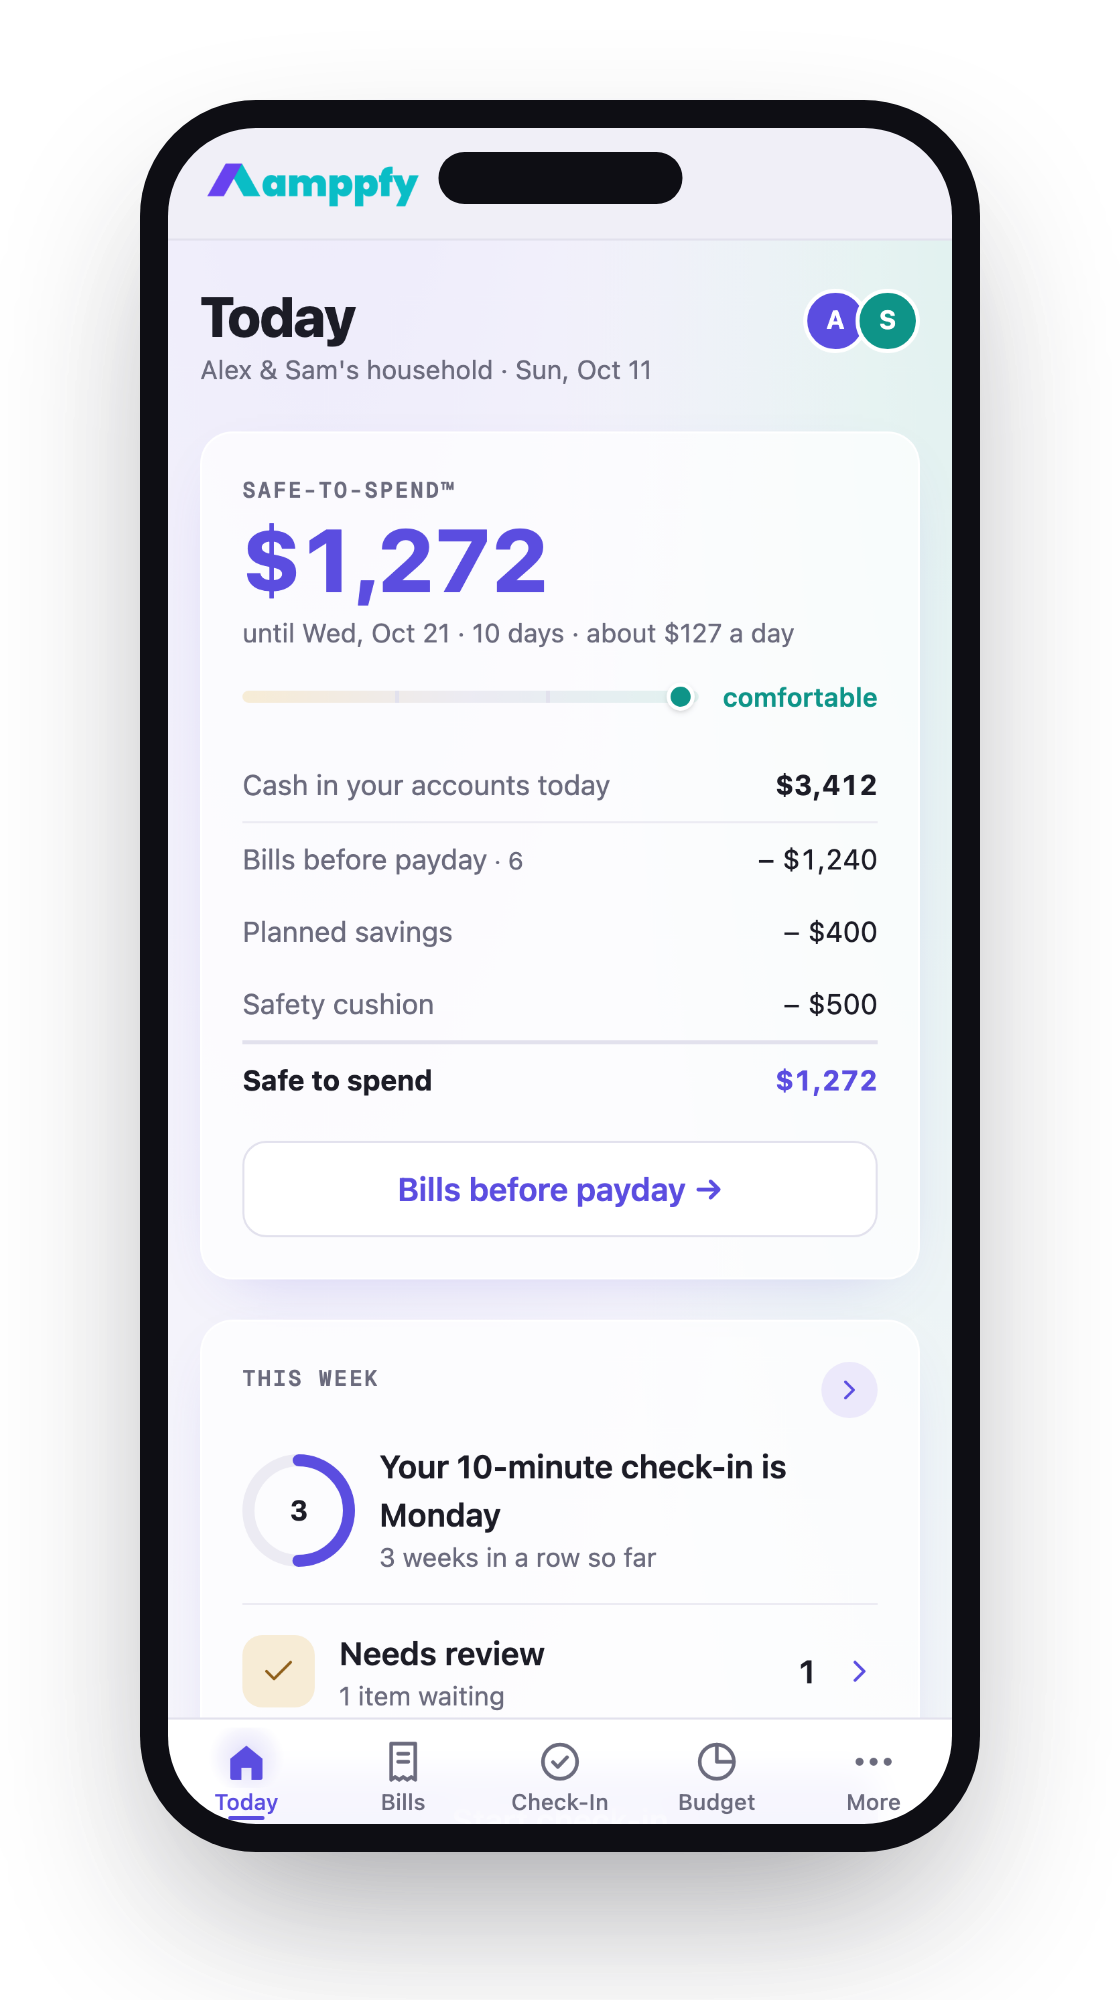
    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it

    Every bank fact here is stated the way Capital One states it, as of October 2026. Where the bank doesn’t publish a number, you’ll see that said plainly. No guessing, no invented times. Just the logic of how a paycheck moves from your employer to your account, and what to do once it gets there.

    What time Capital One posts direct deposits

    Start with the honest answer. Capital One does not publish a specific clock time for direct deposits on its website, as of October 2026. You’ll see times like “3 a.m.” passed around in forums. Those are anecdotes, not policy, so don’t build your bill schedule around them.

    What the bank controls is narrower than most people think. Your employer’s payroll provider sends a file through the ACH network. That file says “pay this person on this date.” Capital One receives the file, then posts the credit to your account.

    “Early” refers to the gap between those two moments. The file often arrives at the bank a day or two before the official pay date. A bank that offers early pay simply releases the money when the file arrives, instead of holding it until the settlement date.

    Think of it like a package that reaches the local post office on Wednesday but is scheduled for Friday delivery. An early-pay bank hands it to you Wednesday. A standard bank keeps it on the shelf until Friday.

    There’s also a rule-level backstop on the standard side. Effective September 18, 2026, a NACHA update requires institutions to make non-Same Day ACH credits available by 9:00 a.m. local time[1] on the settlement date. So even without early pay, your paycheck should be usable by mid-morning on payday.

    Does Capital One pay early? The policy as published

    Yes, for one account type. Capital One offers Early Paycheck on 360 Checking. As the bank describes it on its Early Paycheck page, eligible direct deposits may arrive up to two days early, and Capital One calls it a free, automatic feature for checking accounts enrolled in direct deposit. You don’t sign up or toggle anything. This is the published policy as of October 2026.

    Here’s what that wording means, line by line:

    Line What it is
    360 Checking The account that carries the feature. Other account types aren’t covered by this policy.
    Up to two days early A ceiling, not a promise. Your deposit might arrive two days early, one day early, or on payday.
    Automatic No enrollment step. If the deposit qualifies, it’s released when it arrives.
    Eligible direct deposits Electronic deposits of regular periodic payments, such as salary, pension, or government benefits. Capital One says certain non-payroll and tax payments are not eligible, and a bank-to-bank transfer doesn’t count.

    The phrase “up to” does the heavy lifting. Capital One can only release money it has received. If your employer’s payroll provider sends the file one day ahead, you get it one day ahead. If the file arrives the morning of payday, early pay has nothing to release early. Capital One’s fine print adds that eligibility may vary between pay periods and that daily and transaction limits apply, as of October 2026.

    So treat the early arrival as a pleasant bonus. Don’t treat it as the date a bill can safely pull. Your official pay date is still the date that matters for planning. If you want the longer view on this, here’s a clear breakdown of why your direct deposit lands early or late and how to plan around it.

    Weekends, holidays, and the first deposit from a new employer

    Three situations shift the timing more than anything else. Each one has a simple logic behind it.

    Weekends and federal holidays

    The ACH network settles on business days. If your payday falls on a Saturday, Sunday, or bank holiday, most employers send pay on the prior business day. Some send it the next business day instead. That choice belongs to your employer, not Capital One.

    Check your pay stub or ask payroll which rule they follow. Once you know, the pattern stays steady all year. A Friday holiday usually means a Thursday deposit. A Monday holiday can push pay to Tuesday if your employer uses the “next day” rule.

    Your first deposit from a new job

    First paychecks are often slow. Payroll needs your account and routing numbers, and many providers run a small test deposit or a “prenote” first. That can push your first real deposit to a paper check or to the following pay cycle.

    Plan as if your first deposit arrives on the official pay date, not early. If it shows up sooner, good. If it doesn’t, nothing in your plan breaks.

    A new Capital One account

    New accounts may not see early timing right away. Capital One’s fine print says it may take two cycles for your direct deposits to take effect, as of October 2026. Give the first couple of paychecks that room before you count on early arrival.

    Why a deposit shows as pending

    Two labels can show up in your app, and they mean different things.

    A pending deposit is money the bank knows about but hasn’t fully posted. A posted or available deposit is money you can use. With early pay, the line between them can blur, because the bank is releasing funds ahead of the settlement date.

    Here’s the plain rule. Look at your available balance, not the pending list. If the deposit is reflected in the available balance, it’s spendable. If it only appears as a pending item, wait. Capital One doesn’t publish an exact time when a pending payroll credit becomes available, as of October 2026, so the available balance is your source of truth.

    A quick example makes this concrete. Say your available balance is $340 and a $2,150 paycheck shows as pending. Your spendable money is $340, not $2,490. A rent autopay of $1,400 pulling right now would draw against the $340.

    Pending items can also change. Payroll occasionally corrects an amount or reissues a file. That’s rare, but it’s another reason to wait for the available balance before you move big money.

    What to do if payday passed and nothing landed

    It’s mid-morning on your official pay date. The available balance hasn’t moved. Before you call anyone, run this short check. It takes about ten minutes.

    1. Confirm the date. Is today the real pay date, or the early date you’re used to? Early arrival isn’t guaranteed. If today is a weekend or holiday, check the prior business day.
    2. Check the clock. Under the NACHA rule effective September 2026, standard ACH credits should be available by 9:00 a.m. local time on settlement day. If it’s 7 a.m., give it time.
    3. Look at your pay stub. Most payroll portals show the deposit date and the last four digits of the account. Confirm the account number is your 360 Checking account.
    4. Ask payroll if the file went out. Late payroll runs and missed cut-offs are the most common cause. Your employer can see whether the file was sent and when.
    5. Contact Capital One with details. If payroll confirms the file went out and the date has passed, call the bank. Have the pay date, amount, and employer name ready.

    Meanwhile, look at what’s due today and tomorrow. If an autopay will hit before the money arrives, many billers let you push a payment a few days with a quick call. A short delay on one bill is ordinary. It’s a phone call, not a crisis.

    The deposit landed. What is actually safe to spend?

    The number on your screen just jumped. That’s the moment most budgets go sideways, because the full balance looks like spending money. It isn’t.

    Your Safe-to-Spend™ amount is the balance minus three things, in a set order. Here’s how the math works with a real example.

    Line Amount
    Available balance after payday $2,490
    Bills due before next payday (rent $1,400, phone $65, car insurance $112) − $1,577
    Planned savings this cycle − $200
    Safety cushion you choose − $150
    Safe-to-Spend™ until next payday $563

    Read it top to bottom. Bills come out first, because they’ll pull whether you remember them or not. Savings comes next, so it doesn’t get eaten by whatever’s left. The cushion goes last. It covers the grocery run that costs more than planned or the gas price bump.

    That $563 has to last until the next paycheck. With 14 days in the cycle, that’s about $40 a day. You can see the arithmetic, so you can trust the result.

    Early pay changes the timing, not the math. Getting paid two days sooner means your cycle starts two days sooner too. The bills don’t move. If you spend from the early balance as if it’s extra, the next cycle starts thinner.

    FAQ

    What time does Capital One direct deposit hit on payday?
    Capital One doesn’t publish a specific posting time, as of October 2026. Under the NACHA rule effective September 18, 2026, standard ACH credits must be available by 9:00 a.m. local time on settlement day. With Early Paycheck on 360 Checking, eligible deposits can arrive up to two days sooner.

    Do I need to sign up for Early Paycheck?
    No. Capital One describes Early Paycheck on 360 Checking as automatic for eligible direct deposits, as of October 2026. There’s no enrollment step or setting to turn on.

    Why did my paycheck come early last time but not this time?
    Early timing depends on when your employer’s payroll file reaches the bank. If payroll sends it later than usual, there’s nothing to release early. That’s why “up to two days early” is a ceiling, not a fixed date.

    Is a pending deposit safe to spend?
    Go by your available balance. If the deposit is included there, you can use it. If it only shows as pending, wait until it moves into the available balance before paying bills against it.

    Once the deposit lands, remember the order. The balance is not what’s safe to spend. Bills due before the next payday come out first, then planned savings, then your cushion. What’s left is the real number. Amppfy does that arithmetic for you on iPhone and the web, with the four lines printed under the number and your lowest-cash day marked on the calendar. You type in your balances yourself, no bank login, and a 10-minute weekly check-in keeps it current. Take ten minutes this week to set up your Safe-to-Spend™ number in Amppfy before your next payday.

    1. nacha.org

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it
    Banking Basics Banking How-To Guides Banking Tips Checking Checking Account
    Share. Facebook Twitter LinkedIn Email Copy Link
    Previous ArticleWhat Time Does Navy Federal Direct Deposit Hit? Early Pay for Military Paydays
    Next Article What Time Does SoFi Direct Deposit Hit? Up to Two Days Early, Explained
    Thomas T.

    Thomas is a Personal Finance Writer and Financial Content Strategist with over 10 years of experience helping individuals make smarter financial decisions. He specializes in topics such as budgeting, debt management, saving strategies, and financial behavior, translating complex financial concepts into clear, actionable guidance. His work focuses on empowering readers to build sustainable financial habits and confidently navigate their financial lives, combining data-driven insights with practical, real-world advice.

    More Like This

    Truist Joint Account: How to Add a Partner to Checking

    By Thomas T.October 17, 2026

    U.S. Bank Joint Account: Adding a Partner or Opening One Together

    By Thomas T.October 17, 2026

    Online Banks That Offer Joint Accounts: Who Does, Who Doesn’t, and How to Open One

    By Thomas T.October 17, 2026
    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number.

    Download on the App Store

    Prefer the web? Sign up free ›

    Amppfy dashboard on an iPhone showing the Safe to Spend number with the math under it
    Helpful Resources

    Truist Joint Account: How to Add a Partner to Checking

    October 17, 2026

    U.S. Bank Joint Account: Adding a Partner or Opening One Together

    October 17, 2026

    Online Banks That Offer Joint Accounts: Who Does, Who Doesn’t, and How to Open One

    October 17, 2026

    Joint Bank Accounts for Unmarried Couples: What Changes, What Doesn’t, and How to Set One Up

    October 17, 2026

    Financial Clarity. Everyday Confidence.

    Facebook X (Twitter) YouTube LinkedIn
    Calculators

    Emergency Fund Calculator

    Compound Interest Calculator

    Interest Rate Calculator

    Net Worth Calculator

    Mortgage Calculator

    How Much Home Can I Afford

    Debt-to-Income Ratio Calculator

    Cost of Living Calculator

    Savings Calculator

    Savings Goal Calculator

    Monthly Budget Calculator

    Latest Resources

    Average Money Left Over After Bills in 2026: What the Numbers Say and Why Yours Differs

    October 17, 2026

    Disposable Income: What It Means, and What’s Actually Yours to Spend

    October 17, 2026

    How Much Money Should You Have Left After Bills? A Per-Paycheck Answer

    October 17, 2026

    Truist Joint Account: How to Add a Partner to Checking

    October 17, 2026
    About & Legal

    About Amppfy

    Documentation

    Editorial Policy

    EULA

    Terms of Use

    Acceptable Use Policy

    Privacy Policy

    Cookie Policy

    Disclaimer

    Do Not Sell or Share My Personal Information

    Acceptable Use Policy

    Disclaimer: Amppfy is committed to keeping its information transparent, accurate, and up-to-date. The information on Amppfy is provided for educational and informational purposes only and should NOT be considered financial, investment, tax, or legal advice. You should consult a qualified financial professional before making any financial decisions. This information may differ from what you find on the specific product or service provider’s website. All information, content, software, tools, products, or services on Amppfy are presented without warranty or guarantee. Please review the specific provider’s terms and conditions when evaluating products or services. By accessing Amppfy or using our AI generator tools, you acknowledge that you have read, understood, and agreed to our EULA, Terms of Use, Acceptable Use Policy, Privacy Policy, Cookie Policy, and Disclaimer. Amppfy.com uses cookies. For more information, visit Amppfy’s Cookie Policy. Amppfy may be compensated through third-party advertisers and affiliates. For more information, visit Amppfy’s Disclaimer.

    Copyright© 2026 Amppfy | All Rights Reserved

    Type above and press Enter to search. Press Esc to cancel.

    Advertiser Disclosure: Products may include affiliate links related to financial products or services. We may earn a commission at no additional cost to you. Our content remains independent and focused on helping you make informed financial decisions.
    Fact Checked
    Financial Disclaimer

    This content is for informational and educational purposes only and should not be considered financial advice. Personal finance decisions—including budgeting, saving, investing, credit, mortgages, taxes, and debt management—depend on your individual circumstances. Always consult a qualified financial professional before making financial decisions.

    Editorial Standards and Content Integrity

    Our editorial process ensures accuracy, clarity, and trust across all personal finance topics, including budgeting, saving, investing, and debt management. Content is created using credible sources such as government agencies, academic research, and established financial institutions, and may incorporate insights from industry experts when relevant. Each article is reviewed for accuracy, timeliness, and relevance before publication and updated as needed to reflect changes in financial guidelines and best practices, with the goal of providing clear, evidence-based information to help readers make informed financial decisions.

    Learn more about our editorial policy and guideline.
    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Download the app and enter your balances, bills, and payday. About ten minutes to one clear number: what’s safe to spend before payday.Your balances, bills, and payday. Ten minutes to one clear number. Learn more ›

    Download on the App Store
    Scan with your iPhone to get the app

    Free  ·  No credit card  ·  Just your balances

    Prefer the web? Sign up free ›

    Amppfy app icon

    Amppfy

    Free on iPhone and the web

    Know what’s safe to spend before payday

    Enter your balances, bills, and payday once. About ten minutes to one clear number, with the math shown under it.

    Download on the App Store
    Scan with your iPhone to get the app

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances