Close Menu

    Subscribe to Updates

    Get the latest creative news from FooBar about art, design and business.

    What's Hot

    Social Security COLA 2027: What the 3.6% Raise Means for Your Monthly Plan

    November 6, 2026

    Best Free Budget Apps in 2026: iPhone, Android, and Web

    November 6, 2026

    Federal Pay Period Calendar for 2027: Every Pay Period and Payday

    November 6, 2026
    Facebook X (Twitter) Instagram
    Amppfy
    • Safe to Spend™ App
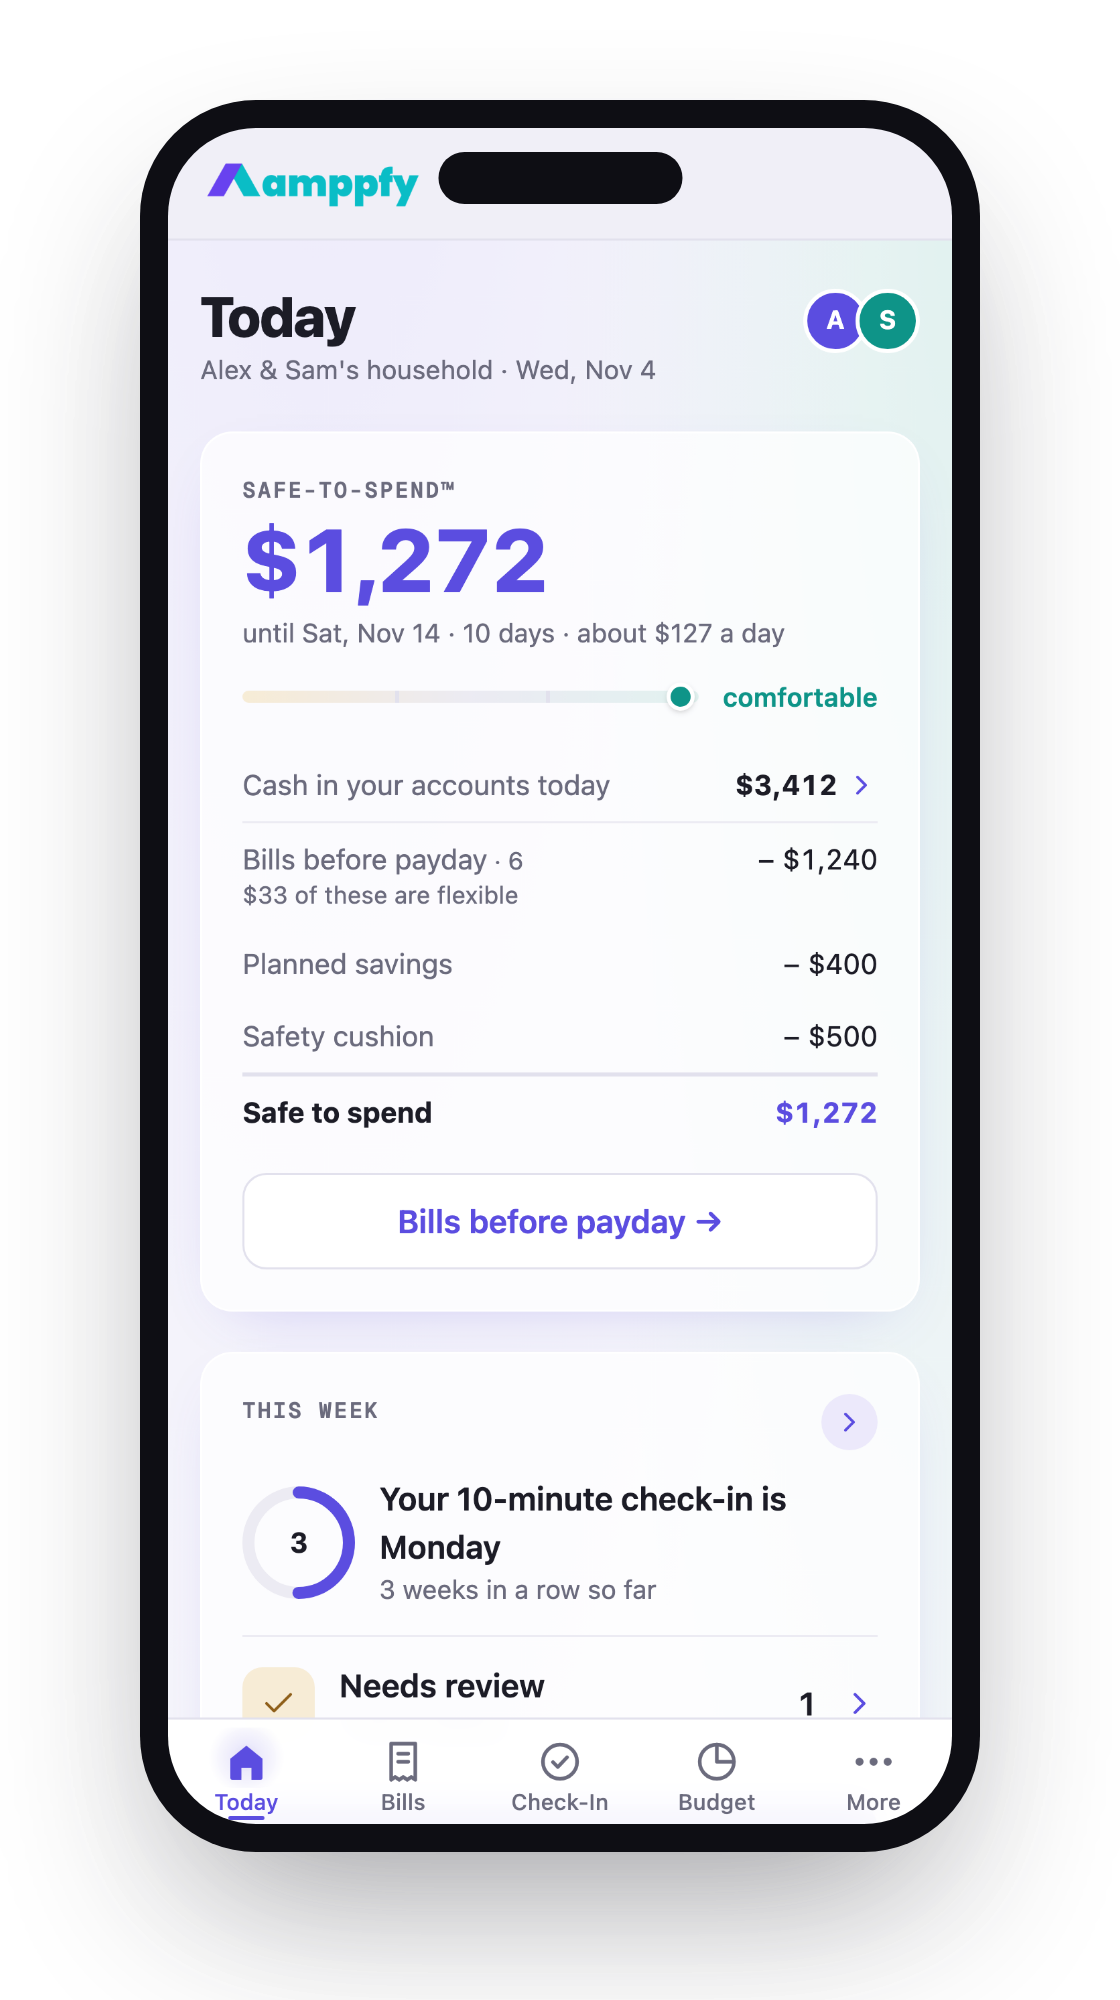
      • Amppfy on iPhone — one clear number with the status scale and the math under itYour number, in your pocketFree on iPhone and Android, with the same account on the web.
        • Download on the App Store
        • Get it on Google Play
        • Prefer the web? Sign up free ›
      • The app
        • OverviewOne clear number for what’s safe to spend before payday
        • Safe-to-Spend™The four-line math, always shown
        • Weekly check-inTen minutes a week keeps it honest
      • Features
        • Bills & paydaysEvery bill and payday on one calendar
        • GoalsSavings that fund themselves first
        • For couplesTwo logins, one number you both trust
        • SubscriptionsWhat you pay monthly, and what cancelling gives back
        • Calendar & heads-upsYour month at a glance, a heads-up before bills land
        • Net worth & payday nudgeThe whole picture, month by month
        • BudgetWhere the month’s money goes, month by month
      • Trust & help
        • Security & privacyJust your balances, optional two-step verification
        • Help centerSetup, the number, check-ins, FAQ
        • Open the web appSame account, any browser
    • Personal Finance
      • Money Basics
        • How to Master Money Management
        • Psychology of Money Habits
        • How to Set Financial Goals
        • Money Management for Every Life Stage
        • Beyond Budgeting: Advanced Money Skills
        • Financial Literacy
        • Money Management
        • Know Your Money
        • Cash Flow
      • Financial Wellness
        • Understand Your Money Relationship
        • Build a Healthy Money Mindset
        • 7 Money Tips for Financial Freedom
        • Take the Money Health Quiz
        • Monthly Financial Reviews
        • Money Habits
        • Money Mindset
        • Financial Goals
        • Financial Independence
      • Side Hustles & Extra Income
        • 8 Realistic Side Hustles
        • How to Make Money Online
        • Passive Income Ideas That Work
        • Passive Income 101: Ideas That Scale
        • Spot a Bad Passive Income Deal
        • Start Freelance Writing: First $1,000
        • Budgeting with Irregular Income
        • Side Hustle Ideas
        • Passive Income
        • Gig Economy
      • Major Money Decisions
        • Plan a Major Purchase Without Debt
        • Car Buying: Save, Finance, or Lease?
        • Used Car Buying & Negotiation Tips
        • What to Save For vs. Finance
        • Life Insurance 101: Coverage Needs
        • Term vs. Whole Life Insurance
        • Buying a Car
        • Major Purchase Planning
        • Home Improvement
        • Life Insurance
      • Money Tools & Calculators
        • Net Worth Calculator
        • Cost of Living Calculator
        • Compound Interest Calculator
        • Monthly Budget Calculator
        • Savings Goal Calculator
        • Emergency Fund Calculator
        • Savings Calculator
        • Do Money Management Tools Work?
        • Spend Tracking
        • Net Worth
    • Savings
      • Budgeting Tips
        • The 50/30/20 Rule Explained
        • How to Make a Monthly Budget
        • How to Budget Money in 5 Steps
        • The Envelope Method Explained
        • Best Budgeting Apps Compared
        • Common Budgeting Mistakes
        • Budgeting for Couples
        • Start a Budget
        • Budget Methods
        • 50/30/20 Budgeting
      • Ways to Save
        • Save $500 This Month
        • 14 Ways to Cut Monthly Expenses
        • How to Save Money on Groceries
        • Lower Your Utility Bills
        • Budget Swaps for Big Purchases
        • Save Money on Car Insurance
        • Cut Expenses
        • Groceries Savings
        • Smart Saving Strategies
      • Emergency Fund
        • How Much Emergency Fund to Save
        • How to Build an Emergency Fund
        • Start a Rainy Day Fund
        • Sinking Funds vs. Emergency Fund
        • Emergency Fund Essentials
        • Where to Keep Your Emergency Fund
        • Best Emergency Fund Tips
        • Emergency Savings
        • Emergency Buffer
      • Savings Goals & Plans
        • How to Create a Savings Plan
        • How to Set Savings Goals
        • Track Spending Without Spreadsheets
        • 529 College Savings on a Budget
        • Saving During a Recession
        • Budget a Debt-Free Vacation
        • Vacation Budgeting
        • Family Budgeting
        • Savings Goals
        • Recession Saving
      • Savings Tools & Planning
        • Budget Calculator
        • Savings Goal Calculator
        • Emergency Fund Calculator
        • Savings Calculator
        • Compound Interest Calculator
        • Savings Buckets
        • Sinking Funds
        • Maximize Your Savings
        • Savings Tips
        • Savvy Saver
    • Debt
      • Get Out of Debt
        • Debt Snowball vs. Avalanche
        • Pay Off Credit Card Debt Fast
        • Beginner’s Credit Card Payoff Plan
        • Build a Debt Payoff Calendar
        • Use Windfalls to Crush Debt
        • Debt Free Journey
        • Debt Payoff
        • Credit Card Debt
      • Student & Auto Loans
        • Student Loans 101
        • Get Out of Student Loan Debt
        • Income-Driven Repayment Plans
        • Best Student Loan Repayment Option
        • Auto Loans: Shop & Save on Interest
        • Pay Off Your Auto Loan Early
        • Student Loans
        • Auto Loans
        • Auto Loan Debt
      • Debt Consolidation
        • Debt Consolidation Pros & Cons
        • Is Consolidating Debt Right for You?
        • Balance Transfers to Pay Off Debt
        • HELOC to Pay Off Credit Cards
        • 401(k) Rollover to Pay Down Debt
        • How to Refinance a Personal Loan
        • Before You Take a Personal Loan
        • Personal Loans
        • Personal Loan Refinance
      • Managing Debt
        • Navigating Medical Debt
        • Budgeting with a High-Interest Loan
        • Build a Debt-Repayment Fund
        • Debt Payoff for Single Parents
        • Save for a Wedding Without Debt
        • Medical Debt
        • Single Parent Debt
        • Personal Loan Debt
      • Debt Relief & Protection
        • When Bankruptcy Is an Option
        • Avoid Predatory Lenders & Scams
        • Negotiate with Creditors: Scripts
        • Budgeting Around Wage Garnishment
        • Debt Relief
        • Bankruptcy
        • Creditor Negotiation
        • Predatory Lenders
        • Wage Garnishment
    • Credit
      • Credit Scores
        • Credit Score 101
        • Check & Improve Your Credit Score
        • Credit Utilization: A Simple Fix
        • Check Your Credit Score Free
        • Rebuild Credit After a Setback
        • How Credit Scores Are Calculated
        • What Credit Scores Mean
        • Credit Health
      • Credit Reports
        • Read & Dispute Your Credit Report
        • Dispute Template That Works
        • How Long Negative Marks Last
        • Remove Negative Items
        • What to Expect as Items Age Off
        • Understanding Credit Utilization
        • Credit Basics
        • Checking Your Credit Score
      • Building Credit
        • Best Starter Credit Cards
        • Secured vs. Unsecured Cards
        • Secured Cards & Credit-Builder Loans
        • Build Credit as a Gig Worker
        • Boost Your Score Before a Mortgage
        • Borrow Now vs. Wait
        • Build Credit
        • Credit Cards for Beginners
        • Credit for Gig Workers
      • Credit Cards
        • Best Rewards Credit Cards
        • Credit Card Hacks: Intro APRs
        • Balance Transfers Explained
        • Earn Rewards Without Debt
        • Responsible Card Use & Rewards Tips
        • Lost or Stolen Card: What to Do
        • Credit Card Rewards
        • Balance Transfer Cards
      • Credit Protection & Safety
        • Identity Theft Checklist
        • Truth About Credit Freezes
        • How to Freeze & Thaw Your Credit
        • Credit Monitoring vs. Freezes
        • Credit Protection
        • Credit Freeze
        • Fraud Awareness
        • Financial Safety
    • Investing
      • Start Investing
        • Investing 101: Beginner’s Guide
        • Start Investing with $100
        • Start with $50/Month
        • Scared of the Market? Start Here
        • Open a Brokerage Account
        • Invest While Paying Down Debt
        • How to Start Investing
        • Start with Little Money
        • Fear of Investing
      • Investing Strategy
        • Roth IRA vs. Traditional IRA
        • Dollar-Cost Averaging Explained
        • DCA vs. Lump-Sum Investing
        • 5 Simple Starter Portfolios
        • Asset Allocation Beyond 60/40
        • How to Rebalance Your Portfolio
        • Diversify Your Portfolio
        • Investing Mistakes to Avoid
        • Investment Strategies
        • Diversification
      • Stocks
        • How the Stock Market Works
        • How to Make Money in Stocks
        • How to Read Stock Charts
        • Analyze Stocks in 5 Steps
        • P/E Ratio for Beginners
        • Bullish vs. Bearish Explained
        • How Stock Trading Works
        • Stock Market Basics
        • Stock Analysis
        • Stock Trading Strategies
      • Funds & Wealth Building
        • Beginner’s Guide to Index Funds
        • Best S&P 500 Index Funds
        • Mutual Funds vs. ETFs
        • How to Invest in ETFs
        • Dividend Investing for Beginners
        • Build a Dividend Income Stream
        • Maximize Your 401(k) Match
        • Build a Retirement Portfolio
        • Index Funds
        • Dividend Investing
      • Brokerages & Platforms
        • Vanguard vs. Fidelity
        • Fidelity vs. Schwab
        • Robinhood vs. E*Trade
        • Robo-Advisors vs. Human Advisors
        • Robo-Advisor or DIY Investing?
        • How Brokerage Fees Affect Returns
        • Manage Multiple Brokerage Accounts
        • Brokerages
        • Investment Platforms
        • Robo Advisors
    • Home
      • Home Buying
        • First-Time Homebuyer Checklist
        • How Much Down Payment You Need
        • How Much Home Can You Afford?
        • Renting vs. Buying
        • True Costs of Homeownership
        • Qualify as a First-Time Buyer
        • Buying a Fixer-Upper
        • First-Time Home Buyer
        • Home Affordability
      • Mortgage
        • First-Time Buyer’s Mortgage Guide
        • Fixed vs. Adjustable Mortgage
        • How to Refinance a Mortgage
        • Mortgage Payoff Strategies
        • Winning in a High-Rate Market
        • Mortgage Amortization Calculator
        • Down Payment Assistance Programs
        • Mastering Refinance Rate Locks
        • Mortgage Rates
        • Mortgage Refinance
        • Debt-to-Income Calculator
      • Real Estate Investing
        • Real Estate Crowdfunding Platforms
        • Rental Property Cash Flow
        • REITs for Passive Income
        • REITs vs. Direct Ownership
        • Fix-and-Flip Opportunities
        • Airbnb & Short-Term Rental ROI
        • Buying a Multi-Family Property
        • 1031 Exchange to Defer Taxes
        • Real Estate Investing
        • Rental Property
      • Home Insurance
        • Homeowners Insurance Guide
        • Compare Home Insurance Quotes
        • Best Home Insurance Companies
        • Choose Your Deductible
        • Renters vs. Homeowners Insurance
        • File a Property Insurance Claim
        • Home Insurance Coverage Basics
        • Home Insurance Rates
        • Home Insurance Claims
      • Home Equity & Ownership
        • Smart Ways to Use Home Equity
        • Save for a Down Payment
        • Down Payment Strategies
        • Estimate Property Appreciation
        • Home Equity
        • HELOC Payoff Strategy
        • Home Down Payment
        • Home Ownership
        • Home Renovation
    • Bank
      • Banking Basics
        • Open Your First Bank Account
        • Online Banks vs. Traditional Banks
        • How to Avoid Bank Fees
        • How to Switch Banks
        • Read Your Bank Statement
        • Second-Chance Checking Accounts
        • Get Better Rates from Your Bank
        • Banking Basics
        • How to Choose a Bank
        • Compare Banks
      • Checking Accounts
        • Best Checking Accounts
        • Choose the Right Checking Account
        • Overdraft Protection Guide
        • Stop Paying Overdraft Fees
        • The True Cost of Checking Fees
        • Mobile Check Deposits
        • How Long Checks Take to Clear
        • Checking Accounts
        • Best Checking Account
      • Savings Accounts & CDs
        • High-Yield Savings Explained
        • Best High-Yield Savings Account
        • Savings Accounts vs. CDs
        • What Is a CD?
        • Money Market vs. Savings Account
        • HYSA vs. Treasury Bills
        • How Savings Interest Is Calculated
        • Savings Account Minimum Balances
        • Savings Account
      • Bank Smarter
        • Top Banks for High-APY Savings
        • How Much Cash in Each Account
        • How Many Savings Accounts to Have
        • Managing Multiple Bank Accounts
        • Where to Put Your Money
        • When to Save vs. When to Invest
        • Savings Account Fees to Avoid
        • Banking Tips
        • Digital Banking
      • Banking Safety & Security
        • Set Up Bank Account Alerts
        • Avoid Check Scams
        • Missing Debit Card: Next Steps
        • When to Stop a Check Payment
        • Bank Fees
        • Debit Cards
        • Joint Bank Accounts
        • Banking How-To Guides
    • Sign In
    • Sign Up
    Amppfy
    Home » Banking » U.S. Bank Joint Account: Adding a Partner or Opening One Together
    Banking

    U.S. Bank Joint Account: Adding a Partner or Opening One Together

    Decide whether to add your partner to existing U.S. Bank checking or open new, then compare the fees and waivers.
    Thomas T.By Thomas T.October 17, 2026Updated:November 5, 202610 Mins Read
    Facebook Twitter LinkedIn Email Copy Link
    U.S. Bank Joint Account: Adding a Partner or Opening One Together
    Share
    Facebook Twitter LinkedIn Email Copy Link

    Two paychecks, one rent payment, and a grocery bill that somehow lands on whoever’s card is closest. That’s how a lot of couples end up looking at a shared account. If you already bank with U.S. Bank, the question gets more specific. Do you add your partner to the checking account you have, or start fresh with a new one in both names?

    Either path can work. They aren’t the same process, and U.S. Bank doesn’t publish the same instructions for both. One is a short online application. The other takes a phone call or a branch visit.

    This guide walks through what a U.S. Bank joint account actually is, how each route works, and what each of you can do once you’re both on it. It also covers the fees, the waivers, and how to keep two people looking at the same honest number without adding a chore to your week.

    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store Get it on Google Play

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it

    No pressure, no panic. Just the steps, the costs, and the arithmetic.

    Joint accounts at U.S. Bank: what they are and who can be on one

    A joint account is one account with two or more owners. Not a primary owner and a helper: owners, plural, on equal footing. U.S. Bank says that on joint checking, all owners have equal access and equal legal responsibility[1] for the account (as of October 2026).

    That equal footing is the whole point. It’s also the part to think through before you sign.

    Here’s what “equal” means in practice:

    • Equal access: each of you can deposit, withdraw, pay bills, and use the money.
    • Equal responsibility: if the account goes negative, both of you are on the hook.
    • Separate tools: each owner can have their own debit card and their own online banking login (as of October 2026).

    Who can be on one? Partners, spouses, a parent and an adult child, roommates splitting utilities. The bank cares that every owner applies and is verified. Your relationship doesn’t need to be legal or permanent.

    One more thing to read before opening: the account agreement. It spells out ownership terms, including what happens to the balance if one owner dies. Ten minutes with that document now saves confusion later.

    Add a partner to an existing account vs open a new joint account

    You have two routes. They look similar on paper. They aren’t.

    Opening a new joint account is the path U.S. Bank documents clearly. You pick a checking account, choose the joint option, and add your partner during the application. It’s online, it’s published, and you can do it tonight.

    Adding someone to an account you already own is different. U.S. Bank doesn’t publish online steps for adding an owner to an existing account (as of October 2026). If you want that route, call 800-USBANKS or visit a branch. Bring your questions, and expect your partner to need ID too.

    So which should you pick? A quick way to decide:

    Situation Better fit
    Your current account has years of autopays tied to it Add your partner (call or branch)
    You want a clean “household bills” account Open a new joint account
    You want to keep your own account private Open a new joint account
    You want it done online today Open a new joint account

    Many couples land on the new account. It gives you a fresh start, a clear purpose, and your old account stays yours.

    There’s also a third option if you don’t want shared ownership at all. U.S. Bank offers Shared Access, which gives someone limited access to an account without making them an owner (as of October 2026). It works well for a partner who helps pay bills but shouldn’t carry legal responsibility.

    Step by step

    These are the steps U.S. Bank lists on its own guide to opening a joint checking account, as of October 2026.

    Online

    1. Choose a checking account. Pick the one that fits your balances and deposits. More on fees below.
    2. Select the joint option. This tells the application there will be more than one owner.
    3. Finish your own details. Name, address, ID info, the usual.
    4. Add your co-applicant. At the end of the application, select Yes to add a co-applicant. Enter their name, email, and phone number.
    5. Your partner completes their part. They’ll get what they need to finish their side.

    In a branch

    All joint owners must be present. Each of you needs a valid government-issued ID. Bring the minimum opening deposit too.

    That last point catches couples off guard. You can’t send one person in with both IDs. Pick a time you’re both free, and the visit is simple.

    Adding to an existing account

    Again, U.S. Bank doesn’t publish online steps for this (as of October 2026). Call 800-USBANKS or visit a branch, and ask exactly what both of you need to bring.

    What each of you can see, move, and close

    Joint ownership is like a house with two front-door keys. Either key opens the door. Neither key opens it halfway.

    Once you’re both owners, each of you can see the full balance and every transaction. Each of you can move money in or out. Each of you has your own debit card and your own login (as of October 2026). There’s no “view only” setting between owners.

    That symmetry is a feature if you trust each other with the shared money. It’s worth a calm conversation if you haven’t talked about it yet. A few questions to settle early:

    • Is this account only for shared bills, or for everything?
    • Is there a dollar amount either of you checks in about before spending?
    • Who watches for the next big bill?

    What about closing it or removing someone? U.S. Bank doesn’t publish online steps for removing an owner or closing a joint account (as of October 2026). Call 800-USBANKS or visit a branch for the current process. Don’t guess, and don’t assume one person can quietly undo a shared account.

    Equal responsibility also applies to overdrafts. U.S. Bank waives overdraft fees if the account’s available balance is brought to $0 or more by 11:00 p.m. ET the next business day[2] (as of October 2026). Either of you can make that transfer. Agree now on who does it.

    Fees, minimums, and waivers

    Bank Smartly® Checking is the checking account many joint applicants consider. Here’s what U.S. Bank publishes for it on its Bank Smartly Checking page[3], as of October 2026.

    Item Detail (as of October 2026)
    Monthly maintenance fee $12
    Minimum opening deposit $25
    Waiver: balance $1,500 minimum balance
    Waiver: direct deposit $1,500+ in monthly direct deposits
    Waiver: age Ages 13 to 24, or 65+
    Waiver: military U.S. Military members
    Waiver: other Other listed groups on the U.S. Bank page

    U.S. Bank’s page doesn’t spell out how the waiver applies when two owners share one account (as of October 2026), so ask before you count on one person’s deposits. Direct deposits land in the account either way, so one paycheck routed there may clear the threshold on its own.

    Here’s the math, step by step:

    • No waiver: $12 x 12 months = $144 a year.
    • With a waiver: $0 a year.
    • Example: you each get paid $1,100 every two weeks. Route both paychecks to the joint account and monthly direct deposits run about $4,400. That clears $1,500 easily.

    If you’d rather route only part of your pay there, check that it still totals $1,500 or more each month. A bills-only account can fall short if it’s funded by transfer instead of direct deposit.

    Joint, separate, or both: how couples actually use it

    There’s no single right setup. Most couples land in one of three.

    All joint. Both paychecks go in, everything comes out. Simple, transparent, and very little to manage. It works best when spending styles roughly match.

    All separate. Each person pays agreed bills from their own account. This keeps independence intact but means more Venmo requests and more “did you pay the electric?” texts.

    Hybrid. A shared account covers rent, utilities, groceries, and insurance. Each of you keeps a personal account for everything else. This is where a lot of couples settle, and it’s where a new joint account shines.

    The hybrid model raises one practical question: how much does each person put in? Two common answers:

    • 50/50: each covers half of shared bills. Clean, but tight for the lower earner.
    • Proportional: contributions match income share. If one of you earns $60,000 and the other $40,000, shared bills split 60/40.

    For more on choosing, see this breakdown of bank accounts for couples, joint, separate, or both. If you go the hybrid route, here’s how to work out how much to put into a bills-only joint account each payday.

    One number for two people

    A shared account solves where the money lives. It doesn’t solve the question you both ask most: can we spend this right now?

    The bank app shows a balance. That balance includes rent due Friday. It doesn’t know about the car insurance next Tuesday. So one of you glances at it and sees room. The other remembers the bills and sees none. That gap causes more friction than the account itself.

    The fix is arithmetic, not willpower. Take what’s in the account. Subtract bills due before the next payday. Subtract planned savings. Subtract a small cushion. What’s left is the honest number.

    Here’s a quick example:

    • Joint balance: $3,200
    • Bills due before payday: $1,850
    • Planned savings: $300
    • Cushion: $200
    • Left to spend: $850

    Amppfy does this as its Safe-to-Spend™ number, with that four-line math printed right under it. Each partner gets their own login on iPhone, Android, or the web and sees the same number. Personal accounts stay private, so the hybrid setup still holds. You type balances in yourself, no bank login, and a ten-minute weekly check-in keeps it current.

    If you’re opening a joint account this month, set up a shared number for the two of you the same week.

    Comparing banks? Here is the list of online banks that offer joint accounts, with each bank’s own steps.

    FAQ

    Can I add my partner to my existing U.S. Bank checking account online?

    U.S. Bank doesn’t publish online steps for adding an owner to an existing account (as of October 2026). Call 800-USBANKS or visit a branch. The online joint option applies when you open a new account.

    Do we both need to go to the branch?

    Yes, if you open in person. All joint owners must be present with a valid government ID and the minimum opening deposit (as of October 2026). Opening online avoids the trip.

    Does each of us get our own debit card and login?

    Yes. U.S. Bank says each owner can have their own debit card and their own login (as of October 2026). Both of you have equal access and equal legal responsibility.

    Is there a way to share access without making someone an owner?

    Yes. Shared Access gives someone limited access without ownership (as of October 2026). It suits a partner who helps with bills but shouldn’t be legally responsible for the account.

    A U.S. Bank joint account is simple once you know which door you’re walking through. New account: online, published steps, done tonight. Existing account: a call or a branch visit. Either way, you both get equal access, equal responsibility, and your own card and login.

    Pick the setup that matches how you already live: joint, separate, or a hybrid with a bills account in the middle. Check the fee waiver math once. Then agree on one number you both trust.

    Take 15 minutes this week: choose the account, add your partner, and talk through the first payday together.

    1. usbank.com

    2. usbank.com

    3. usbank.com

    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number, with the math shown under it. Learn more ›

    Download on the App Store Get it on Google Play

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances

    Amppfy on an iPhone showing the Safe-to-Spend™ number with the status scale and the math under it
    Bank Account Setup Banking How-To Guides Checking Account Couples Budgeting Joint Accounts Joint Bank Accounts
    Share. Facebook Twitter LinkedIn Email Copy Link
    Previous ArticleOnline Banks That Offer Joint Accounts: Who Does, Who Doesn’t, and How to Open One
    Next Article Truist Joint Account: How to Add a Partner to Checking
    Thomas T.

    Thomas is a Personal Finance Writer and Financial Content Strategist with over 10 years of experience helping individuals make smarter financial decisions. He specializes in topics such as budgeting, debt management, saving strategies, and financial behavior, translating complex financial concepts into clear, actionable guidance. His work focuses on empowering readers to build sustainable financial habits and confidently navigate their financial lives, combining data-driven insights with practical, real-world advice.

    More Like This

    One Household, Two Phones: Budget Apps That Work on iPhone and Android Together

    By Thomas T.November 6, 2026

    How to Open a Joint Bank Account Online (Without a Branch Visit)

    By Thomas T.October 19, 2026

    Regions Joint Account: Opening One Together or Adding a Partner

    By Thomas T.October 19, 2026
    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Your balances, bills, and payday. Ten minutes to one clear number.

    Download on the App Store Get it on Google Play

    Prefer the web? Sign up free ›

    Amppfy dashboard on an iPhone showing the Safe to Spend number with the math under it
    Helpful Resources

    One Household, Two Phones: Budget Apps That Work on iPhone and Android Together

    November 6, 2026

    How to Open a Joint Bank Account Online (Without a Branch Visit)

    October 19, 2026

    Regions Joint Account: Opening One Together or Adding a Partner

    October 19, 2026

    TD Bank Joint Account: How to Open One or Add a Partner

    October 19, 2026

    Financial Clarity. Everyday Confidence.

    Facebook X (Twitter) YouTube TikTok
    Calculators

    Emergency Fund Calculator

    Compound Interest Calculator

    Interest Rate Calculator

    Net Worth Calculator

    Mortgage Calculator

    How Much Home Can I Afford

    Debt-to-Income Ratio Calculator

    Cost of Living Calculator

    Savings Calculator

    Savings Goal Calculator

    Monthly Budget Calculator

    Latest Resources

    Social Security COLA 2027: What the 3.6% Raise Means for Your Monthly Plan

    November 6, 2026

    Best Free Budget Apps in 2026: iPhone, Android, and Web

    November 6, 2026

    Federal Pay Period Calendar for 2027: Every Pay Period and Payday

    November 6, 2026

    Money Manager Expense & Budget App: Price, Ads, and Simpler Alternatives in 2026

    November 6, 2026
    About & Legal

    About Amppfy

    Documentation

    Advertise with Amppfy

    Editorial Policy

    EULA

    Terms of Use

    Acceptable Use Policy

    Privacy Policy

    Cookie Policy

    Disclaimer

    Do Not Sell or Share My Personal Information

    Acceptable Use Policy

    Disclaimer: Amppfy is committed to keeping its information transparent, accurate, and up-to-date. The information on Amppfy is provided for educational and informational purposes only and should NOT be considered financial, investment, tax, or legal advice. You should consult a qualified financial professional before making any financial decisions. This information may differ from what you find on the specific product or service provider’s website. All information, content, software, tools, products, or services on Amppfy are presented without warranty or guarantee. Please review the specific provider’s terms and conditions when evaluating products or services. By accessing Amppfy or using our AI generator tools, you acknowledge that you have read, understood, and agreed to our EULA, Terms of Use, Acceptable Use Policy, Privacy Policy, Cookie Policy, and Disclaimer. Amppfy.com uses cookies. For more information, visit Amppfy’s Cookie Policy. Amppfy may be compensated through third-party advertisers and affiliates. For more information, visit Amppfy’s Disclaimer.

    Copyright© 2026 Amppfy | All Rights Reserved

    Type above and press Enter to search. Press Esc to cancel.

    Advertiser Disclosure: Products may include affiliate links related to financial products or services. We may earn a commission at no additional cost to you. Our content remains independent and focused on helping you make informed financial decisions.
    Fact Checked
    Financial Disclaimer

    This content is for informational and educational purposes only and should not be considered financial advice. Personal finance decisions—including budgeting, saving, investing, credit, mortgages, taxes, and debt management—depend on your individual circumstances. Always consult a qualified financial professional before making financial decisions.

    Editorial Standards and Content Integrity

    Our editorial process ensures accuracy, clarity, and trust across all personal finance topics, including budgeting, saving, investing, and debt management. Content is created using credible sources such as government agencies, academic research, and established financial institutions, and may incorporate insights from industry experts when relevant. Each article is reviewed for accuracy, timeliness, and relevance before publication and updated as needed to reflect changes in financial guidelines and best practices, with the goal of providing clear, evidence-based information to help readers make informed financial decisions.

    Learn more about our editorial policy and guideline.
    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Get the app on iPhone or Android and enter your balances, bills, and payday. About ten minutes to one clear number: what’s safe to spend before payday.Your balances, bills, and payday. Ten minutes to one clear number. Learn more ›

    Download on the App Store Get it on Google Play
    Scan with your phone to get the app

    Free  ·  No credit card  ·  Just your balances

    Prefer the web? Sign up free ›

    Amppfy app icon

    Amppfy

    Free on iPhone, Android, and the web

    Know what’s safe to spend before payday

    Enter your balances, bills, and payday once. About ten minutes to one clear number, with the math shown under it.

    Download on the App Store Get it on Google Play
    Scan with your phone to get the app

    Prefer the web? Sign up free ›

    Free  ·  No credit card  ·  Just your balances