
Tracking your net worth shouldn’t require handing over your bank credentials to a third party. If you’ve been using Empower Personal Dashboard and you’re rethinking that arrangement, you’re not alone. Plenty of people want a clear picture of their finances without the friction of broken syncs or the nagging question of who else can see their data. The good news: several Empower alternatives for net worth tracking work without linking a single account. Some are spreadsheets. Some are apps. All of them put you in control of your own numbers.
Why People Look for an Empower Alternative
Empower Personal Dashboard is a free tool on the web, iOS, and Android. It pulls in your accounts, shows your net worth, and tracks investments. So why leave?
The most common reason is account-linking fatigue. Connections drop. You re-enter credentials. They drop again. For some people, the convenience stops being worth the upkeep.
Security is another concern. Every linked account means a connection to your bank running through someone else’s systems. You may trust Empower’s security team, but some people would simply rather not have those connections at all.
A smaller but real group simply wants less noise. Empower’s dashboard can feel busy: investment analysis, retirement projections, spending breakdowns. If all you want is a monthly net worth number and a sense of what’s safe to spend, a simpler tool might serve you better.
What to Look for in a Replacement
Not every alternative does the same job. Before you pick one, get clear on what you actually need.
Core Features That Matter
- Net worth over time. A month-by-month chart or table showing assets minus liabilities. This is the whole point.
- Manual balance entry. You type in your numbers yourself. No bank login, no sync to babysit.
- Data portability. Can you export your history as a CSV or text file? If the tool shuts down, your data should survive.
- Speed. Updating should take minutes, not an afternoon. If it’s a chore, you’ll stop doing it.
Nice-to-Haves
- Partner access. Two people, one shared view, without sharing passwords.
- Bill and cash-flow awareness. Knowing your net worth is useful. Knowing what’s safe to spend before Friday is more useful day to day.
- Cost. Free matters, but “free with a catch” (upsells, ads, data harvesting) is worth examining.
There’s also a quieter benefit to manual entry: typing your balances forces you to look at them, which is the whole point of tracking in the first place.
The Alternatives, Compared
Here are four practical options for tracking net worth without linking accounts, each with a different personality. Prices are as listed on each company’s own site as of October 2026.
| Feature | Google Sheets / Excel | hledger (Plain Text) | Amppfy | Tiller (manual mode) |
|---|---|---|---|---|
| Cost | Free | Free (open source) | Free | $99/year after a 30-day trial |
| Manual entry | Yes | Yes | Yes | Yes (optional) |
| Net worth view | DIY formula | Reports in the terminal, terminal UI, or web UI | Built-in net worth page | Net worth template |
| Partner access | Share the file | Share the files | Invite a partner by email | Share the spreadsheet |
| Bill tracking | DIY | DIY | Bills calendar with paydays | DIY or community template |
| Where your data lives | .xlsx / .csv | Plain text files | In the app | Google Sheets or Excel |
| Learning curve | Low-medium | Medium-high | Low | Low-medium |
Google Sheets or Excel
The classic. Build a row for each month, columns for each account, and a SUM formula for net worth. It’s infinitely customizable and costs nothing. The downside: you design and maintain everything yourself. Templates help, but they still need upkeep.
hledger and Plain Text Accounting
For the technically inclined, plain text accounting tools like hledger, which is free and open source, store your financial data as simple text files. You can version-control them with Git, which means every change is logged and reversible. Your data is yours in the most literal sense: it’s a file on your computer. The trade-off is a steeper learning curve. hledger has a command line, a terminal UI, and a web UI, but it still won’t appeal to everyone.
Amppfy
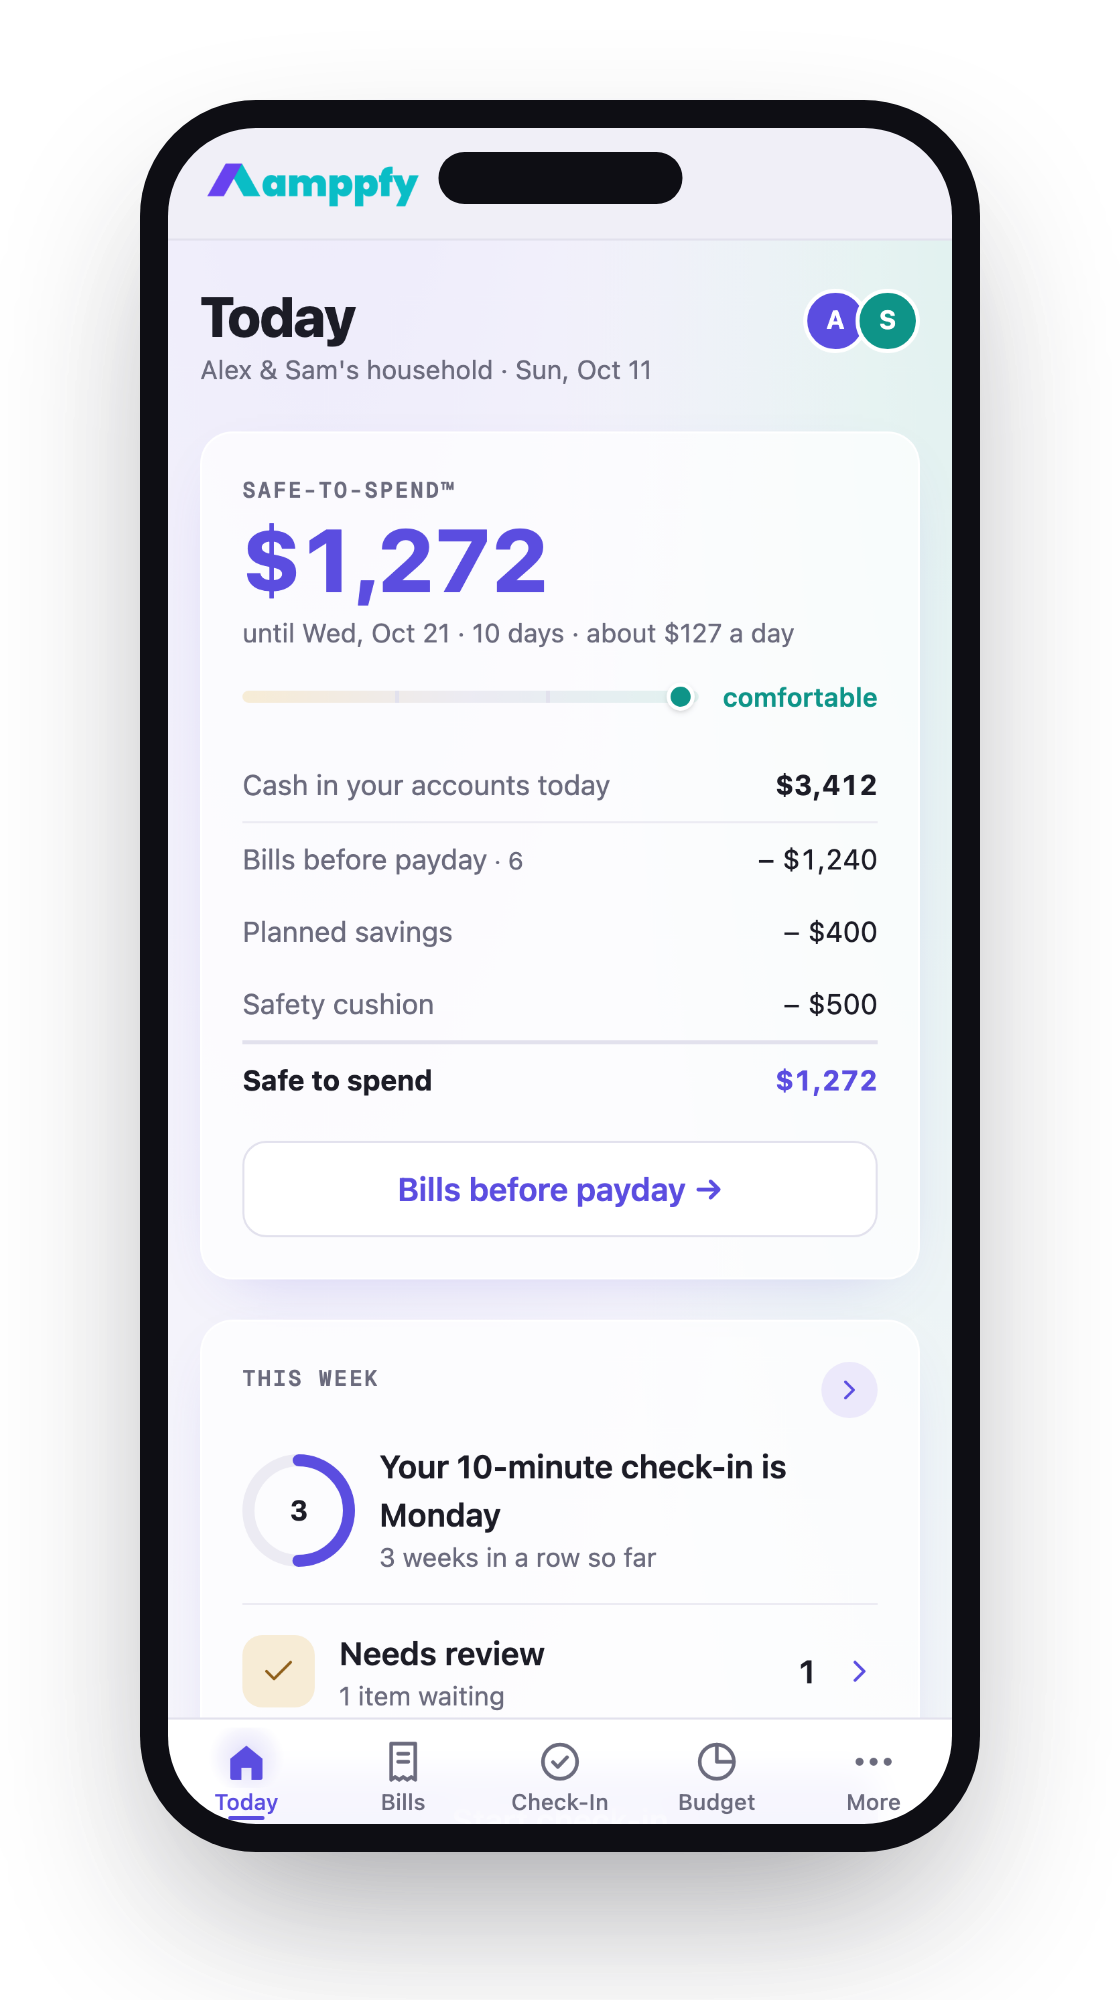
A free app on iPhone and the web. You enter your balances by hand, add your bills and payday, and it shows a single Safe-to-Spend™ number: your cash, minus bills due before payday, minus planned savings, minus a cushion you set, with the four lines of math right under it. The net worth page adds up what you own minus what you owe, and you can invite a partner by email. There’s no transaction import and no investment syncing (you type in your brokerage balance), so it won’t replace a full budgeting app, but it answers the “what’s my number” question quickly.
Tiller Money (Manual Mode)
Tiller feeds bank data into Google Sheets or Microsoft Excel, but it also supports entering balances by hand, so you can use its templates without linking accounts. The structure is already built for you, which saves time over a blank sheet. Tiller costs $99 a year after a 30-day free trial; the subscription cost is the main friction point.
Which One Fits Which Household
The right tool depends on your situation, not on a feature checklist.
- You’re a solo spreadsheet person. Google Sheets. You already know the tool. Build a simple net worth tracker in 20 minutes and update it on the first of each month.
- You’re a couple sharing bills. Amppfy fits here. Invite your partner by email and you both work from the same Safe-to-Spend™ number and net worth page, with no bank logins involved. Each of you gets your own login, and anything you keep private stays private.
- You’re a developer or data nerd. hledger. You’ll appreciate the version control and the ability to query your finances from a terminal. Nobody else will touch your data.
- You want structure without building it. Tiller’s templates give you a pre-made dashboard in Google Sheets or Excel. If you’re willing to pay $99/year, it saves you the setup work.
- You quit a budgeting app because of upkeep. Pick the tool with the least friction. A manual-balance app asks you to type a few numbers. A spreadsheet takes longer but gives you more control. Avoid anything that feels like homework.
For couples with hybrid finances (some shared, some separate), the key question is visibility. Do you both need to see the same number, or do you just need your own tracker? A shared Google Sheet works if you’re fully transparent. A manual-balance app with a partner invite works if you want one shared spending number built from the balances you both choose to enter.
How to Switch Without Losing Your History
Moving away from Empower doesn’t mean starting from zero. Here’s how to carry your data with you.
- Export your Empower history. In Empower’s web app, go to Transactions and use the CSV button to download your transaction history. The export follows the date range you select, so widen it first. Do this before you close or unlink anything, and save the file somewhere you won’t lose it: a cloud drive or a local backup.
- Run a one-month overlap. Keep both systems running for one month when you switch to manual tracking. Compare your new manual totals against Empower’s automated numbers. If they don’t match, you’ve probably missed an account or a liability.
- Set a recurring reminder. Pick a day: the 1st of the month, the day after payday, whatever sticks. Put it on your calendar. Update your balances. It should only take a few minutes.
- Build your baseline. In your new tool, enter today’s balances for every account: checking, savings, retirement, mortgage, student loans, credit cards. Assets minus liabilities equals your starting net worth. That’s the number you’ll watch move month to month.
- Delete your Empower credentials last. Once you’ve confirmed your new system captures everything, go back to Empower and unlink your accounts. Then change the passwords on any bank accounts that were connected, just as a precaution.
The one-month overlap is the step most people skip, and it’s the one that catches hidden accounts or forgotten liabilities. Don’t skip it.
Frequently Asked Questions
Is manual net worth tracking actually accurate?
Yes, if you update it consistently. Your bank’s balance is the same number whether an app pulls it automatically or you type it in. The risk isn’t accuracy: it’s forgetting to update. A monthly calendar reminder solves that. Many people find that the act of typing the number makes them more aware of where they stand.
Can I track investments without linking a brokerage account?
You can. Log into your brokerage, note the total balance, and enter it in your tracker. You won’t get automatic transaction categorization or performance analytics, but your net worth number will be correct. If you want deeper investment analysis, that’s a separate tool for a separate purpose.
What happens to my Empower data if I leave?
Empower’s web app offers a CSV export for transaction history. Download that file before you unlink accounts. Once you disconnect, you may lose access to historical data inside the app. The CSV is your safety net.
How often should I update my balances?
Once a month is enough for net worth tracking. If you’re also tracking what’s safe to spend before payday, a quick weekly balance update keeps that number honest. More often than weekly is usually unnecessary unless your cash flow is volatile.
Your Net Worth, Your Way
Tracking net worth without linking accounts isn’t a compromise. It’s a choice. You trade a few minutes of manual entry for full control over your data, zero broken syncs, and one less credential floating around on someone else’s server.
Pick the tool that matches your patience level. A spreadsheet if you like building things. hledger if you think in text files. A manual-balance app if you want a pre-built view.
If you want to see your own Safe-to-Spend™ number before your next payday, Amppfy is free on iPhone and the web. Enter your balances, bills, and payday once, then update the balances when they change. Get the app free.